

Poddar-Keventer Launches 400 Crore Real Estate Debt AIF for Delhi-NCR and West Bengal
Karthik posts articles on Energy and Construction.
Summary
Poddar Keventer Capital Advisors has launched a ₹400 crore Category II Alternative Investment Fund focused on secured real estate debt , adding another source of alternative capital for Indian property developers. The Poddar Keventer Real Estate Fund, Scheme I, has a target corpus of ₹400 crore and a ₹200 crore greenshoe option , potentially increasing its corpus to ₹600 crore. The sponsors have committed ₹80 crore , equivalent to 20% of the ₹400 crore target corpus.
Published on
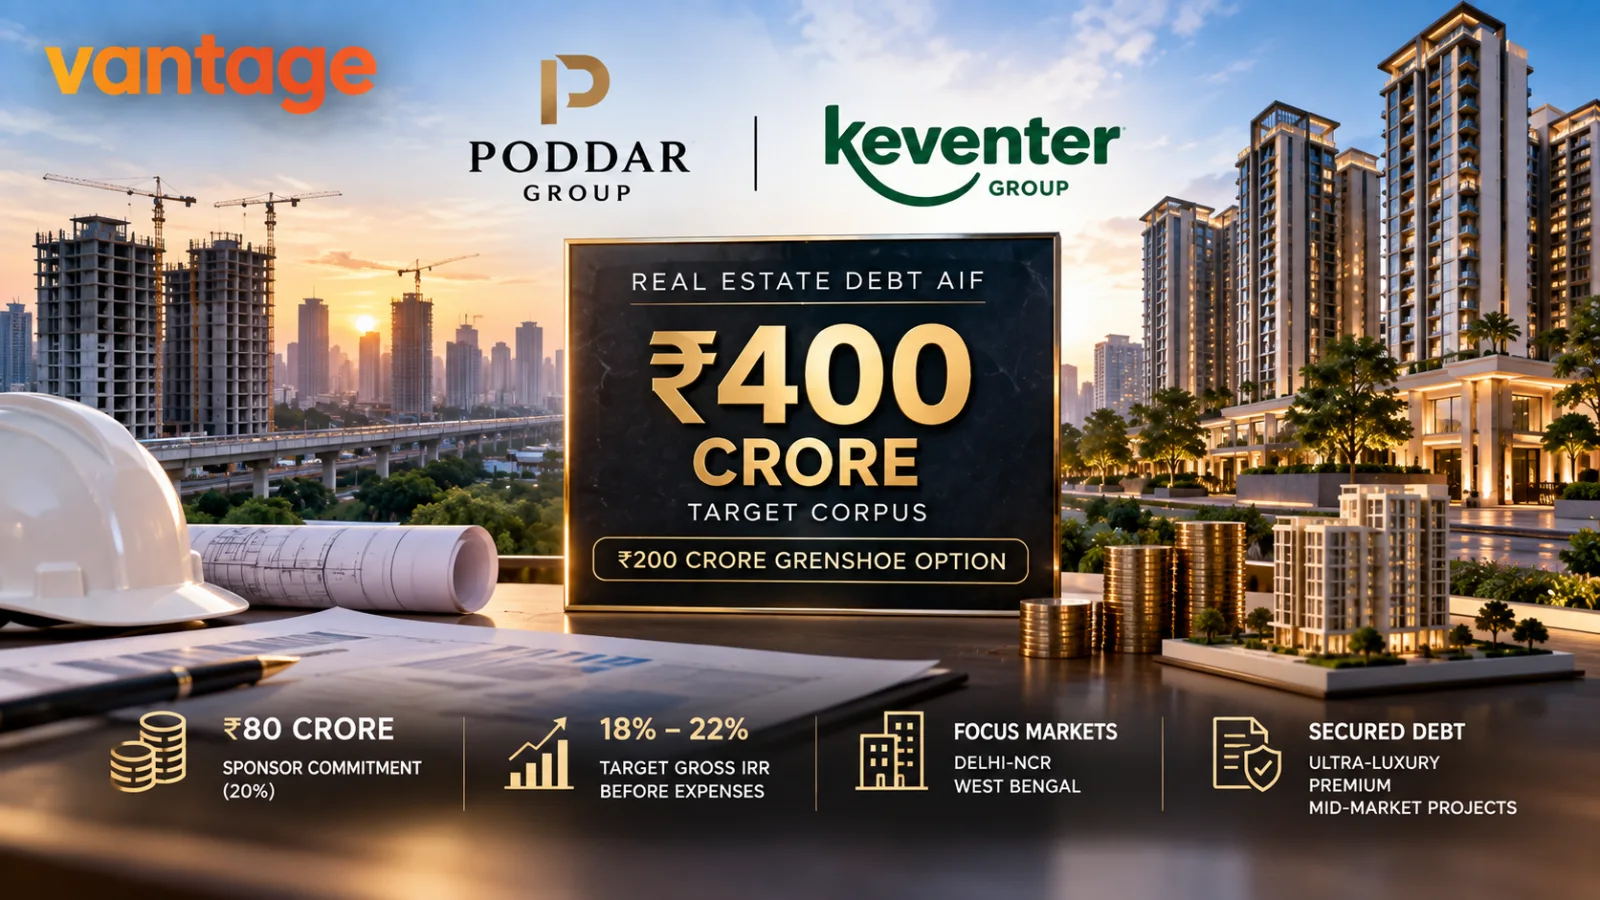
Editorial InSights banner showing residential construction, completed premium towers and financial-analysis elements around a real estate debt fund targeting 18% to 22% gross IRR before expenses. Security, cash flow, covenants, project risk and recovery cues frame the central trade-off between targeted returns and real estate credit risk.
Inline Intelligence
Poddar Keventer Capital Advisors has launched a ₹400 crore Category II Alternative Investment Fund focused on secured real estate debt, adding another source of alternative capital for Indian property developers.
The Poddar Keventer Real Estate Fund, Scheme I, has a target corpus of ₹400 crore and a ₹200 crore greenshoe option, potentially increasing its corpus to ₹600 crore.
The sponsors have committed ₹80 crore, equivalent to 20% of the ₹400 crore target corpus.
The fund plans to finance selected ultra-luxury, premium and mid-market real estate projects across Delhi-NCR and West Bengal.
It is targeting a gross internal rate of return of 18% to 22% before expenses.
That return figure needs an important qualification.
It is the fund's target gross IRR. It is not a guaranteed return to investors, and actual investor-level returns can differ after expenses and depending on investment performance.
What Is the Poddar Keventer Real Estate Fund?
The fund is being managed through Poddar Keventer Capital Advisors, an investment management platform backed by the Saroj Poddar Group and Keventer Group.
It is structured as a Category II Alternative Investment Fund.
The fund's strategy is centred on secured real estate debt rather than taking direct equity positions in property developments.
Its target corpus is:
₹400 crore
with an additional:
₹200 crore greenshoe option.
If the greenshoe is fully exercised, the potential corpus could reach ₹600 crore.
The ₹600 crore figure should not be interpreted as capital already raised or deployed.
Sponsors Have Committed ₹80 Crore
The sponsors have committed ₹80 crore to the fund.
That represents:
20% of the ₹400 crore target corpus.
This is a significant sponsor commitment relative to the target corpus and creates direct sponsor capital exposure to the fund.
However, sponsor commitment should not be interpreted as protection against investment losses.
The performance of a real estate debt fund ultimately depends on the quality of its underlying loans, projects, security structures, repayments and recoveries.
Where Will the Real Estate AIF Invest?
The fund plans to focus on opportunities across:
- Delhi-NCR; and
- West Bengal.
The strategy will cover projects across:
- ultra-luxury housing;
- premium developments; and
- mid-market real estate.
The Economic Times has also reported that the two groups plan to jointly develop approximately 11 million to 12 million sq ft over the next six years.
That development plan should be distinguished from the AIF's ₹400 crore corpus.
Project development area and investment-fund size measure different things and should not be combined into a single investment metric.
How Will the Fund Finance Real Estate Projects?
The fund plans to use a secured real estate debt strategy.
According to the disclosed investment framework, financing can include:
- security cover;
- escrow mechanisms;
- covenants;
- milestone-linked disbursements; and
- ongoing monitoring.
The objective is to structure financing around the underlying project, promoter capability and expected cash flows.
Milestone-linked drawdowns can allow capital to be released in stages rather than necessarily being provided to a project at once.
Escrow structures can also provide greater control over specified project cash flows.
But these protections do not eliminate credit or project risk.
What Does Secured Real Estate Debt Mean?
A debt AIF typically seeks to earn returns by providing financing rather than acquiring direct ownership of a development.
The distinction matters.
An equity investor generally participates more directly in the upside and downside of a property's value.
A debt investor instead focuses on:
- interest and repayment;
- collateral;
- security cover;
- cash flows;
- covenants; and
- recovery mechanisms.
Secured debt can provide contractual protections that unsecured financing does not have.
But "secured" does not mean risk-free.
If a project runs into financial trouble, recovery can still depend on asset values, legal enforceability, seniority, cash flows and the time required to realise security.
The Fund Is Targeting 18% to 22% Gross IRR
Poddar Keventer Real Estate Fund, Scheme I, is targeting a gross IRR of 18% to 22% before expenses.
This is one of the most important figures in the announcement and one of the easiest to misinterpret.
The 18% to 22% range is:
a target
and
a gross return measure before expenses.
It is not a guaranteed investor return.
Actual outcomes can be lower or higher, depending on the performance and timing of investments and repayments.
Investor-level returns can also differ from gross portfolio-level targets because of fees, expenses and the structure of the fund.
Why Would Developers Use Real Estate Debt AIFs?
Real estate development requires substantial capital before all customer collections are received.
Developers can require funding for:
- land and development obligations;
- construction;
- refinancing;
- project completion;
- working capital; and
- other project requirements.
Traditional bank lending is one source of capital.
Alternative investment funds and private credit vehicles can provide another.
Structured real estate debt can be particularly relevant where a project requires financing designed around specific cash flows, collateral and milestones.
For developers, the advantage can be flexibility.
The trade-off can be a higher cost of capital and tighter contractual protections for the lender.
Why Delhi-NCR and West Bengal?
The fund is concentrating on two geographically distinct markets.
Delhi-NCR is one of India's largest property markets, with substantial residential development across Gurugram, Noida, Greater Noida and surrounding locations.
West Bengal gives the platform exposure to the groups' home region and real estate opportunities centred particularly around Kolkata and its surrounding market.
Keventer Group Chairman and Managing Director Mayank Jalan said the groups see opportunities in both Delhi-NCR and West Bengal, supported by consumer aspirations, infrastructure-led development and demand for quality real estate.
This is the sponsor's stated investment thesis, not an independent guarantee of future market performance.
Why the ₹400 Crore Fund Matters for Real Estate Financing
The significance of the launch extends beyond the size of a single fund.
Indian developers increasingly operate within a capital market that includes more than conventional bank loans.
Funding sources can include:
- banks;
- non-banking financial companies;
- private credit;
- alternative investment funds;
- institutional equity;
- listed debt;
- customer collections; and
- developer equity.
A secured real estate debt AIF adds another potential source of project financing.
For developers, more capital providers can create additional financing options.
For investors, it creates access to a different risk-return structure from direct property ownership or listed REITs.
A Real Estate Debt AIF Is Not the Same as a REIT
Investors should not confuse real estate debt AIFs with Real Estate Investment Trusts.
A REIT generally provides exposure to a portfolio of income-producing real estate through listed units.
A real estate debt AIF can instead provide structured financing to property projects.
The return drivers are therefore different.
A REIT investor may focus heavily on:
- occupancy;
- rental income;
- distributions;
- asset valuation; and
- market price.
A real estate debt fund investor is more directly exposed to:
- borrower credit quality;
- repayment;
- interest;
- security;
- project cash flows;
- defaults; and
- recoveries.
Both involve real estate, but they are fundamentally different investment structures.
What Does This Mean for Developers?
For developers, the launch highlights the growing role of alternative capital.
A developer with a viable project but a specific financing requirement may have more options beyond conventional lending.
But structured capital comes with discipline.
The Poddar-Keventer framework refers to security cover, escrow arrangements, covenants, milestone-linked drawdowns and monitoring.
These protections can give the lender greater control over how capital is deployed and how project performance is tracked.
What Should AIF Investors Examine?
The headline target return should not be the only consideration.
Investors evaluating a real estate debt AIF need to understand factors such as:
Borrower quality
Who receives the capital and what is the promoter's execution history?
Project fundamentals
Does the underlying project have credible demand, approvals, pricing and cash-flow visibility?
Security
What assets or rights secure the financing?
Seniority
Where does the fund rank relative to other lenders if the borrower defaults?
Loan-to-value and security cover
How much protection exists relative to the exposure?
Cash-flow controls
How are project collections and repayments monitored?
Exit and repayment
What is expected to generate repayment of the debt?
Fees and expenses
How does the targeted gross return translate into potential investor-level returns after costs?
The reviewed public reports do not provide enough detail to answer all of these questions for individual future investments.
₹400 Crore Is a Target Corpus, Not Money Already Invested
This distinction is particularly important.
The fund has a ₹400 crore target corpus.
The sponsors have committed ₹80 crore.
The vehicle also has a ₹200 crore greenshoe option.
These numbers should not be interpreted as evidence that ₹400 crore or ₹600 crore has already been invested into real estate projects.
Capital raising, investor commitments, fund closings, investment deployment and repayment are different stages of the fund lifecycle.
The Bigger Signal Is the Expansion of Alternative Real Estate Capital
Poddar-Keventer's new fund is relatively focused in geographic and investment terms.
But it illustrates a broader change in how Indian property projects can be financed.
Real estate capital is increasingly coming from multiple channels, with private and alternative investment vehicles able to structure financing around individual projects and developers.
That can help viable projects access capital.
It can also shift more credit assessment and project risk into privately managed investment vehicles.
For developers, the opportunity is access to additional financing.
For AIF investors, the opportunity comes with a different set of risks.
The most important question is therefore not whether the fund targets an 18% to 22% gross IRR.
It is what level of project and credit risk is required to pursue that return, and how effectively the fund's security and monitoring framework manages that risk.
Frequently Asked Questions
What is the Poddar Keventer Real Estate Fund?
Poddar Keventer Real Estate Fund, Scheme I, is a Category II AIF focused on secured real estate debt opportunities across Delhi-NCR and West Bengal.
How large is the Poddar-Keventer real estate AIF?
The fund has a target corpus of ₹400 crore and a ₹200 crore greenshoe option, potentially taking the corpus to ₹600 crore.
How much have the sponsors committed?
The sponsors have committed ₹80 crore, equivalent to 20% of the ₹400 crore target corpus.
What return is the Poddar-Keventer fund targeting?
The fund is targeting a gross IRR of 18% to 22% before expenses. This is a target, not a guaranteed investor return.
What projects will the fund finance?
The disclosed strategy covers selected ultra-luxury, premium and mid-market real estate projects across Delhi-NCR and West Bengal.
Is secured real estate debt risk-free?
No. Security can provide additional creditor protection, but repayment and recovery still depend on project cash flows, collateral, borrower performance, legal enforceability and other risks.
Is a real estate debt AIF the same as a REIT?
No. A real estate debt AIF primarily provides financing to projects, while a REIT generally gives investors exposure to income-producing real estate through listed units.
Has the full ₹400 crore already been invested?
No evidence reviewed establishes that. ₹400 crore is the fund's target corpus, while ₹80 crore has been disclosed as the sponsors' commitment.
Sources
Click on article title to view article.
“Saroj Poddar Group, Keventer launch ₹400 crore real estate debt AIF” published on 3 October 2026 in ETRealty
“Keventer, Saroj Poddar groups launch Rs 400-cr real estate debt fund” published on 2 October 2026 in The Economic Times
“Poddar Keventer Capital Advisors to raise up to Rs 400 crore for maiden real estate AIF” published on 2 October 2026 in The Economic Times
“Saroj Poddar, Keventer launch Rs 400cr real estate AIF, first from eastern India” published on 2 October 2026 in The Times of India
“Securities and Exchange Board of India (Alternative Investment Funds Regulations, 2012 [Last amended on July 14, 2026]” published on 14 July 2026 by SEBI
Related Vantage Coverage
Click on article title to view article.
“Gurugram RERA Approves 51 Projects Worth ₹38,000 Crore in H1 2026” published on 30 July 2026 in Vantage-Radar
“Six listed Indian REITs distribute Rs 3,136 crore to investors in Q1 FY27” published on 17 August 2026 in Vantage-Radar
Evidence Caveats
- ₹400 crore is the target corpus, not verified deployed capital.
- ₹600 crore is the potential corpus if the ₹200 crore greenshoe option is exercised.
- ₹80 crore is the disclosed sponsor commitment, equal to 20% of the ₹400 crore target corpus.
- The 18% to 22% figure is a target gross IRR before expenses, not a guaranteed return.
- Security cover, escrow arrangements and covenants can mitigate certain risks but do not eliminate credit, project or recovery risk.
- Public reports reviewed do not provide complete terms for individual future loans, including borrower-level pricing, loan-to-value ratios, security ranking, duration or recovery assumptions.
- The reported 11 million to 12 million sq ft development plan should not be confused with the size of the AIF.

From TatvaOps
Property Development
Developing a property?
Structured oversight for multi-unit and investor-led builds.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this Radar article is filed under Radar.
More from Real Estate
LTCG and STT: Review Reports Do Not Mean a Tax Cut
Finance Minister Nirmala Sitharaman’s comments on equity taxation have reopened a consequential debate for investors. Speaking at the Bloomberg New Economy Forum in New Delhi on 13 October, she welcomed views on long term capital gains tax and securities transaction tax without committing to…
Blackstone Targets 100 Billion in India Investments
Blackstone aims to double its India investments to approximately $100 billion over about five years, president and chief operating officer Jonathan Gray said in interviews reported this week. The ambition spans private equity and real estate, alongside potential expansion in infrastructure, credit…
Property Registrations Flagged Over Fictitious PAN
Nearly 25,000 property registrations over two years at Badshahpur tehsil in Gurugram reportedly carried the same fictitious PAN, according to The Times of India’s 9 October report on an Income Tax Department survey. The finding raises questions about taxpayer identification and transaction…
Inline Intelligence
Key Insight Actions
Connected knowledge for Real Estate Financing
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
GST ITC Relief Could Change Commercial Real Estate Economics, but How Much Would Developers Actually Save?
1 replies
Related discussionDelhi-NCR Home Prices Rose 12 While Sales Fell: Is Luxury Housing Distorting the Market?
1 replies
Related discussionWest Bengal May Scrap the Urban Land Ceiling Act: Will It Make Kolkata Real Estate Cheaper or More Expensive?
1 replies
Related discussionPoddar-Keventer Targets 18 to 22 Gross IRR: What Risk Sits Behind Real Estate Debt AIF Returns?
2 replies
Related discussion
Topic hubs
Conclusion Intelligence
Related Discussions
GST ITC Relief Could Change Commercial Real Estate Economics, but How Much Would Developers Actually Save?
Popular in insights discussions1 reply
Delhi-NCR Home Prices Rose 12 While Sales Fell: Is Luxury Housing Distorting the Market?
Popular in insights discussions1 reply
West Bengal May Scrap the Urban Land Ceiling Act: Will It Make Kolkata Real Estate Cheaper or More Expensive?
Popular in insights discussions1 reply
Poddar-Keventer Targets 18 to 22 Gross IRR: What Risk Sits Behind Real Estate Debt AIF Returns?
Popular in insights discussions2 replies
Was this helpful?
Let us know what you think