

GST Council May Consider Input Tax Credit Relief for Real Estate and Construction on 8 October
Karthik posts articles on Energy and Construction.
Summary
India's GST Council may consider changes to input tax credit rules affecting real estate, construction and infrastructure when it meets on 8 October 2026. The proposals could revisit situations in which businesses pay GST on construction related inputs but cannot claim the corresponding input tax credit because the resulting asset is treated as immovable property. For commercial real estate, infrastructure and other capital intensive businesses, blocked ITC can effectively become part of the project's cost. But the most important point is also the simplest: No new real estate ITC relief has yet been approved.
Published on
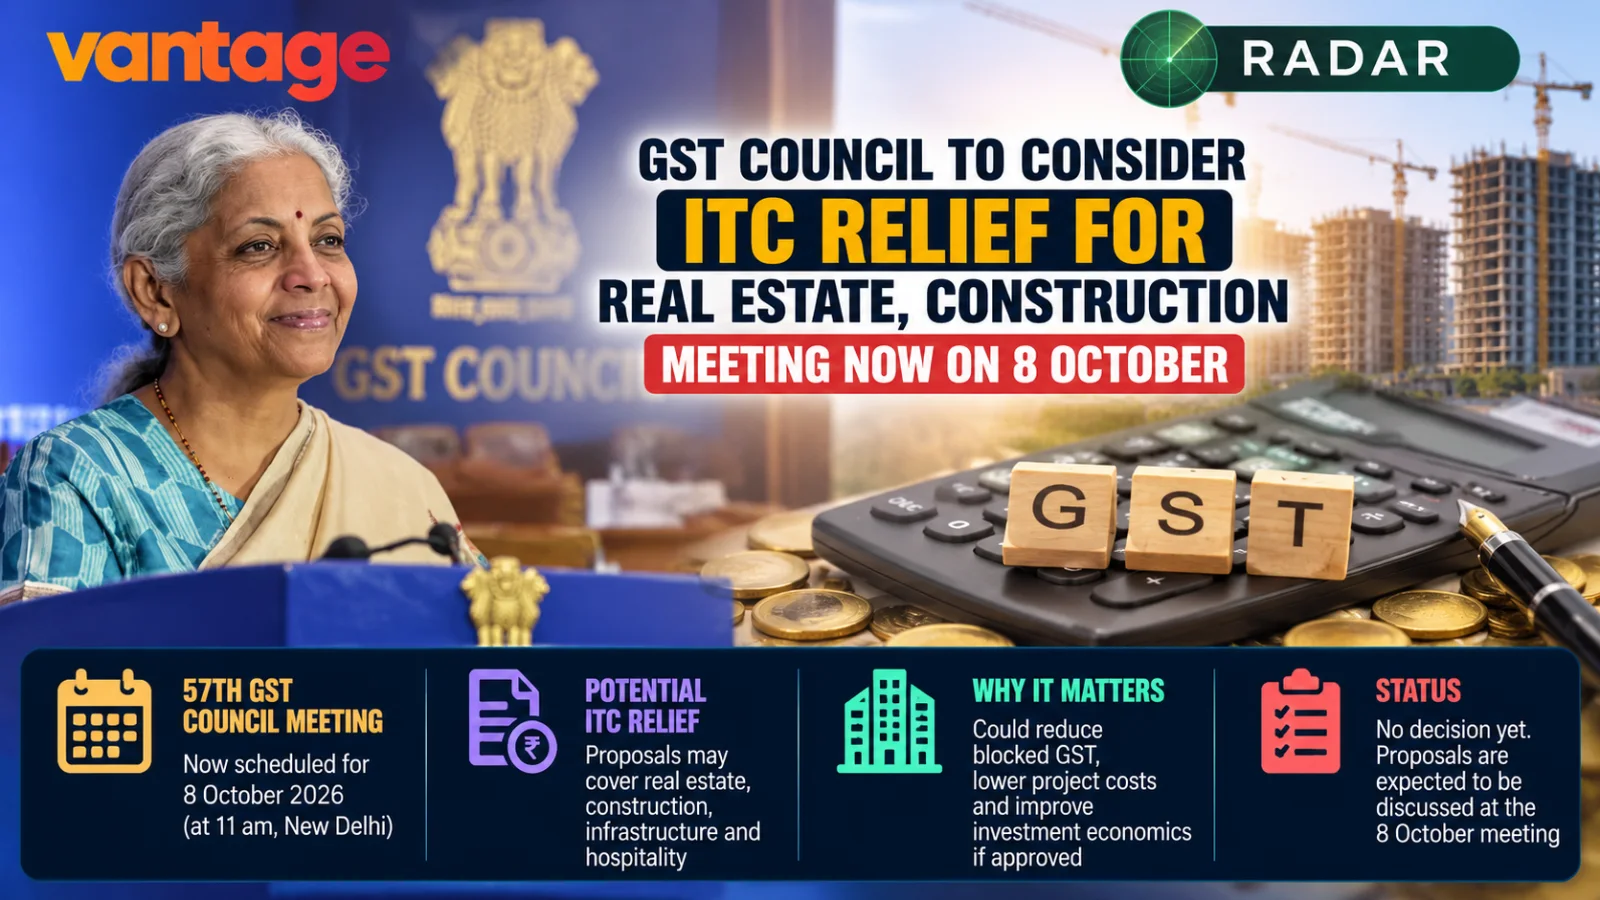
banner illustrating the potential impact of GST input tax credit reform on Indian real estate economics. The visual combines Parliament, residential construction, cranes, GST-related financial imagery and a property professional assessing a development, highlighting possible implications for embedded GST costs, project capital requirements and investment returns. The banner also emphasises that the proposals remain under consideration ahead of the 57th GST Council meeting on 8 October 2026.
Inline Intelligence
India's GST Council may consider changes to input tax credit rules affecting real estate, construction and infrastructure when it meets on 8 October 2026.
The proposals could revisit situations in which businesses pay GST on construction-related inputs but cannot claim the corresponding input tax credit because the resulting asset is treated as immovable property.
For commercial real estate, infrastructure and other capital-intensive businesses, blocked ITC can effectively become part of the project's cost.
But the most important point is also the simplest:
No new real estate ITC relief has yet been approved.
The measures under discussion remain proposals ahead of the 57th GST Council meeting.
GST Council Meeting Rescheduled to 8 October
The 57th GST Council meeting was originally scheduled for 7 October.
The GST Council Secretariat subsequently moved it to 8 October 2026, citing unavoidable circumstances.
The meeting is scheduled to begin at 11 am at Bharat Mandapam in New Delhi.
The Council is expected to focus heavily on process reforms, including input tax credit, refunds, registration and dispute-related issues.
What Is the Real Estate ITC Issue?
Input tax credit is intended to allow a GST-registered business to offset eligible GST paid on inputs against GST collected on taxable supplies.
But the CGST Act contains restrictions.
Section 17(5) blocks ITC in specified situations involving the construction of immovable property.
That can create a significant issue for businesses constructing assets that they intend to retain and use commercially.
A business may incur GST on construction materials and services but be unable to use all of that tax as a credit.
Where credit is blocked, the tax can become part of the economic cost of the asset.
Why This Matters for Commercial Real Estate
The issue is particularly relevant for income-producing property.
Consider a business constructing an office building, shopping centre, hotel or another commercial asset that it intends to retain.
Construction requires numerous taxable inputs and services.
If GST paid on eligible inputs can be credited, part of the tax burden can be offset.
If the credit is blocked, more of the GST becomes embedded in project cost.
This can influence:
- project economics;
- capital requirements;
- return calculations;
- leasing economics; and
- investment decisions.
The actual effect varies by asset and tax structure.
What Could the GST Council Consider?
Business Standard reports that proposals before the Council include rationalising ITC treatment in real estate and construction where assets directly serve business activity.
One specific area concerns pipelines laid outside factory premises.
Under the existing definition of plant and machinery, pipelines outside factory premises are excluded.
The proposals could reconsider the treatment of such infrastructure.
The discussions also extend beyond conventional real estate to infrastructure, hospitality, tourism and other business assets.
The final scope will only become clear if the Council approves recommendations and the government subsequently issues the necessary legal changes.
This Is Not Yet a Tax Cut for Homebuyers
The proposal should not be described as a reduction in GST on residential property.
Nor does the available evidence establish that home prices will fall if the proposals are approved.
The current discussion concerns input tax credit rules.
Any effect on project economics would depend on:
- which assets become eligible;
- whether the relief is prospective or retrospective;
- the exact legal drafting;
- developers' cost structures;
- project type; and
- whether any cost benefit is eventually reflected in pricing.
Until the Council acts, none of those outcomes can be quantified reliably.
The Issue Has a Complicated Legal History
The treatment of construction-related ITC has already been the subject of major litigation.
In October 2024, the Supreme Court's Safari Retreats judgment examined whether certain immovable property could qualify as "plant" under Section 17(5)(d).
The Court said a functionality test could be applied on a case-by-case basis.
The GST Council subsequently recommended changing the wording of Section 17(5)(d) from "plant or machinery" to "plant and machinery" retrospectively from 1 July 2017.
The Finance Act 2025 implemented that change.
The amendment significantly restricted the potential benefit that commercial property owners had expected from the Safari Retreats ruling.
Why Safari Retreats Still Matters
The case illustrates the central tax-policy problem.
A commercial building can generate taxable business activity, such as leasing.
But GST paid during construction may nevertheless be blocked because the expenditure creates immovable property.
Businesses argue that this can break the normal GST credit chain and embed tax in investment costs.
The government's earlier position was that GST is not levied on the sale of completed immovable property, creating a reason to restrict credit in the construction chain.
The competing objectives are therefore:
avoiding cascading tax on business investment
and
protecting the intended boundary around immovable-property credits.
What Would ITC Relief Actually Change?
If a business becomes entitled to claim credit that is currently blocked, the immediate accounting effect can be lower embedded tax cost.
A simplified example illustrates the mechanism.
Suppose a qualifying business incurs:
₹100 crore of eligible taxable construction expenditure
plus
₹18 crore of GST.
If all ₹18 crore were blocked, the economic construction cost could effectively become ₹118 crore.
If the ₹18 crore became fully creditable and could be utilised, the effective cost before financing and other considerations could move closer to ₹100 crore.
This is an editorial illustration only.
It is not an estimate of the proposed reform's actual benefit.
The applicable GST rates, eligibility, utilisation and project structures vary substantially.
Relief Could Affect Investment Returns
Lower embedded construction tax can improve project economics.
For an income-producing asset, that could potentially influence:
- project IRR;
- development yield;
- required rent;
- payback period; and
- capital allocation.
But no uniform percentage improvement can currently be calculated.
The GST Council has not approved the proposal and the final scope is unknown.
Developers Should Not Reprice Projects Yet
The current discussion is not sufficient basis for changing project underwriting.
Developers and investors need to wait for:
- the GST Council's recommendation;
- the exact categories receiving relief;
- effective dates;
- transitional provisions;
- subsequent legislation or notifications where required; and
- implementation guidance.
A Council discussion does not itself rewrite the CGST Act.
Could This Benefit Office Developers?
Potentially, depending on the final drafting.
Commercial office developers and owners can face blocked construction ITC even when completed buildings generate taxable rental income.
If the government expands eligibility for specified business-use assets, some commercial projects could see lower embedded tax costs.
But the current accessible reporting does not establish that ordinary office construction will receive blanket ITC eligibility.
That distinction should be preserved.
Could Warehousing and Logistics Benefit?
Potentially.
Warehouses, logistics infrastructure and industrial facilities often combine buildings with specialised equipment, installations and infrastructure.
ITC eligibility can therefore depend on how individual components are legally classified.
Any reform clarifying business-use assets could reduce uncertainty for some projects.
Again, the benefit cannot be quantified until the final provisions are available.
Hospitality Could Also Be Relevant
Business Standard reports that wider ITC proposals involving hospitality, tourism and wellness are also under consideration.
Hotels are capital-intensive operating assets.
Construction and fit-out taxation can therefore materially influence investment cost.
But hospitality relief should not be assumed to be identical to any eventual real estate or infrastructure provision.
Each proposal needs to be evaluated separately after the Council decision.
The Bigger GST 2.0 Agenda
The meeting is broader than real estate.
The government is considering reforms involving:
- input tax credit;
- refunds;
- registration;
- return filing;
- disputes;
- e-commerce compliance; and
- treatment of certain exports of services.
Finance Minister Nirmala Sitharaman has described the next stage as process reform under GST 2.0.
The government is therefore moving from the earlier rate-rationalisation exercise towards the mechanics of how businesses claim credits, receive refunds and comply with GST.
Why Real Estate Should Watch 8 October
Real estate is unusually sensitive to blocked tax because development requires large upfront capital expenditure.
Even relatively small changes in embedded project cost can affect investment underwriting.
But the sector should avoid treating the upcoming meeting as a guaranteed tax windfall.
The key question is not:
Will GST disappear from construction?
It will not.
The relevant question is:
Will businesses be allowed to recover a larger portion of GST already paid on qualifying construction and infrastructure expenditure?
The answer will depend on the Council's final recommendations.
What Should Developers Watch in the GST Council Decision?
Eligible assets
Which buildings, infrastructure or business-use assets qualify?
Effective date
Is relief prospective or retrospective?
Plant and machinery definition
Are specific exclusions changed?
Own-account construction
Does the treatment of assets constructed and retained by businesses change?
Leasing
Does the Council provide any relief relevant to commercial properties generating taxable rental income?
Transitional credit
Can businesses recover any previously blocked ITC?
Legal mechanism
Does implementation require amendment of the CGST Act, rules or notifications?
These details will determine whether the reform is narrow or economically significant.
Frequently Asked Questions
Is the GST Council reducing GST on real estate?
No such decision has been made. The current discussion concerns potential input tax credit reforms, not a confirmed reduction in GST rates on property.
When is the next GST Council meeting?
The 57th GST Council meeting has been rescheduled to 8 October 2026.
What is input tax credit in real estate?
ITC allows eligible GST paid on business inputs and services to be offset against GST liability. Certain construction-related credits are currently blocked under Section 17(5) of the CGST Act.
Has ITC relief for real estate been approved?
No. Proposals may be considered by the GST Council. Final recommendations are not yet available.
Could ITC reform reduce construction costs?
Potentially, for expenditure that becomes creditable. The actual benefit will depend on the final eligibility rules and cannot currently be quantified.
Will home prices fall if ITC rules change?
There is no evidence supporting a specific home-price reduction. Any pricing impact would depend on the scope of reform, project economics, competition and developer pricing decisions.
What was the Safari Retreats GST case?
The Supreme Court considered ITC eligibility for construction of immovable property used for business. Its 2024 ruling introduced a functionality test, after which the law was retrospectively amended in 2025 to restrict the interpretation.
Which real estate segments could be affected?
Commercial real estate, industrial assets, infrastructure, warehousing and hospitality could potentially be relevant, depending on the final Council recommendations. Blanket eligibility should not be assumed.
Sources
Click on article title to view article.
“GST Council may consider ITC rationalisation for real estate, construction” published on 5 October 2026 in Business Standard
“Govt reschedules GST Council meet to 8 October citing ‘unavoidable circumstances’” published on 5 October 2026 in Moneycontrol
“GST Council to take up process reforms at October 7 meeting: FM Sitharaman” published on 16 September 2026 in Business Standard
Primary Document
“55th Meeting of the GST Council” published by the Goods and Services Tax Council
Evidence Caveats
- No real estate or construction ITC relief has yet been approved at the 57th GST Council meeting.
- The meeting is now scheduled for 8 October 2026, not 7 October.
- The exact scope of the real estate and construction proposals remains subject to Council deliberation.
- Accessible evidence does not establish blanket ITC eligibility for office, retail, warehouse, hotel or residential construction.
- Any project-cost example in this article is illustrative and not an estimate of savings from the proposed reform.
- No reliable evidence currently supports a specific reduction in home prices, rents, construction costs or project IRRs.
- Any Council recommendation may require subsequent legislation, rules or notifications before taking effect.

From TatvaOps
Residential Construction
Financing your project?
Explore credit and milestone-secured payment options with Tatva Finance.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this Radar article is filed under Radar.
More from Real Estate
LTCG and STT: Review Reports Do Not Mean a Tax Cut
Finance Minister Nirmala Sitharaman’s comments on equity taxation have reopened a consequential debate for investors. Speaking at the Bloomberg New Economy Forum in New Delhi on 13 October, she welcomed views on long term capital gains tax and securities transaction tax without committing to…
Blackstone Targets 100 Billion in India Investments
Blackstone aims to double its India investments to approximately $100 billion over about five years, president and chief operating officer Jonathan Gray said in interviews reported this week. The ambition spans private equity and real estate, alongside potential expansion in infrastructure, credit…
Property Registrations Flagged Over Fictitious PAN
Nearly 25,000 property registrations over two years at Badshahpur tehsil in Gurugram reportedly carried the same fictitious PAN, according to The Times of India’s 9 October report on an Income Tax Department survey. The finding raises questions about taxpayer identification and transaction…
Inline Intelligence
Key Insight Actions
Connected knowledge for Tax Policy
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Topic hubs
Conclusion Intelligence
Related Discussions
GST ITC Relief Could Change Commercial Real Estate Economics, but How Much Would Developers Actually Save?
Popular in insights discussions1 reply
Ajmera Wants a 2 Million Sq Ft Mumbai Rental Portfolio: Can a Residential Developer Build a REIT-Ready Income Business?
Popular in insights discussions1 reply
Was this helpful?
Let us know what you think