
Nifty 50 Valuations Near Decade-Low Growth Measure
Summary
India's Nifty 50 index is approaching one of its most attractive growth adjusted valuation levels in a decade, but analysts remain divided over whether the stock market is genuinely inexpensive. Research cited by The Economic Times on 26 October 2026 indicates that the Nifty's price/earnings to growth PEG ratio is approaching 1, while its forward price to earnings P/E multiple has declined sharply from its September 2024 level. According to Bajaj Asset Management, the Nifty 50's 12 month forward P/E declined from 24.8 times in September 2024 to 17.2 times in September 2026.
Published on
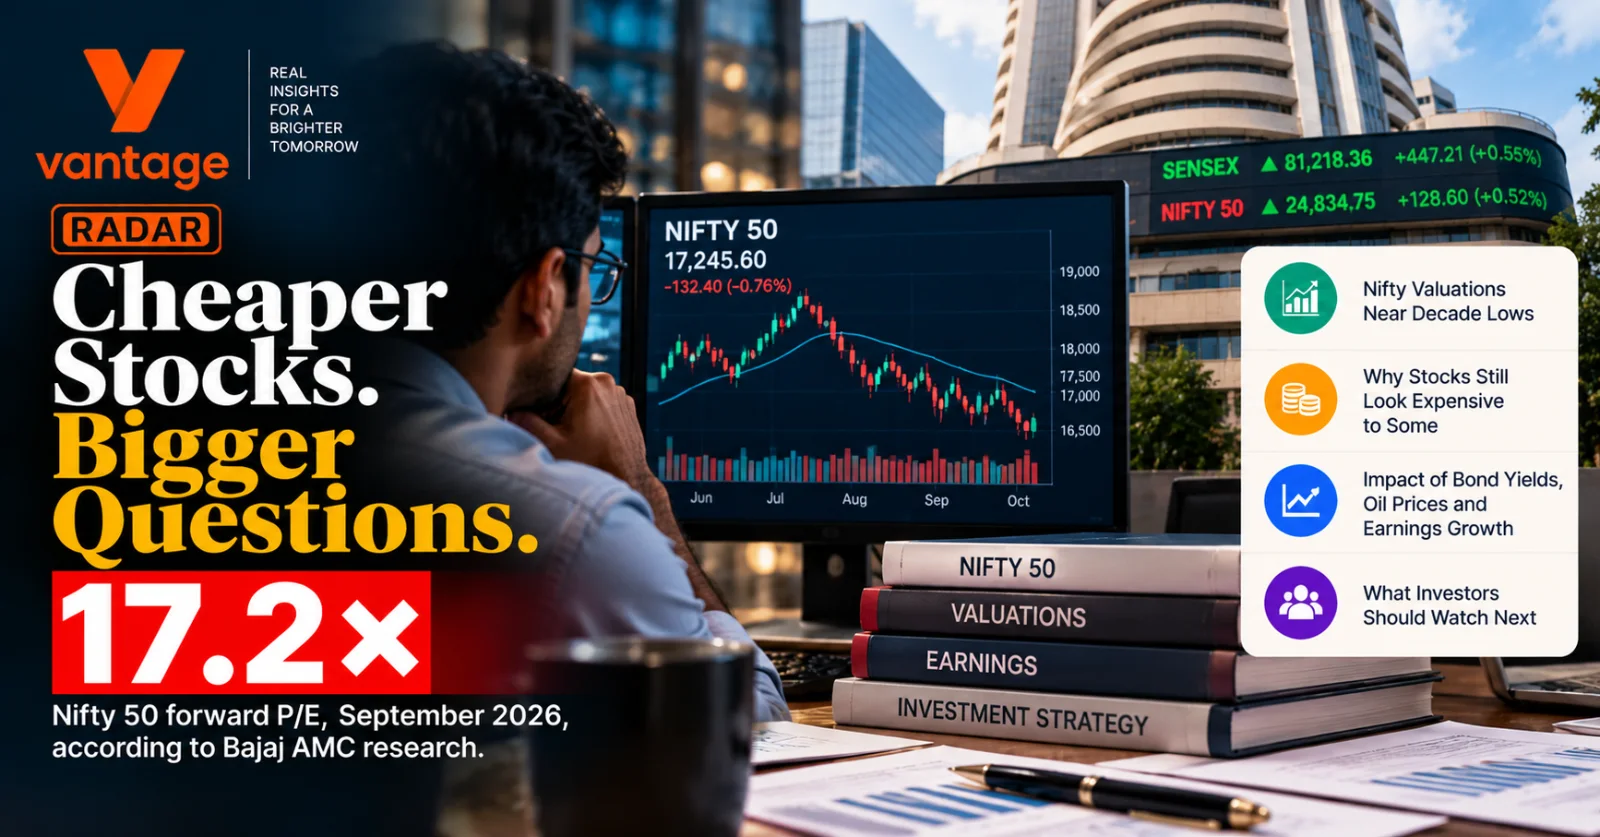
India's Nifty 50 forward P/E ratio fell to 17.2× in September 2026, signalling lower stock market valuations. The image highlights investor uncertainty over earnings growth, bond yields and oil prices, raising questions about whether Indian equities are genuinely undervalued
Inline Intelligence
India's Nifty 50 index is approaching one of its most attractive growth-adjusted valuation levels in a decade, but analysts remain divided over whether the stock market is genuinely inexpensive.
Research cited by The Economic Times on 26 October 2026 indicates that the Nifty's price/earnings-to-growth (PEG) ratio is approaching 1, while its forward price-to-earnings (P/E) multiple has declined sharply from its September 2024 level.
According to Bajaj Asset Management, the Nifty 50's 12-month forward P/E declined from 24.8 times in September 2024 to 17.2 times in September 2026.
That represents a reduction of approximately 30.6% in the valuation multiple.
The apparent improvement comes with an important qualification: expectations of stronger corporate earnings have yet to be fully tested against higher financing costs and weaker economic conditions.
Why Are Nifty Valuations Falling?
A forward P/E ratio compares an index's current price with its expected earnings over a future period.
A declining multiple means investors are paying less for each rupee of forecast earnings.
This can happen when share prices fall, projected earnings rise, or both occur simultaneously.
Bajaj AMC's analysis, reported by The Economic Times on 26 October, found that the Nifty 50 declined approximately 8% year-on-year in September 2026, while its 12-month forward earnings-per-share estimate rose 9.62%.
The combination helped lower the index's valuation multiple.
This does not necessarily mean every Nifty constituent has become equally attractive.
Each company has different earnings prospects, financial strength and sensitivity to economic conditions.
What Is the PEG Ratio Signalling?
The PEG ratio compares a company's or index's P/E multiple with its expected earnings growth rate.
A PEG ratio near 1 is sometimes interpreted as indicating a more balanced relationship between valuation and growth expectations.
ICICI Securities research cited by Economic Times described the Nifty's PEG ratio as approaching its most attractive zone in roughly a decade.
The analysis pointed to a forward valuation near 17 times earnings and consensus expectations of approximately 15% earnings growth in FY2027.
However, a low PEG ratio is not proof that a market is undervalued.
Its interpretation depends heavily on the accuracy and sustainability of earnings-growth estimates.
If projected growth is revised downward, a seemingly attractive PEG ratio can quickly become less favourable.
Are Mid-Cap and Small-Cap Stocks Also Cheaper?
Valuation compression has not been uniform across the Indian equity market.
Bajaj AMC's analysis reported that the Nifty Midcap 150 forward P/E declined from 35.6 to 22.8 between September 2024 and September 2026.
The Nifty Smallcap 250 multiple declined from 25 to 23.2 over the same period.
The magnitude of the reset therefore differed substantially across market-capitalisation categories.
Separate research cited by The Economic Times suggested that mid-cap valuations remained above their long-term averages even after recent corrections.
The figures indicate that the broader market cannot be assessed using the Nifty 50's valuation alone.
Why Are Investors Still Cautious?
Analysts identify several reasons why lower headline valuations have not immediately translated into stronger investor confidence.
Higher bond yields: When relatively lower-risk fixed-income instruments offer more attractive yields, equity investments may need to provide greater expected returns to compensate investors for volatility.
Earnings uncertainty: Expected corporate profits can be revised downward if economic conditions deteriorate.
Elevated crude oil prices: Higher energy costs can pressure business margins, inflation and India's external accounts.
Foreign capital flows: Currency movements and changing global interest-rate expectations can influence overseas investors' allocation decisions.
Nuvama Research, cited by Economic Times, argued that valuations need to be evaluated relative to interest rates and earnings expectations rather than historical multiples alone.
It cautioned that even an index trading around 17 times forward earnings might not offer an adequate margin of safety if bond yields remain elevated or earnings forecasts weaken.
How Does India Compare With Emerging Markets?
A separate Economic Times report published on 26 October examined India's valuations relative to other emerging markets.
It reported that the dollar-denominated MSCI India Index traded at approximately 18.5 times forward earnings, its lowest level since May 2020.
That figure was below its reported 10-year average of 19.7 times.
However, the MSCI Emerging Markets Index traded at approximately 8.7 times forward earnings.
The comparison suggests that Indian equities continued to command a substantial valuation premium over the wider emerging-market benchmark.
Whether that premium is justified depends on relative earnings growth, risk, business quality and other factors.
The MSCI figures use a different index and methodology from the Nifty valuation figures and should not be treated as interchangeable.
What Could Change the Outlook?
The next important development is the delivery of corporate earnings.
Bajaj AMC expects BSE 500 earnings to grow 17% in FY2027 and 16% in FY2028.
These are forecasts, not realised results.
If corporate profits meet or exceed expectations, lower valuation multiples could provide a stronger basis for future returns.
If earnings disappoint, however, the apparent valuation advantage may weaken.
Changes in oil prices, bond yields, currency movements and global capital flows could also influence the outlook.
The central development is clear: Indian large-cap valuations have become considerably less expensive than they were in 2024.
Whether they have become genuinely attractive remains an open question.
What matters more when assessing the Nifty today: its lower valuation multiple, expected earnings growth or the risks created by higher interest rates? Share your reasoning in the attached forum discussion.
Sources
Click an article title to view the source.
- Nifty's PEG ratio near 10-year low but why don't stocks look cheap yet? Valuation paradox explained, published on 26 October 2026 in The Economic Times.
- India valuations hit six-year low, but more expensive than emerging market peers, published on 26 October 2026 in The Economic Times.
- Nifty valuations near post-Covid lows: Alchemy Capital's Alok Agarwal explains what investors should buy now, published on 2 October 2026 in The Economic Times.
From TatvaOps
Residential Construction
Comparing contractor quotes?
Line up pricing, scope, and timelines before you sign.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this Radar article is filed under Radar.
More from Real Estate
Mumbai Luxury Homes Record 3145 Registrations
An industry report records 3,145 registrations of homes priced at Rs 5 crore or more in the Mumbai region in April to September 2026.
Binance Reports Security Incident and Asset Freeze
Binance estimates a $6.3 billion incident impact and says about $3 billion was frozen; withdrawals remain paused, it reports.
Haryana Pauses Gurugram Parallel Power Licence
HERC has halted further action on a parallel power licence for Gurugram and Nuh while Haryana government directions remain operative.
Inline Intelligence
Key Insight Actions
Connected knowledge for Equity Valuation
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Topic hubs
Conclusion Intelligence
Related Discussions
Was this helpful?
Let us know what you think