
L&T Q2 Profit Rises 33 as Order Book Hits Record
Summary
Larsen & Toubro reported a 33% rise in quarterly net profit to ₹5,202 crore, supported by higher revenue and record order inflows. But rising input and logistics costs are putting pressure on parts of its infrastructure business. L&T Reports Strong September Quarter Results Larsen & Toubro announced its financial results on 27 October 2026 for the quarter ended 30 September. Consolidated revenue rose 16% year on year to ₹78,750 crore, while profit after tax increased approximately 33% to ₹5,202 crore.
Published on
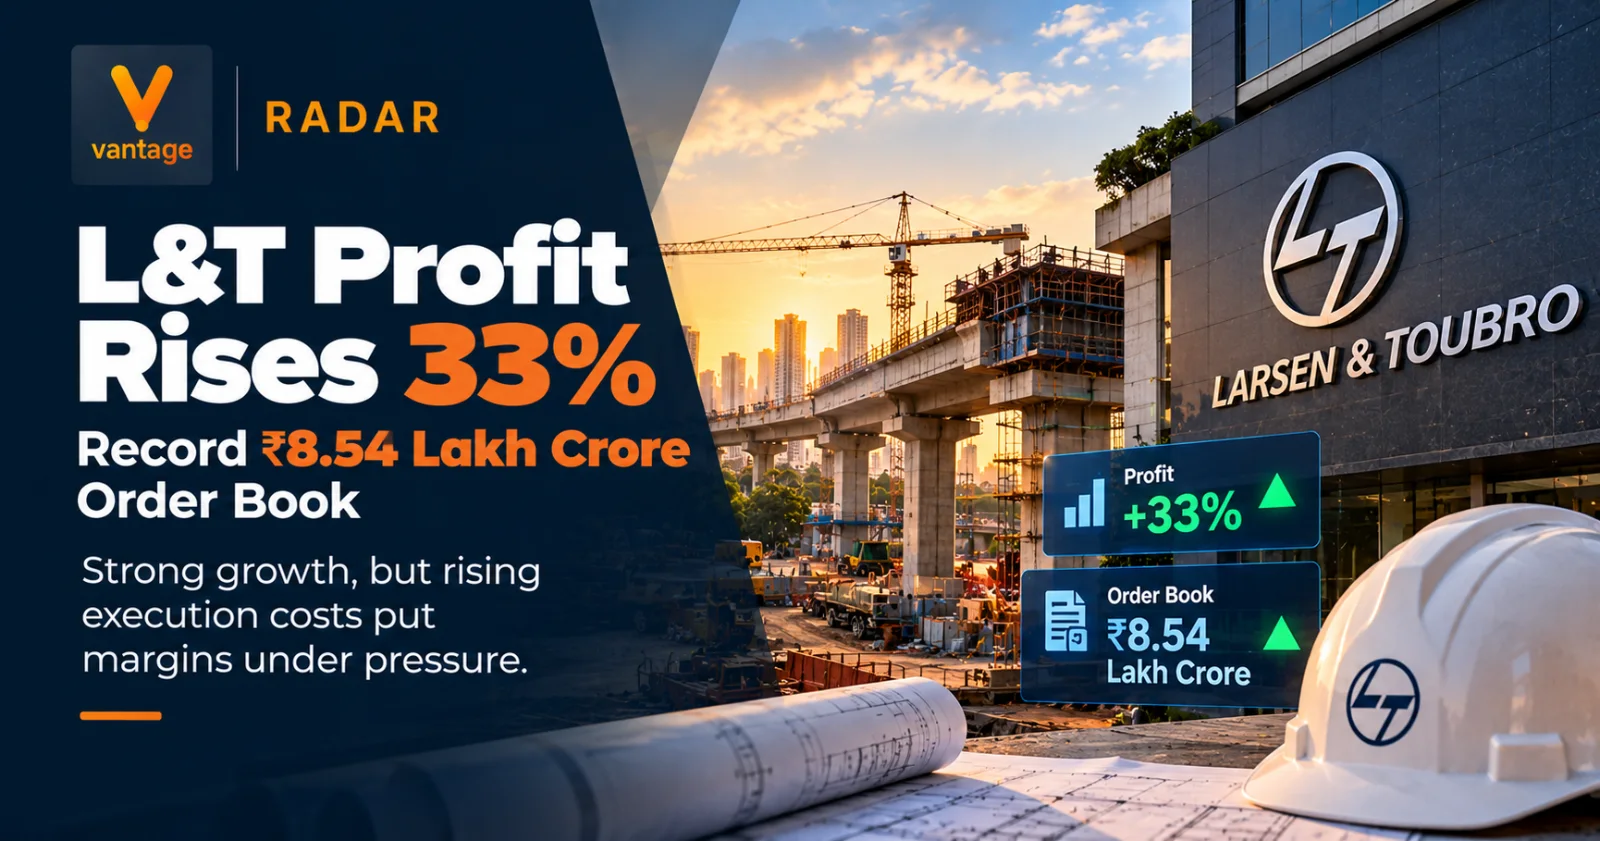
Larsen & Toubro reports a 33% rise in quarterly profit and a record ₹8.54 lakh crore order book for Q2 FY2026–27. Strong infrastructure and engineering orders support growth, while rising material and logistics costs put pressure on project execution margins.
Larsen & Toubro reported a 33% rise in quarterly net profit to ₹5,202 crore, supported by higher revenue and record order inflows. But rising input and logistics costs are putting pressure on parts of its infrastructure business.
L&T Reports Strong September-Quarter Results
Larsen & Toubro announced its financial results on 27 October 2026 for the quarter ended 30 September.
Consolidated revenue rose 16% year on year to ₹78,750 crore, while profit after tax increased approximately 33% to ₹5,202 crore.
The engineering and construction major secured new orders worth ₹1,47,665 crore during the quarter, representing 28% year-on-year growth.
Its consolidated outstanding order book reached ₹8,53,514 crore as of 30 September 2026, approximately 15% higher than at the end of March.
The order book is the value of work yet to be executed, not revenue already earned.
International Projects Drive Order Growth
International orders accounted for ₹92,375 crore, or approximately 63% of quarterly order inflows.
L&T secured substantial orders across hydrocarbons, public spaces and airports, power transmission and distribution, and other engineering businesses.
International contracts represented approximately 54% of its outstanding order book.
This geographical spread provides substantial project opportunities, but it also exposes the company to political instability, transport disruptions and overseas execution risks.
Higher Costs Weigh on Infrastructure Margins
Despite the stronger consolidated results, not every business segment recorded improving profitability.
The Infrastructure & Utilities segment reported new orders worth ₹35,509 crore, down 13% year on year as some targeted awards were deferred.
Its EBITDA margin declined from 6.2% to 5.7%.
Management attributed execution difficulties to domestic and international disruptions, increased input costs and higher logistics expenses.
The distinction matters: winning more projects does not automatically produce higher margins.
Middle East Projects Remain Important
Middle East infrastructure and energy investments are major contributors to L&T's international business.
Regional geopolitical tensions have created concerns about project delivery and transportation costs.
Nevertheless, the company maintained its FY2026–27 guidance for revenue and order-inflow growth of 10–12% each, according to Reuters.
That guidance is a management expectation, not a guaranteed outcome.
What Does This Mean for Investors?
L&T shares rose more than 6% in early trading on 28 October as investors responded to the results.
The early market reaction should not be confused with a confirmed closing return.
For shareholders, attention now turns to whether the company can convert its record order book into revenue, operating profit and cash flow without further margin deterioration.
For the wider infrastructure industry, the results demonstrate continued demand for engineering capacity while highlighting the challenge of executing complex projects profitably.
What to Watch Next
The key indicators are:
- Conversion of the ₹8.54 lakh crore order book into recognised revenue
- Infrastructure segment margins and cost escalation
- Middle East project execution and logistics conditions
- New domestic infrastructure and energy orders
- Working capital, cash generation and project delivery schedules
L&T's record order pipeline provides substantial future work. The next test is how efficiently and profitably that work can be completed.
Sources
Click an article title to view the source.
- Consolidated Financial Results for the Quarter Ended September 30, 2026 issued on 27 October 2026 by Larsen & Toubro.
- L&T Net Rises 33% in Q2 on Order Inflows published on 28 October 2026 by ETInfra.
- India's L&T Jumps as Quarterly Profit Beat Eases Middle East Concerns published on 28 October 2026 by Reuters.
- L&T Q2 Results: Net Profit Rises 33% to Rs 5,202 Crore published on 27 October 2026 by Moneycontrol.
Evidence Caveats
Figures are based on the company's unaudited quarterly results and contemporary reporting. Growth percentages are rounded.
The outstanding order book is not the same as revenue, profit or cash received.
Quarterly margin comparisons relate to the named segment and should not be confused with consolidated group margins.
Share-price movement describes early trading on 28 October, not the final closing price.
FY2026–27 guidance depends on market conditions and execution performance.
Does a record order book make an infrastructure company more attractive, or should profitability matter more? Share your assessment in the Vantage community discussion.
From TatvaOps
Residential Construction
Building or extending your home?
Run your residential build with verified contractors and daily progress tracking.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this Radar article is filed under Radar.
More from Construction
Silver Trading Revives at IIBX as Import Licensing Reshapes Sourcing
India International Bullion Exchange IIBX recorded approximately 570 metric tonnes of silver trades over roughly three months since August, according to a Mint report published on 29 October 2026. The report links the activity to import licensing changes and the subsequent issuance of…
US Fed Holds Rates at 3.754 as Inflation Keeps Further Tightening in Focus
The US Federal Reserve left its benchmark interest rate target unchanged at 3.75–4% on 28 October 2026, retaining its focus on inflation while waiting for more economic information. The Federal Open Market Committee voted 10–2 for the hold. Lisa Cook and Beth Hammack preferred a quarter percentage…
Cyclone Arnab Hits Andhra Coast, Threatens Homes
Cyclone Arnab struck India's Andhra Pradesh coast on 28 October 2026, bringing dangerous winds, heavy rain and flooding risks. More than 180,000 people were evacuated across Andhra Pradesh and Odisha as authorities worked to protect vulnerable communities. Cyclone Arnab Makes Landfall The India…
Key Insight Actions
Connected knowledge for Financial Results
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
DCR Solar Module Premium Raises Rooftop Costs in India
1 replies
Related discussionNoida Adopts New Building Rules to Remove FAR Cap for Eligible Group Housing
1 replies
Related discussionL&T's 8.54 Lakh Crore Order Book: Is Bigger Better?
1 replies
Related discussionRooftop Solar: Bill Savings or Backup Power?
1 replies
Related discussion
Topic hubs
Conclusion Intelligence
Related Discussions
DCR Solar Module Premium Raises Rooftop Costs in India
Popular in radar discussions1 reply
Noida Adopts New Building Rules to Remove FAR Cap for Eligible Group Housing
Popular in radar discussions1 reply
L&T's 8.54 Lakh Crore Order Book: Is Bigger Better?
Popular in insights discussions1 reply
Rooftop Solar: Bill Savings or Backup Power?
Popular in insights discussions1 reply
Was this helpful?
Let us know what you think