

Anarock Profit Rises 53 Ahead of 1,000 Crore IPO, but Operating Cash Flow Turns Negative
Karthik posts articles on Energy and Construction.
Summary
Anarock Property Consultants reported strong FY26 earnings growth ahead of its proposed ₹1,000 crore initial public offering, but the company's cash flow statement presents a more complicated picture. Profit after tax increased 53.4% to ₹93.22 crore in FY26 from ₹60.78 crore a year earlier. Revenue from operations rose 33.8% to ₹881.90 crore , compared with ₹658.95 crore in FY25. Operating cash flow, however, moved in the opposite direction. Anarock reported an operating cash outflow of ₹12.07 crore in FY26 , compared with an inflow of approximately ₹93 crore in FY25.
Published on
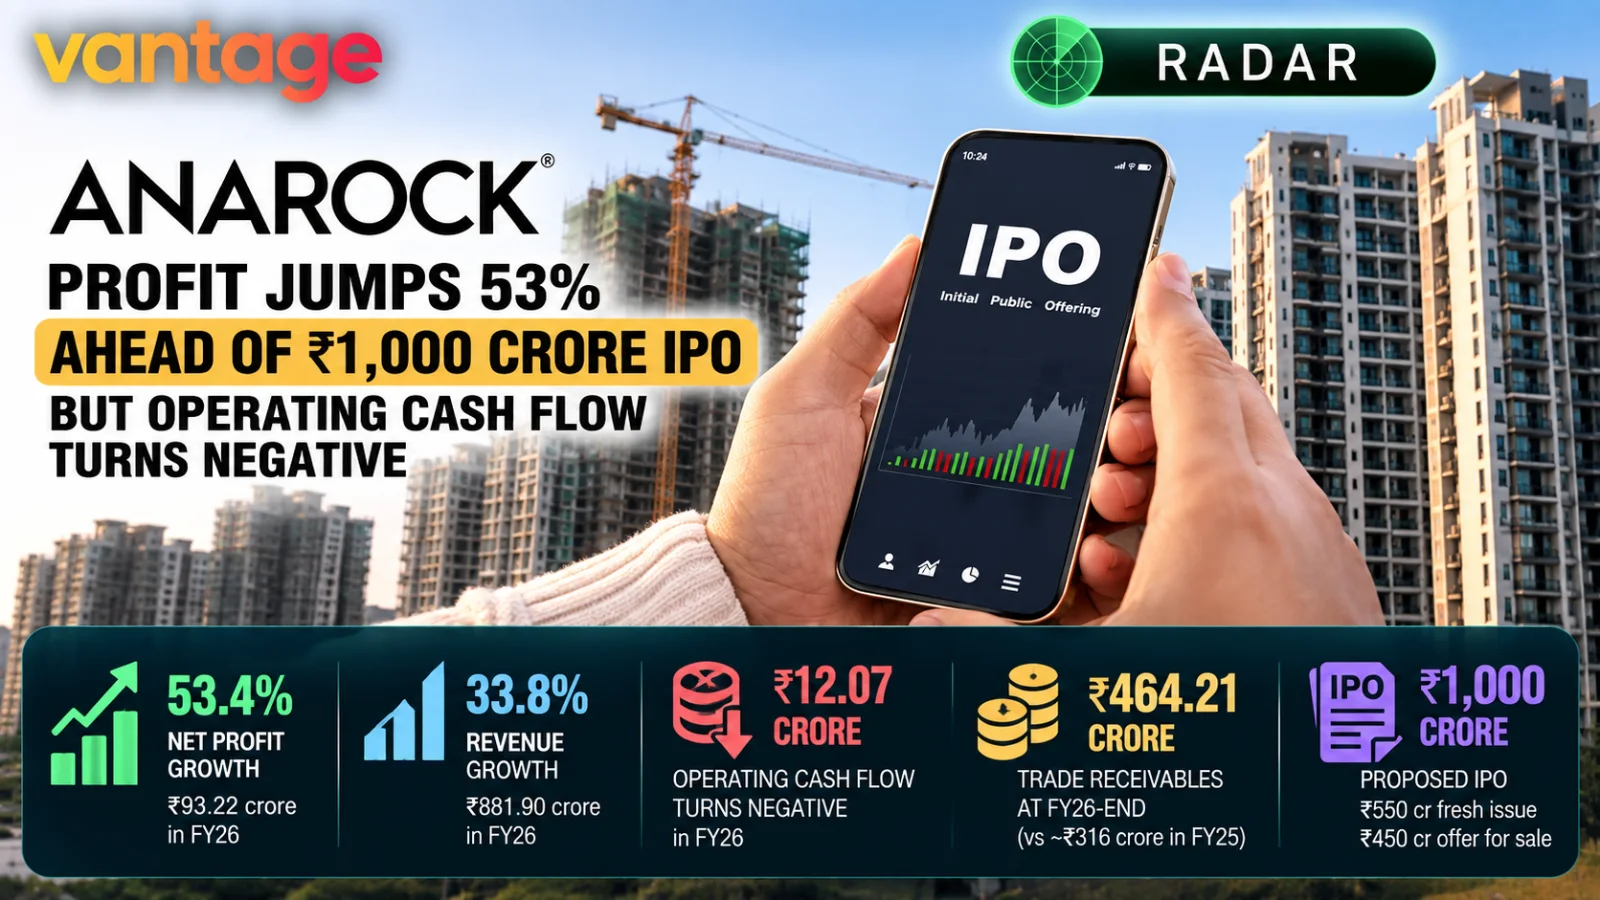
banner showing an investor reviewing Anarock IPO and financial data against an Indian residential construction backdrop. The visual contrasts Anarock's strong FY26 profit and revenue growth with negative operating cash flow and higher trade receivables, framing the key question for prospective IPO investors around earnings quality, cash conversion and deployment of fresh capital.
Inline Intelligence
Anarock Property Consultants reported strong FY26 earnings growth ahead of its proposed ₹1,000 crore initial public offering, but the company's cash-flow statement presents a more complicated picture.
Profit after tax increased 53.4% to ₹93.22 crore in FY26 from ₹60.78 crore a year earlier.
Revenue from operations rose 33.8% to ₹881.90 crore, compared with ₹658.95 crore in FY25.
Operating cash flow, however, moved in the opposite direction.
Anarock reported an operating cash outflow of ₹12.07 crore in FY26, compared with an inflow of approximately ₹93 crore in FY25.
The divergence does not mean Anarock's reported profit is invalid.
But ahead of an IPO, it makes one question particularly important for prospective investors:
How efficiently can Anarock convert its growing accounting earnings into cash?
Anarock FY26 Profit Reaches ₹93.22 Crore
Anarock's profit after tax increased from ₹60.78 crore in FY25 to ₹93.22 crore in FY26.
That represents growth of approximately 53.4%.
Revenue from operations increased from ₹658.95 crore to ₹881.90 crore over the same period.
The company has also grown substantially compared with FY24, when revenue from operations was ₹509.23 crore and net profit was ₹44.94 crore.
The earnings trajectory is therefore clearly positive.
But Operating Cash Flow Swung Negative
The important counterpoint sits in the cash-flow statement.
Operating cash flow moved from an inflow of approximately ₹93 crore in FY25 to an outflow of ₹12.07 crore in FY26.
Profit and operating cash flow measure different things.
Accounting profit includes revenue that has been recognised even when the associated customer payment has not yet been received.
Operating cash flow tracks the actual cash generated or absorbed by normal business operations.
A profitable company can therefore report negative operating cash flow in an individual year.
The key question is why.
Trade Receivables Rose to ₹464.21 Crore
Anarock's trade receivables increased to ₹464.21 crore at the end of FY26, from approximately ₹316 crore a year earlier.
That is an increase of roughly ₹148.21 crore.
This is a Vantage-derived calculation.
Trade receivables represent amounts customers owe for services for which revenue has already been recognised.
Anarock attributed the increase partly to revenue growth and the timing of revenue recognition and billing.
Revenue recognised late in the financial year naturally provides less time for the corresponding cash to arrive before the 31 March reporting date.
Higher receivables therefore do not automatically establish a collection problem.
But the size of the increase makes cash conversion an important metric to monitor.
Receivables Were Equivalent to More Than Half of FY26 Revenue
Comparing year-end trade receivables with annual revenue provides another scale indicator.
₹464.21 crore divided by ₹881.90 crore equals approximately 52.6%.
This is a Vantage-derived ratio.
It should not be interpreted as a collection delay percentage.
Revenue is measured across an entire year, while receivables are a point-in-time balance-sheet figure.
The ratio simply demonstrates that outstanding customer balances were substantial relative to Anarock's annual revenue base at year-end.
Profit Growth and Cash Generation Can Diverge
The difference between accounting earnings and cash generation is common in businesses where clients pay after services are delivered or revenue is recognised.
The important question for investors is whether the divergence is temporary.
If receivables are subsequently collected, operating cash flow can improve.
If receivables continue rising faster than revenue for an extended period, more capital becomes tied up in working capital.
The FY26 numbers alone cannot determine which pattern will emerge.
Anarock Plans a ₹1,000 Crore IPO
Anarock has filed its Draft Red Herring Prospectus for a proposed ₹1,000 crore IPO.
The offer comprises:
- up to ₹550 crore of fresh shares; and
- up to ₹450 crore through an offer for sale.
The distinction is important.
Fresh-issue proceeds go to the company, subject to issue expenses and the stated use of proceeds.
Offer-for-sale proceeds go to selling shareholders.
Therefore, the full ₹1,000 crore should not be described as capital being raised for Anarock's business.
Only ₹550 Crore Is the Proposed Fresh Issue
The fresh issue represents 55% of the proposed ₹1,000 crore offer.
The ₹450 crore OFS represents 45%.
These percentages are direct calculations from the disclosed issue structure.
Anarock may also undertake a pre-IPO placement of up to ₹110 crore.
If that occurs, the fresh issue will be reduced by the amount raised through the placement.
Where Does Anarock Plan to Use the Fresh Capital?
The company proposes to allocate fresh-issue proceeds across technology, talent, acquisitions and other corporate requirements.
Disclosed uses include:
- ₹120 crore for artificial intelligence augmentation and technology across certain businesses;
- ₹89.5 crore to strengthen existing businesses and add specialised services through talent augmentation;
- ₹148 crore towards acquiring additional equity in DSP Design Associates; and
- remaining proceeds towards acquisitions, strategic initiatives and general corporate purposes.
These are proposed uses rather than completed investments.
The DSP Design Acquisition Adds Another Layer
Anarock acquired 53.68% of DSP Design Associates for ₹64.01 crore on 27 September 2026, shortly before filing its IPO papers.
DSP provides architecture, interior design, office fit-outs, design-and-build and project-management services.
The acquisition broadens Anarock's exposure beyond transaction advisory.
But DSP's FY26 numbers also require attention.
DSP reported revenue of ₹241.97 crore and net profit of ₹6.86 crore.
Its operating cash flow was negative ₹1.61 crore, compared with positive ₹11.95 crore in FY25.
Because the acquisition happened after FY26, DSP is not included in Anarock's reported FY26 results.
DSP Adds More Revenue Than Profit
Anarock's DRHP provides pro forma numbers showing what the combined FY26 financials would have looked like if DSP had been part of the group throughout the year.
Pro forma revenue would have been approximately ₹1,123.87 crore, around 27% above Anarock's reported ₹881.90 crore.
Pro forma net profit would have been approximately ₹100.07 crore, only around 7% above Anarock's reported ₹93.22 crore.
The combined net profit margin would have been approximately 8.9%, compared with Anarock's reported margin of approximately 10.6%.
This suggests DSP adds meaningful scale but currently has a lower profit margin than Anarock's existing business.
Anarock's Business Is Becoming More Diversified
Anarock began primarily as a residential property advisory platform.
It now operates across several parts of the real estate services value chain.
In FY26, transaction advisory generated approximately ₹442.45 crore of revenue.
Leasing and investment advisory contributed approximately ₹306.83 crore.
Management services generated approximately ₹89.17 crore.
The company also operates technology-based real estate services.
Diversification can create multiple revenue streams.
It can also introduce businesses with different margins, working-capital requirements and cash-conversion cycles.
Anarock Had No Outstanding Borrowings at FY26-End
One important counterweight to the cash-flow concern is the balance sheet.
Business Standard reported that Anarock had no outstanding borrowings as of 31 March 2026.
That matters.
Negative operating cash flow has a different risk profile in a highly leveraged company than in a company without outstanding borrowings.
The FY26 issue is therefore better framed as a cash-conversion and working-capital question, rather than automatically as a debt-stress story.
Why Cash Conversion Matters Before an IPO
Public-market investors ultimately buy a claim on future economic cash flows.
Accounting profit is essential, but investors also examine whether reported earnings translate into cash.
Strong profit growth combined with persistently weak operating cash flow can raise questions around:
- working-capital intensity;
- customer payment cycles;
- revenue recognition;
- collection efficiency; and
- the capital required to support growth.
One negative year does not establish a structural problem.
The trend after FY26 will be more informative.
What Should IPO Investors Watch?
Several indicators deserve attention.
Trade receivables
Do receivables continue growing faster than revenue?
Operating cash flow
Does cash generation return to positive territory?
Receivable collection
Are FY26 customer balances converted into cash during FY27?
DSP integration
Does the acquisition improve its relatively low profitability?
Margins
Does diversification dilute or strengthen group margins?
IPO valuation
The eventual price band will determine what investors are being asked to pay for the earnings and growth profile.
No IPO valuation can yet be assessed from the current evidence.
The ₹1,000 Crore Headline Needs Context
The IPO size may attract attention.
But investors should separate the components.
₹550 crore is the proposed fresh issue.
₹450 crore is the proposed OFS.
And the fresh issue itself could be reduced if the company completes a pre-IPO placement.
That makes the eventual capital flowing into Anarock different from the headline ₹1,000 crore issue size.
Strong Earnings, Weaker Cash Conversion
Anarock enters the IPO process with several strengths visible in the disclosed financials:
revenue is growing,
profit is growing faster than revenue,
the company has expanded its service portfolio,
and it had no outstanding borrowings at FY26-end.
But the DRHP also gives investors something important to investigate.
Operating cash flow deteriorated sharply while trade receivables increased.
Neither fact cancels the earnings growth.
Together, they define the central IPO question:
Can Anarock continue growing while converting a larger share of reported earnings into operating cash?
The next set of financial disclosures may provide a more important answer than the 53% profit-growth headline.
Frequently Asked Questions
How much profit did Anarock make in FY26?
Anarock reported profit after tax of ₹93.22 crore in FY26, up approximately 53.4% from ₹60.78 crore in FY25.
What was Anarock's FY26 revenue?
Revenue from operations was ₹881.90 crore, up approximately 33.8% year on year.
Why was Anarock's operating cash flow negative?
Operating cash flow was negative ₹12.07 crore as trade receivables increased substantially. Anarock attributed the receivables increase partly to revenue growth and the timing of revenue recognition and billing.
How much were Anarock's trade receivables?
Trade receivables stood at ₹464.21 crore at the end of FY26, compared with approximately ₹316 crore a year earlier.
How large is the Anarock IPO?
The proposed IPO is ₹1,000 crore, comprising up to ₹550 crore of fresh issuance and ₹450 crore of offer-for-sale shares.
Does the entire ₹1,000 crore IPO go to Anarock?
No. The ₹450 crore OFS proceeds go to selling shareholders. Only the fresh-issue proceeds go to the company, subject to issue expenses and any pre-IPO placement adjustment.
Does Anarock have debt?
Business Standard reported that Anarock had no outstanding borrowings as of 31 March 2026.
Is negative operating cash flow a warning sign for the Anarock IPO?
It is a metric investors should examine, particularly alongside rising receivables. One year of negative operating cash flow does not by itself establish a structural collection problem.
Sources
Click on article title to view article.
“IPO-bound Anarock’s FY26 operating cash flow turns negative despite 53% rise in profit” published on 5 October 2026 in Moneycontrol
“Anarock Property Consultants files DRHP to raise ₹1,000 cr via IPO” published on 1 October 2026 in Business Standard
Evidence Caveats
- Negative FY26 operating cash flow does not by itself establish a structural collection problem.
- Anarock attributed higher receivables partly to revenue growth and the timing of billing and revenue recognition.
- Approximately ₹148.21 crore receivables growth and the 52.6% receivables-to-revenue comparison are Vantage-derived indicators.
- The 52.6% ratio is not a collection-delay percentage.
- ₹1,000 crore is the total proposed IPO size, not the amount of fresh capital flowing to Anarock.
- DSP pro forma financials illustrate a hypothetical full-year combination and are not Anarock's reported FY26 results.
- IPO valuation, price band, post-issue market capitalisation, FY27 cash conversion and future receivable collection remain unavailable.

From TatvaOps
Home Maintenance & Appliance Care
Comparing contractor quotes?
Line up pricing, scope, and timelines before you sign.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this Radar article is filed under Radar.
More from Real Estate
LTCG and STT: Review Reports Do Not Mean a Tax Cut
Finance Minister Nirmala Sitharaman’s comments on equity taxation have reopened a consequential debate for investors. Speaking at the Bloomberg New Economy Forum in New Delhi on 13 October, she welcomed views on long term capital gains tax and securities transaction tax without committing to…
Blackstone Targets 100 Billion in India Investments
Blackstone aims to double its India investments to approximately $100 billion over about five years, president and chief operating officer Jonathan Gray said in interviews reported this week. The ambition spans private equity and real estate, alongside potential expansion in infrastructure, credit…
Property Registrations Flagged Over Fictitious PAN
Nearly 25,000 property registrations over two years at Badshahpur tehsil in Gurugram reportedly carried the same fictitious PAN, according to The Times of India’s 9 October report on an Income Tax Department survey. The finding raises questions about taxpayer identification and transaction…
Inline Intelligence
Key Insight Actions
Connected knowledge for Financial Updates
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Anarock Profit Rose 53, but Cash Flow Turned Negative: What Should IPO Investors Trust More?
1 replies
Related discussionGST ITC Relief: Can Property Investors Count on Savings?
1 replies
Related discussionIndias Data-Centre Boom Is Turning Power and Land Into Digital Infrastructure
1 replies
Related discussion
Topic hubs
Conclusion Intelligence
Related Discussions
Anarock Profit Rose 53, but Cash Flow Turned Negative: What Should IPO Investors Trust More?
Popular in insights discussions1 reply
GST ITC Relief: Can Property Investors Count on Savings?
Popular in insights discussions1 reply
Indias Data-Centre Boom Is Turning Power and Land Into Digital Infrastructure
Popular in insights discussions1 reply
Was this helpful?
Let us know what you think