

GST ITC Relief Could Change Commercial Real Estate Economics, but How Much Would Developers Actually Save?
Karthik posts articles on Energy and Construction.
Summary
The GST Council may consider input tax credit reforms affecting real estate and construction on 8 October 2026. If more construction GST becomes creditable, qualifying commercial projects could require less capital and generate better development economics. But the scope remains unknown, and there i The GST Council is preparing to consider input tax credit reforms that could affect real estate, construction and infrastructure. For developers and property investors, the proposal sounds technical. Economically, it is not.
Published on
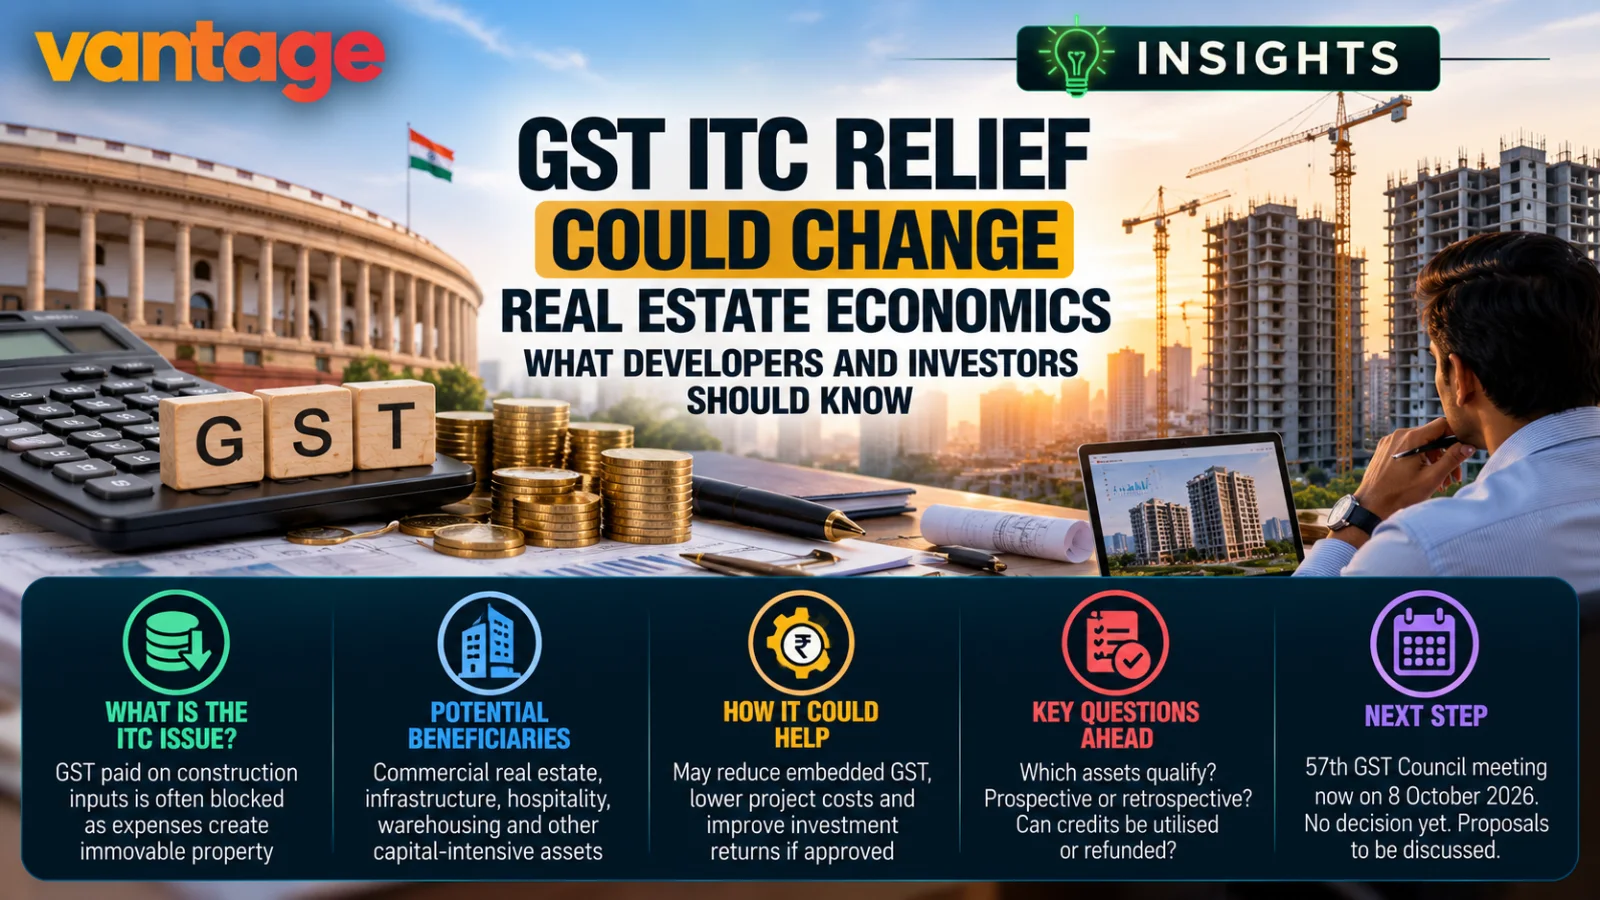
InSights editorial banner illustrating the potential impact of GST input tax credit reform on Indian real estate economics. The visual combines Parliament, residential construction, cranes, GST-related financial imagery and a property professional assessing a development, highlighting possible implications for embedded GST costs, project capital requirements and investment returns. The banner also emphasises that the proposals remain under consideration ahead of the 57th GST Council meeting on 8
Inline Intelligence
The GST Council is preparing to consider input tax credit reforms that could affect real estate, construction and infrastructure.
For developers and property investors, the proposal sounds technical.
Economically, it is not.
When GST paid during construction cannot be claimed as input tax credit, that tax can become embedded in the cost of creating an asset.
Allowing more credit could therefore reduce the effective capital required for qualifying projects.
But there is a major limitation.
We do not yet know how much real estate expenditure, if any, will become newly creditable.
The GST Council has not approved the proposals.
That means developers should understand the potential mechanism without building unconfirmed tax savings into project valuations.
Blocked ITC Behaves Like a Project Cost
Consider two otherwise identical commercial projects.
Both spend money on taxable construction inputs.
Project A can claim the GST as credit.
Project B cannot.
Project B effectively carries a higher embedded tax cost.
That can influence the developer's required return, financing requirement and eventual economics.
This is why input tax credit matters even when the headline GST rate itself does not change.
A Simple Example Shows the Potential Effect
Assume, purely for illustration, that a qualifying business incurs:
₹100 crore of taxable construction expenditure,
with ₹18 crore of GST.
Scenario 1: ITC blocked
Effective outlay = ₹118 crore.
Scenario 2: ITC fully available and usable
Economic cost before financing and other considerations = ₹100 crore.
The difference is ₹18 crore.
That represents approximately 15.3% of the ₹118 crore tax-inclusive outlay.
This is a Vantage-derived illustration.
It is not an estimate of savings available under the proposal.
Real projects contain expenditure taxed at different rates, exempt items, land, financing costs and credits with different eligibility.
Why the Return Effect Can Be Larger Than It Looks
Suppose the project's annual net operating income remains unchanged while development cost falls.
The development yield improves.
For example, a hypothetical property generating ₹10 crore of annual NOI on ₹118 crore of cost produces a development yield of approximately 8.47%.
The same ₹10 crore on ₹100 crore of cost produces 10%.
Again, these are illustrative calculations only.
They demonstrate why embedded taxes matter to capital-intensive property investment.
They do not forecast returns from any real project.
Commercial Leasing Creates the Central Policy Tension
Commercial property presents an unusual GST issue.
Rental income from commercial property can be taxable.
Yet construction-related ITC can be blocked when the owner builds and retains the underlying immovable property.
From the business perspective, this can create tax embedded in an asset that is subsequently used to make taxable supplies.
From the government's perspective, completed immovable property occupies a special position in the GST framework, and the law deliberately restricts construction credits in specified circumstances.
The policy challenge is deciding where the credit chain should end.
Safari Retreats Exposed the Problem
The Supreme Court's 2024 Safari Retreats judgment became important because it examined whether a commercial property could qualify as "plant" depending on its functionality.
The judgment opened the possibility of ITC in certain circumstances.
The GST Council subsequently recommended changing Section 17(5)(d).
The Finance Act 2025 retrospectively substituted "plant and machinery" for "plant or machinery", effective from 1 July 2017.
That substantially narrowed the route created by the judgment.
The latest reform discussion therefore takes place against a history of government caution around construction ITC.
That Makes the Current Proposal More Interesting
If the Council now relaxes specific blocked credits, it would not necessarily reverse the 2025 amendment.
Instead, policymakers could create targeted relief for defined business assets or expenditure.
That distinction matters.
A narrow reform involving pipelines or specified infrastructure would have a very different economic effect from broad eligibility for commercial buildings.
Investors should wait for the actual wording.
Which Assets Could Gain Most?
Theoretically, the greatest benefit would accrue to projects with:
- high taxable construction expenditure;
- significant currently blocked ITC;
- long holding periods;
- taxable operating income; and
- sufficient output GST liability or refund mechanisms to utilise credits.
But these are analytical characteristics.
They do not establish which sectors will actually qualify.
Office Real Estate
Office assets could be important if the reform reaches buildings retained for taxable leasing.
Reducing embedded tax could improve development economics and potentially make redevelopment or new construction more attractive.
But current reporting does not confirm blanket office-building ITC.
Therefore, no office yield improvement should yet be modelled.
Retail Malls
Shopping centres combine property construction with substantial fit-out, equipment and operating infrastructure.
The Safari Retreats dispute itself originated in mall construction and leasing.
That makes retail property especially relevant to the broader policy debate.
But the 2025 amendment materially restricted the earlier judicial opening.
Any new benefit depends entirely on what the Council now recommends.
Warehousing and Logistics
Warehousing can sit close to the boundary between conventional building construction and specialised operating infrastructure.
Automated systems, equipment, storage infrastructure and logistics installations can have different tax treatment.
Clearer rules could therefore be as valuable as broader credit eligibility.
Tax certainty itself can reduce underwriting risk.
Hotels
Hotels are both real estate assets and operating businesses.
A hotel building supports taxable hospitality activity but requires substantial upfront construction and fit-out.
Wider ITC could potentially improve project economics.
Business Standard reports that hospitality-related credit reforms are also under consideration.
However, these proposals should not be assumed to match the real estate measures exactly.
Would Developers Pass the Saving to Tenants?
Not necessarily.
Lower development cost could produce several outcomes:
- lower required rents;
- higher developer margins;
- greater land bids;
- higher investment returns;
- more new supply; or
- some combination.
Competitive markets influence where the benefit ultimately goes.
There is no evidence supporting a uniform pass-through percentage.
Could Landowners Capture the Benefit Instead?
Possibly.
Real estate economics often capitalise cost or revenue advantages into land values.
If development becomes more profitable, developers may eventually bid more aggressively for suitable sites.
Part of the tax benefit could therefore migrate to landowners rather than remaining permanently with developers or tenants.
This is an economic possibility, not an observed outcome of the current proposal.
The Financing Effect Also Matters
Blocked GST requires cash.
That cash may need to be funded with equity or debt.
If more GST becomes creditable, a developer could require less permanent capital for a qualifying project.
The benefit can therefore extend beyond the tax amount itself because financing costs may also fall.
But the size depends on:
- credit timing;
- utilisation;
- project leverage;
- interest rates; and
- construction duration.
No reliable sector-wide estimate is currently available.
Retrospective Relief Would Be Much More Powerful
One of the most consequential details will be the effective date.
Prospective relief affects new expenditure.
Retrospective relief could potentially affect existing projects or previously blocked credits.
The fiscal consequences would be much larger.
Current accessible reporting does not establish that broad retrospective relief for real estate will be granted.
Developers should not assume it.
Refundability Is Another Key Question
A tax credit has economic value only if a business can use or recover it.
If credits accumulate without sufficient output liability, working capital can remain trapped.
The Council is separately considering reforms to refunds of accumulated ITC, including input services and capital goods in certain inverted-duty situations.
The interaction between eligibility and refundability can therefore be as important as the headline credit rule.
The Biggest Immediate Benefit May Be Certainty
Construction ITC has produced litigation, statutory amendments and uncertainty.
For institutional real estate investors, uncertainty has a cost.
Projects are often underwritten over ten or more years.
A tax assumption that changes after construction can materially alter returns.
Clearer rules could therefore improve investment decision-making even if the eventual relief is narrower than industry hopes.
What Should a Developer Do Before 8 October?
Do not reprice the project.
Instead, map exposure.
A developer can identify:
- GST currently capitalised into construction cost;
- credits blocked under Section 17(5);
- asset categories potentially affected by reform;
- projects under construction;
- completed assets with unresolved credit positions; and
- litigation or disputed claims.
Once the Council decision and legal text arrive, that map can be used to quantify the actual impact.
What Should REIT Investors Watch?
For listed office and retail portfolios, potential changes could matter through development and redevelopment economics.
But existing completed assets will not necessarily receive any benefit.
REIT investors should therefore watch:
- treatment of redevelopment expenditure;
- prospective development pipelines;
- fit-out credits;
- retrospective applicability;
- tax disputes; and
- management guidance after final rules are issued.
Until then, changing NAV or distribution forecasts based on the proposal would be premature.
What Would Make the Reform Material?
The reform becomes economically significant for real estate if several conditions align:
a broad set of business-use assets becomes eligible,
meaningful construction expenditure qualifies,
credits can actually be utilised or refunded,
and
implementation is clear enough to avoid another litigation cycle.
If the reform covers only narrow infrastructure categories, the impact on conventional property development could be limited.
The Decision Is About Capital Efficiency
GST reform is often discussed as tax compliance.
For property investors, this issue is really about capital efficiency.
Blocked ITC converts recoverable tax into permanent project cost.
Recoverable ITC converts part of that cost back into working capital.
That can change the amount of equity required to build an asset and the return generated on that equity.
But until the GST Council makes its decision, the size of that opportunity remains unknown.
The correct investment stance is therefore not to assume a windfall.
It is to identify which projects have the greatest exposure to blocked GST and be ready to recalculate their economics once the final rules are known.
Frequently Asked Questions
How does input tax credit affect commercial real estate returns?
When construction GST is blocked, it can become part of project cost. If credit becomes available and can be utilised, effective development cost can fall, potentially improving project returns.
How much could developers save from GST ITC reform?
No reliable percentage can currently be calculated because the GST Council has not approved the proposals or defined the eligible expenditure.
Will office developers get full construction ITC?
There is no evidence yet supporting blanket eligibility for office construction.
Could GST ITC relief increase REIT returns?
Potentially through development or redevelopment economics, but the actual effect depends on final rules, asset eligibility and whether credits can be utilised. No REIT return uplift can currently be quantified.
Will GST ITC relief reduce office rents?
Not necessarily. Benefits could be captured through margins, land values, investment returns, rents or additional supply. Market competition determines pass-through.
Why was the Safari Retreats case important?
It opened a potential route for certain commercial properties to qualify for ITC through a functionality test. A retrospective 2025 statutory amendment subsequently narrowed that route.
Could previously blocked GST be recovered?
That depends on whether any final reform has retrospective effect or transitional provisions. Current evidence does not establish broad retrospective recovery.
What is the most important detail to watch on 8 October?
The exact definition of eligible assets and expenditure. Without that, the economic value of the proposed ITC reform cannot be quantified.
Sources
Click on article title to view article.
“GST Council may consider ITC rationalisation for real estate, construction” published on 5 October 2026 in Business Standard
“GST Council may set different timelines for services, capital goods refunds” published on 5 October 2026 in Business Standard
“GST 2.0: Council to consider sweeping reforms to unlock tax credit, ease compliance” published on 5 October 2026 in The Economic Times
“Govt reschedules GST Council meet to 8 October citing ‘unavoidable circumstances’” published on 5 October 2026 in Moneycontrol
Primary Document
“55th Meeting of the GST Council” published by the Goods and Services Tax Council
Evidence Caveats
- No final real estate ITC reform has been approved.
- All project-return examples are Vantage editorial illustrations, not forecasts.
- The 15.3%, 8.47% and 10% figures come only from the hypothetical example and must not be applied to actual projects.
- The final treatment of offices, malls, warehouses, hotels, industrial property and other assets remains unknown.
- No reliable evidence supports a uniform rent, property-price, development-cost, IRR or REIT-distribution impact.
- Prospective versus retrospective treatment remains a critical unknown.

From TatvaOps
Residential Construction
Financing your project?
Explore credit and milestone-secured payment options with Tatva Finance.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
1 reply already on Forums
More from Real Estate
LTCG Tax Debate: Should You Delay Selling Investments?
Could waiting for LTCG tax relief cost more than it saves? With proposals under discussion, we examine how your current tax liability, market exposure and cash deadline should shape a planned investment sale.
Blackstones India Bet: What Should You Check?
Blackstone’s $100-billion India ambition is a useful signal. For your own money, the harder questions are access, valuation, cash flow and risk. Here is what to check before turning institutional optimism into a personal investment decision.
Senior Living: Buy the Home, Examine the Services: what most readers overlook
Rustomjee’s senior-living evaluation raises a household question: can you afford and rely on the services after buying the home? We examine recurring charges, operator responsibilities, changing support needs and exit flexibility.
Inline Intelligence
Key Insight Actions
Connected knowledge for Tax & Finance
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Topic hubs
Conclusion Intelligence
Related Discussions
Chennai Office Lease: What Reaches the REIT Investor?
Popular in insights discussions1 reply
GST ITC Relief: Can Property Investors Count on Savings?
Popular in insights discussions1 reply
Why TVS Motors 5.3 Lakh Sq Ft Bengaluru Lease Matters Beyond the Headline Rent
Popular in insights discussions1 reply
Was this helpful?
Let us know what you think