

Record SIPs: Can More Units Still Mean Less Money?
Karthik posts articles on Energy and Construction.
Summary
September SIP contributions reached a record, yet SIP assets declined. We explain why buying more units does not guarantee a profit, how gross contributions differ from net flows, and which personal checks matter during a market fall. Investors kept contributing through SIPs in September. Yet the value of assets associated with those investments fell. AMFI’s tables show SIP assets declining from approximately ₹18.62 lakh crore in August to ₹17.86 lakh crore in September, a decrease of about 4.06%. This occurred alongside record monthly contributions. There is no contradiction. Contributions measure money invested.
Published on
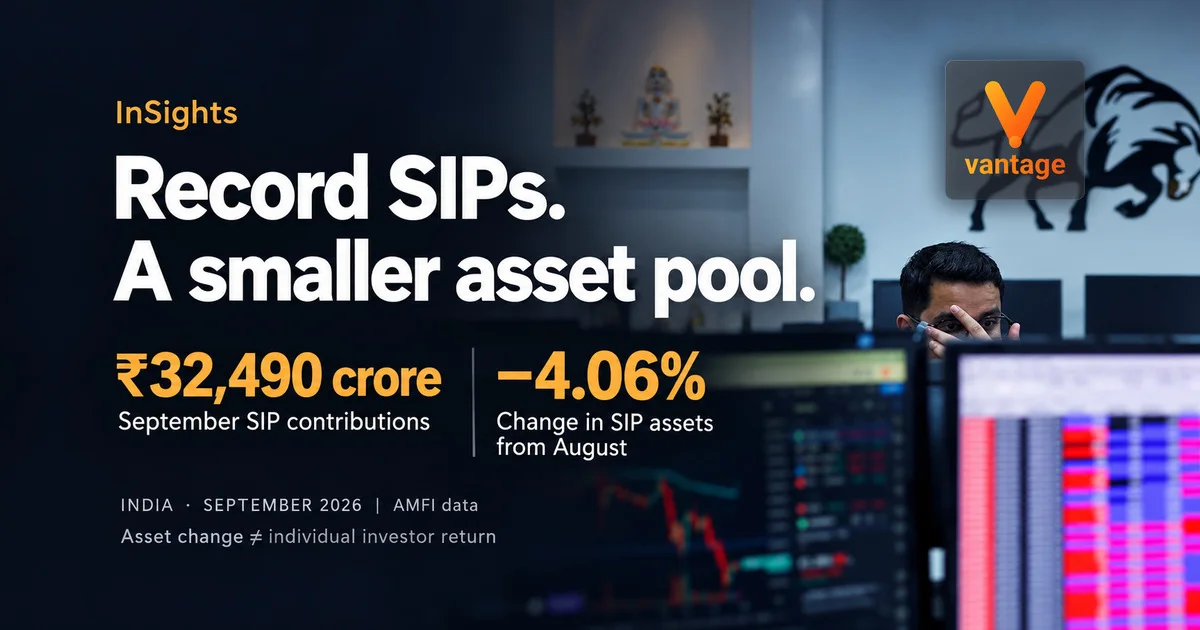
InSights banner showing ₹32,490 crore in September 2026 SIP contributions and a 4.06% decline in SIP assets from August, with trading monitors and the Vantage logo.
Inline Intelligence
Investors kept contributing through SIPs in September. Yet the value of assets associated with those investments fell.
AMFI’s tables show SIP assets declining from approximately ₹18.62 lakh crore in August to ₹17.86 lakh crore in September, a decrease of about 4.06%. This occurred alongside record monthly contributions.
There is no contradiction. Contributions measure money invested. Portfolio value also reflects market movements and withdrawals.
For an individual investor, the useful question is therefore not simply whether the SIP continued: does the investment still fit the purpose and timing of the money?
A SIP is a method, not a separate asset class
SEBI’s investor-education booklet describes a systematic investment plan as a facility for investing fixed amounts in a scheme at regular intervals.
The scheme determines what the money is exposed to. An equity fund, a debt fund and a hybrid fund can have different risks even when contributions follow the same schedule.
Automation helps implement a decision. It cannot establish that the original fund choice or allocation remains suitable.
That distinction matters during a market decline. Continuing an appropriate long-term investment and continuing an unsuitable allocation are different decisions.
How can buying more units still leave you with a loss?
Consider three hypothetical monthly investments of ₹10,000 at progressively lower net asset values.
| Instalment | Amount invested | Assumed NAV | Units purchased |
|---|---|---|---|
| First | ₹10,000 | ₹100 | 100.000 |
| Second | ₹10,000 | ₹80 | 125.000 |
| Third | ₹10,000 | ₹60 | 166.667 |
| Total | ₹30,000 | — | 391.667 |
The same contribution buys more units as the NAV falls.
Using unrounded units, the average acquisition cost is approximately ₹76.60 per unit. But immediately after the third investment, at the assumed ₹60 NAV, the portfolio is worth ₹23,500.
That is ₹6,500 below the ₹30,000 contributed.
The acquisition process has spread purchases across different prices. It has not prevented a loss at the valuation date.
These are Vantage calculations using an invented NAV path, not an actual fund’s performance. The illustration ignores transaction charges and taxes. The difference between contributions and ending value is not an annualised return calculation.
What would need to happen for the example to recover?
Under those simplified assumptions, the NAV would need to rise to approximately the average acquisition cost for the portfolio value to equal the amount contributed.
Whether that happens, and how long it takes, cannot be established from the purchase schedule.
Further contributions would change both the number of units and the average cost. Withdrawals would change the portfolio again.
The benefit of spreading purchases is therefore different from a guarantee that the investment will become profitable by a particular date.
AMFI’s Mutual Funds Sahi Hai calculator explicitly cautions that illustrated outcomes are not actual returns and that mutual funds do not offer a predictable fixed rate of return.
Why should the two headline flow numbers remain separate?
September’s SIP contributions and equity-scheme net inflows cannot be interpreted as two independent pools of fresh money.
| Measure | What it describes | What it cannot establish |
|---|---|---|
| SIP contributions | Money collected through recurring investments | Net additions after all redemptions or investor returns |
| Equity-scheme net flows | Subscriptions less redemptions within the stated scheme grouping | Money invested exclusively through SIPs |
| Assets under management | The value of assets at a specified date | Investment performance separated from cash flows |
| Account or folio counts | Recorded investment accounts | An equivalent number of unique individuals |
A recurring contribution to an equity scheme can be reflected in both the SIP collection figure and the equity scheme’s subscriptions.
Similarly, rising assets can partly reflect new contributions rather than investment gains. Falling assets can reflect market losses, net withdrawals or both.
For the SIP asset decline, the available tables do not provide a complete decomposition assigning the movement to each cause.
Does persistent investing put a floor under the market?
Regular contributions provide money for funds to deploy. They do not establish a minimum market price.
Fund managers operate within scheme mandates, and money collected need not become an identical amount of immediate stock buying. Market prices also reflect earnings expectations, valuations, other investors’ transactions and changing conditions.
Aggregate flows cannot establish that the market has reached its lowest point or that a particular fund is attractively valued.
We previously examined why contrasting buying and selling figures do not produce a single investment verdict in this article -> FPI Flows: New Issues Draw Buying as Listed Shares Lose.
The relevant connection is how to interpret flows. The investor groups, transaction routes and reporting periods differ.
Should you continue, increase or review your SIP?
Begin with the purpose of the allocation.
Money intended for a distant goal can have a different capacity to withstand market fluctuations from money required for an imminent payment. An emergency reserve also has a different job from a long-term growth allocation.
Next, examine the underlying fund. Review its mandate, current Riskometer, portfolio exposure, costs and its role alongside your other investments.
Several funds can hold overlapping securities. Multiple SIP instructions do not necessarily provide meaningful diversification.
Finally, examine affordability. A contribution that was comfortable when established may become difficult after income or essential expenses change. Maintaining it through expensive borrowing can create a separate financial problem.
A review should identify what changed. A fall in the market alone does not settle the decision, but neither does the instruction to “stay disciplined” override a changed goal or unsuitable risk exposure.
What if the money is for a home purchase?
A down payment has a spending date and a required amount. Those constraints deserve attention before pursuing a higher expected return.
If a market loss shortly before purchase would prevent the transaction, the allocation needs to be assessed against that possibility. A plan that requires both favourable returns and perfect withdrawal timing carries a different risk from one with adequate flexibility.
The same reasoning applies to education payments, construction milestones and other commitments that cannot easily be postponed.
The practical question is how much uncertainty the goal can absorb, rather than which asset is receiving the most money nationally.
Discipline includes reviewing the plan
The September data shows that contributions can remain resilient while asset values decline. That is compatible with long-term investing, but it is not evidence that every continuing investor has chosen an appropriate fund.
A durable process combines regular investing with periodic checks on risk, allocation, affordability and the date when money is needed.
Buying more units is part of the process. Achieving the financial goal is the outcome that matters.
FAQ
1. Does a SIP guarantee a profit?
No. Outcomes depend on the underlying investments, purchase prices, costs and valuation when the money is needed.
2. Why do lower NAVs buy more units?
Units purchased equal the amount invested divided by the applicable NAV. A lower NAV increases the number purchased for the same contribution.
3. Does a lower average cost mean the portfolio is profitable?
No. The current value per unit can remain below the average acquisition cost.
4. Can SIP contributions and equity net inflows be added?
No. They measure different things and can overlap.
5. Does the decline in SIP assets measure every investor’s loss?
No. Aggregate assets are affected by market movements and cash flows. Individual portfolios and investment dates differ.
6. Are the example’s NAVs actual fund data?
No. They are assumptions used to demonstrate how unit accumulation and portfolio value can diverge.
7. Should a market fall automatically trigger a larger SIP?
No. Assess allocation, affordability, risk and goal timing before increasing exposure.
8. What should I check before changing a SIP?
The fund’s mandate and risk, portfolio overlap, costs, available monthly surplus and the date when the money is required. Distinguish changing future contributions from redeeming existing holdings.
Sources
Click an article title to view the source.
- SIP contribution and account tables published by AMFI, including September 2026 data; accessed on 13 October 2026. No publication date is displayed.
- Booklet on Securities Market: Understanding from Investor’s Perspective hosted by SEBI Investor Education, accessed on 13 October 2026. An exact publication date was not established.
- SIP Calculator in AMFI’s Mutual Funds Sahi Hai, accessed on 13 October 2026. No publication date is displayed.
- FPI Flows: New Issues Draw Buying as Listed Shares Lose published on 11 October 2026 in Vantage Radar.
Evidence Caveats
The SIP asset movement is an aggregate change, not a return calculation for an individual investor. Its division between market movements and withdrawals was not independently established.
AMFI’s SIP page retains an August heading, but its detailed tables include September entries. This article uses the dated table rows.
The NAV example is hypothetical and uses unrounded units for calculations. It is not a forecast, historical backtest or comparison demonstrating that SIP investing will outperform lump-sum investing.
This article does not recommend a specific scheme or establish current tax treatment for an individual investor.
What change would justify reviewing your SIP even if your long-term goal remains intact? Explain your reasoning in the attached forum discussion. Experiences involving affordability, risk or goal timing are especially welcome.
Disclaimer
This article provides general information and educational analysis, not personalised investment or tax advice. Mutual-fund investments carry risks. Review current scheme documents and seek qualified advice where appropriate.

From TatvaOps
Property Development
Developing a property?
Structured oversight for multi-unit and investor-led builds.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
1 reply already on Forums
More from Real Estate
LTCG Tax Debate: Should You Delay Selling Investments?
Could waiting for LTCG tax relief cost more than it saves? With proposals under discussion, we examine how your current tax liability, market exposure and cash deadline should shape a planned investment sale.
Blackstones India Bet: What Should You Check?
Blackstone’s $100-billion India ambition is a useful signal. For your own money, the harder questions are access, valuation, cash flow and risk. Here is what to check before turning institutional optimism into a personal investment decision.
Senior Living: Buy the Home, Examine the Services: what most readers overlook
Rustomjee’s senior-living evaluation raises a household question: can you afford and rely on the services after buying the home? We examine recurring charges, operator responsibilities, changing support needs and exit flexibility.
Inline Intelligence
Key Insight Actions
Connected knowledge for Investing
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Topic hubs
Conclusion Intelligence
Related Discussions
Was this helpful?
Let us know what you think