

Inflation at 5.54: Is a 7 Return Really Enough?
Karthik posts articles on Energy and Construction.
Summary
India’s September inflation reached 5.54%. A 7% return can still lose purchasing power after tax under an illustrative scenario. We examine personal inflation, savings choices and the pressure on home buying budgets. A savings balance can grow while its purchasing power shrinks. That possibility deserves attention after India’s September retail inflation reached 5.54%. A hypothetical investment earning 7% appears comfortably ahead of that figure. Yet, under an illustrative 30% tax deduction from interest, its net nominal return becomes 4.90%.
Published on
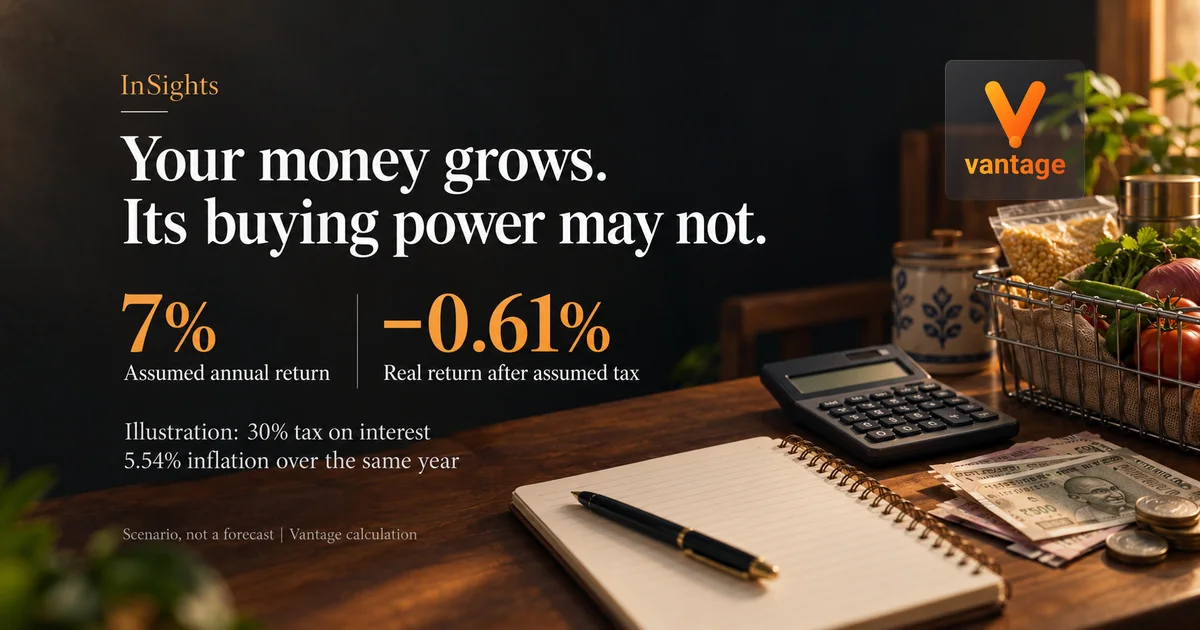
Calculator, notebook, rupee notes and groceries beside an illustrative 7% annual return and −0.61% real return, assuming 30% tax on interest and 5.54% inflation.
Inline Intelligence
A savings balance can grow while its purchasing power shrinks.
That possibility deserves attention after India’s September retail inflation reached 5.54%. A hypothetical investment earning 7% appears comfortably ahead of that figure. Yet, under an illustrative 30% tax deduction from interest, its net nominal return becomes 4.90%.
The central question is therefore more useful than asking whether your money is growing: is it growing fast enough to support the expenses and goals it must eventually fund?
What does the inflation figure actually tell you?
The government’s 12 October release puts September’s provisional year-on-year Consumer Price Index inflation at 5.54%, while food inflation was 7.74%.
These figures describe changes in measured consumer prices against the corresponding month a year earlier. They are neither a forecast for the next twelve months nor an exact measure of your household’s experience.
A household’s spending mix matters. A family allocating more of its budget to categories with faster price increases can experience greater pressure than the headline suggests.
The new CPI series uses a 2024 base year. That is another reason to examine the measurement basis before repeating claims about long-term inflation records.
Can a 7% return lose purchasing power?
Yes, under the assumptions below.
Consider ₹10 lakh invested for one year at a hypothetical 7% simple annual return. Assume an effective tax deduction equal to 30% of interest and, solely for illustration, a 5.54% increase in the relevant cost basket over that same year.
| Measure | Illustrative result |
|---|---|
| Starting investment | ₹10,00,000 |
| Gross interest at 7% | ₹70,000 |
| Assumed tax deduction from interest | ₹21,000 |
| Net interest | ₹49,000 |
| Ending balance after assumed tax | ₹10,49,000 |
| Ending purchasing power in starting-year rupees | Approximately ₹9,93,936 |
| Change in purchasing power | Approximately −0.61% |
The balance has increased by ₹49,000. But the amount required to buy the original basket has increased faster.
The inflation-adjusted calculation is:
Real return = (1 + net nominal return) ÷ (1 + inflation) − 1
In this example:
1.049 ÷ 1.0554 − 1 ≈ −0.61%
Without the assumed tax deduction, the same 7% return produces an inflation-adjusted gain of approximately 1.38%.
These are Vantage calculations. The return, tax deduction and future inflation rate are assumptions, not a current product quotation, a statement of your tax liability or an inflation forecast.
Does that make a deposit a bad investment?
The calculation establishes a purchasing-power trade-off. It does not decide whether an investment is suitable.
Money reserved for an imminent payment has a different job from money intended for retirement decades away. For a near-term commitment, access and capital stability can matter more than maximising expected return.
Chasing a higher return may introduce price fluctuations, credit risk, lock-ins or withdrawal restrictions. An investment that performs well over a long period can still be worth less when a particular bill becomes due.
SEBI’s investor education explains how inflation reduces purchasing power and encourages careful spending and investment planning. The practical extension is to examine each allocation against its purpose, rather than treating inflation as an instruction to move every rupee into a higher-risk asset.
Your personal inflation can change the answer
The national CPI is a useful benchmark. Your actual obligations provide the more specific test.
For an everyday spending review, compare similar quantities and services across comparable periods. Separate price increases from spending changes caused by buying more, upgrading products or adding a new expense.
For a future goal, update the cost of that goal itself. A home down payment, an education expense and an emergency reserve do not necessarily grow at the same rate.
There is also an important distinction between everyday price inflation and property appreciation. CPI cannot tell you how much a particular apartment, plot or construction contract will cost next year.
Why does this matter to a homebuyer?
A purchase can become harder to afford through two separate routes: less monthly surplus and more expensive borrowing.
If essential spending rises while income stays unchanged, the money available for a down payment or EMI falls. If the applicable loan rate also increases, the household must assess the repayment consequences.
The RBI’s 7 October decision raised the repo rate to 5.50%. How that affects a borrower depends on the loan’s benchmark, reset mechanism and terms.
We examined the difference between an unchanged instalment and an unchanged borrowing cost in this article -> Your EMI Hasnt Changed. Has Your Home Loan Become More Expensive?.
For a prospective purchase, assess the cash remaining after realistic living expenses, ownership costs and overlapping commitments such as rent before possession. A loan eligibility figure alone cannot establish that the purchase leaves enough flexibility.
For construction or interiors, obtain current quotations and understand their validity periods. Applying headline CPI mechanically to an old project estimate will not capture changes in specifications, labour or individual materials.
What should you reconsider first?
Start with the mismatch between the purpose of your money and how it is held.
For money needed soon, examine access, withdrawal conditions and the consequences of a loss. For long-term allocations, examine diversification, costs, tax treatment and whether the expected return reasonably compensates for the risks.
For debt, obtain the updated repayment schedule. Compare both the instalment and maturity date.
The September release is a reason to revisit assumptions. A decision to change an investment or delay a home purchase still requires evidence specific to that decision.
FAQ
1. Does 5.54% mean prices rose that much in one month?
No. It is the September year-on-year headline inflation rate.
2. Does food inflation describe every grocery item?
No. It is an aggregate measure. Individual items and the quantities a household buys can produce a different experience.
3. Is 7% a current deposit offer?
No. It is an illustrative return used to explain the difference between nominal and inflation-adjusted outcomes.
4. Is the assumed 30% tax deduction applicable to everyone?
No. Actual treatment depends on the investment, applicable law and the individual’s circumstances. The example is not a tax calculation for a specific reader.
5. Should emergency money always beat inflation?
Its purpose also includes availability and resilience. Accepting some purchasing-power erosion may be a reasonable trade-off for retaining suitable access and limiting risk.
6. Does higher inflation automatically mean another RBI rate hike?
No. A future decision depends on the evolving economic assessment. The inflation release itself is not a monetary-policy announcement.
7. Does CPI predict property-price increases?
No. Assess the specific location, property, transaction evidence and costs.
8. What is the most useful first calculation?
Estimate the realistic surplus after essential spending and existing obligations. Then compare investment returns after relevant costs and taxes against the expenses or goals they must fund.
Sources
Click an article title to view the source.
- Press Release of Consumer Price Index on Base 2024=100 for September, 2026 published on 12 October 2026 by MoSPI through the Press Information Bureau.
- Inflation: The General Increase in Prices in SEBI Investor Education, accessed on 13 October 2026. No publication date is displayed.
- Monetary Policy Statement, 2026-27 Resolution of the Monetary Policy Committee October 5 to 7, 2026 published on 7 October 2026 by the Reserve Bank of India.
- Your EMI Hasnt Changed. Has Your Home Loan Become More Expensive? published on 10 October 2026 in Vantage InSights.
Evidence Caveats
September’s CPI figures are provisional. The government release was inspected through its indexed text; direct page retrieval was intermittent.
The investment example assumes a single annual return, a simplified tax deduction and the same inflation rate over the illustrative investment period. September’s backward-looking inflation reading does not establish future inflation. Actual returns, tax treatment, compounding, fees and personal spending patterns can change the result.
This analysis does not establish future lender rates, local property prices or project costs.
Which assumption changes your decision most: the tax deduction, your personal spending inflation or when you need access to the money? Explain your reasoning in the attached forum discussion. Different experiences and counter-evidence are welcome.
Disclaimer
This article provides general information and educational analysis, not personalised investment, tax or borrowing advice. Consider your circumstances, verify applicable terms and rules, and seek qualified advice where needed.

From TatvaOps
Finance
Financing your project?
Explore credit and milestone-secured payment options with Tatva Finance.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
More from Real Estate
LTCG Tax Debate: Should You Delay Selling Investments?
Could waiting for LTCG tax relief cost more than it saves? With proposals under discussion, we examine how your current tax liability, market exposure and cash deadline should shape a planned investment sale.
Blackstones India Bet: What Should You Check?
Blackstone’s $100-billion India ambition is a useful signal. For your own money, the harder questions are access, valuation, cash flow and risk. Here is what to check before turning institutional optimism into a personal investment decision.
Senior Living: Buy the Home, Examine the Services: what most readers overlook
Rustomjee’s senior-living evaluation raises a household question: can you afford and rely on the services after buying the home? We examine recurring charges, operator responsibilities, changing support needs and exit flexibility.
Inline Intelligence
Key Insight Actions
Connected knowledge for Finance
Move between tutorials, discussions, Studio, and hubs without losing context.
Conclusion Intelligence
Was this helpful?
Let us know what you think