
PSU vs Private Banks: What Q2 Earnings Mean for Investors
Summary
India's Q2 FY27 results show improving PSU bank margins and rising funding pressure at private lenders. Explore profitability, valuations, asset quality and what investors should examine before choosing bank stocks. India's banking sector is showing an interesting divide. Public sector banks are experiencing stronger improvements in lending profitability, while several leading private sector banks are facing pressure from higher deposit costs. The divergence has become more visible during the Q2 FY2026–27 earnings season.
Published on
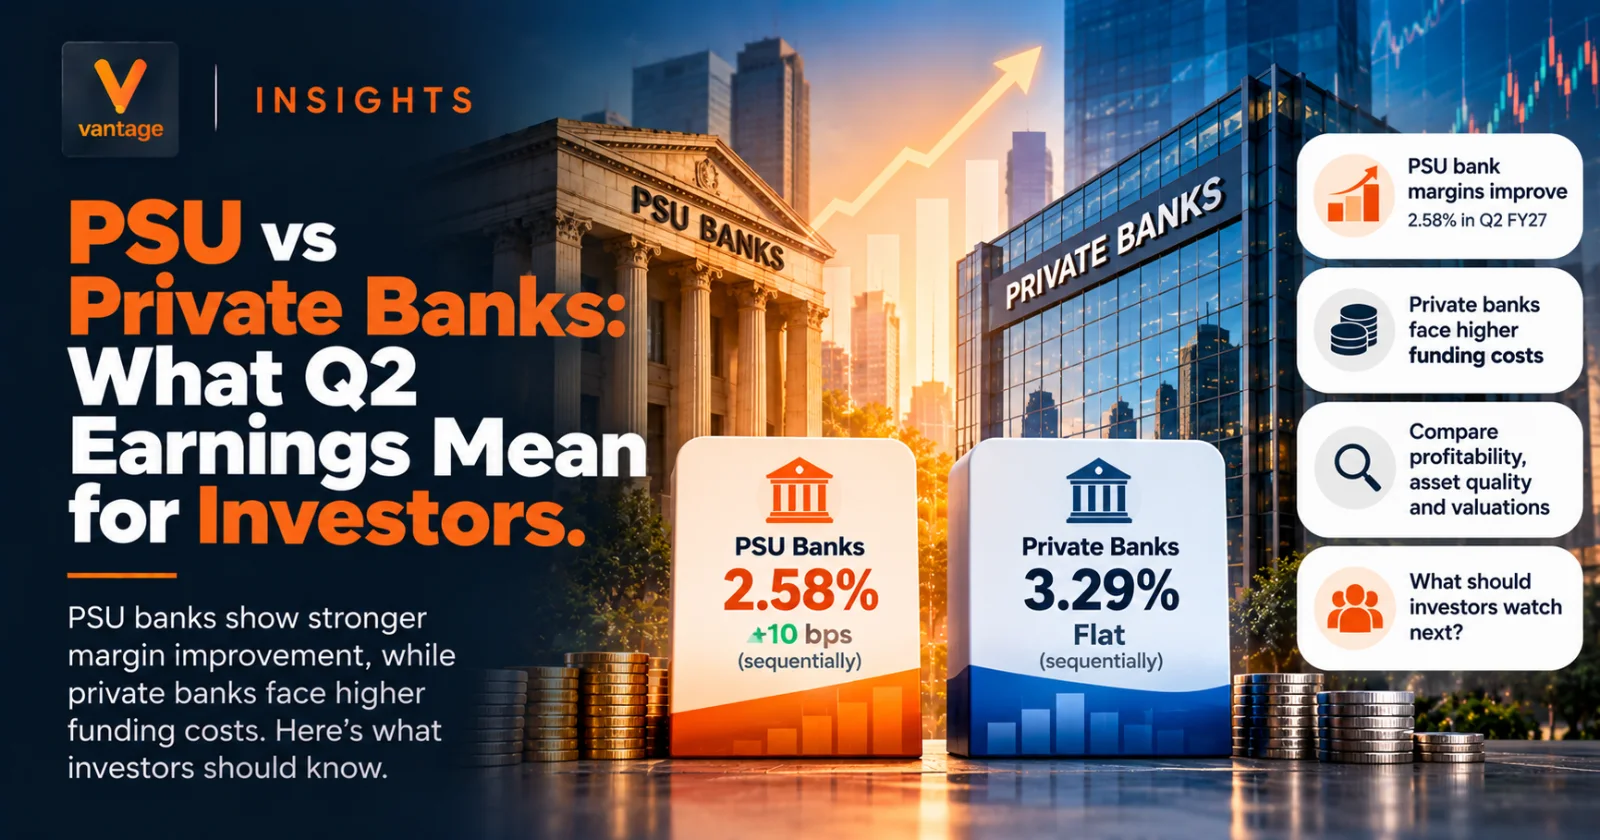
Comparison of Indian public-sector and private-sector banks based on Q2 FY27 earnings, highlighting differences in net interest margins, funding costs, profitability and stock-market valuations.
Inline Intelligence
India's banking sector is showing an interesting divide.
Public-sector banks are experiencing stronger improvements in lending profitability, while several leading private-sector banks are facing pressure from higher deposit costs.
The divergence has become more visible during the Q2 FY2026–27 earnings season.
An Economic Times report published on October 27, citing CareEdge Ratings analysis, found that select public-sector banks improved their net interest margins while private-sector banks experienced relatively weaker margin trends.
For investors, the development raises an important question.
Are public-sector bank stocks becoming more attractive than private-bank shares, or could the current earnings divergence be temporary?
Understanding the answer requires looking beyond quarterly profit numbers.
What Q2 FY27 Reveals About India's Banks
Banks earn a substantial portion of their income by lending money at rates higher than their funding costs.
A bank may receive deposits from customers, use those funds to support loans and earn interest on the difference.
But its profitability also depends on operating expenses, credit losses, capital requirements and non-interest income.
The latest results show that public-sector and private-sector lenders are experiencing different funding conditions.
According to the CareEdge-based comparison reported by Economic Times:
| Indicator | Selected PSU banks | Selected private banks |
|---|---|---|
| Q2 net interest margin | 2.58% | 3.29% |
| Sequential NIM movement | +10 basis points | Broadly flat |
| Annual NIM movement | +15 basis points | -8 basis points |
| Annual net interest income growth | 18.4% | 14.4% |
The data provides two important observations.
First, private banks continue to report higher absolute net interest margins.
Second, public-sector banks currently show stronger improvement in those margins.
Both can be true simultaneously.
The comparison should not be interpreted as proof that all public-sector banks are more profitable or financially stronger than all private lenders.
What Is Net Interest Margin?
Net interest margin, commonly called NIM, measures the relationship between a bank's net interest income and its average interest-earning assets.
Net interest income is the difference between interest earned and interest paid.
A simplified formula is:
Net interest margin = Net interest income ÷ Average interest-earning assets × 100
Consider a hypothetical bank with ₹10,000 crore of average interest-earning assets.
If its annualised net interest income is ₹300 crore, its NIM is 3%.
If annualised net interest income increases to ₹320 crore while average assets remain unchanged, its NIM becomes 3.2%.
That 20-basis-point improvement can be meaningful for a large lending institution.
However, NIM is not the same as net profit margin or return on equity.
A bank can report a healthy NIM while facing high operating expenses or significant bad-loan provisions.
Investors should therefore treat NIM as one component of the overall financial picture.
Why Are Public-Sector Bank Margins Improving?
The current improvement appears partly connected to the relationship between lending yields and funding costs.
The CareEdge-based analysis found that lending yields at selected public-sector banks increased by 18 basis points sequentially, compared with an increase of nine basis points in funding costs.
That difference supported net interest margins.
Public-sector lenders also reported stronger growth in net interest income than the selected private-bank group.
But investors should be careful about projecting this improvement indefinitely.
Deposit pricing, loan repricing and borrowing conditions can change over time.
A temporary advantage in the funding cycle does not necessarily establish a permanent competitive advantage.
The more important test is whether banks can maintain profitable loan growth without allowing credit risk or operating costs to increase disproportionately.
Why Are Private Banks Facing Higher Funding Costs?
Private-sector banks continue expanding their lending portfolios.
That growth requires funding.
One challenge is that obtaining deposits can become increasingly expensive when banks compete for household and corporate savings.
Higher term-deposit rates may attract funds, but they also increase interest expenses.
Some private lenders have additionally mobilised significant FCNR(B) deposits.
FCNR(B) stands for Foreign Currency Non-Resident (Bank), a deposit facility available to eligible non-resident customers under applicable banking rules.
These deposits can help banks secure funding in foreign currencies.
However, the overall economics depend on interest costs, currency arrangements, swaps and how quickly the resulting funds are deployed profitably.
A bank may raise funds before earning the full return expected from using them.
This can temporarily pressure margins.
For example, Axis Bank reported a Q2 FY27 NIM of 3.36%.
The bank also disclosed a NIM of 3.47% excluding the identified impact of FCNR(B) funding.
That does not mean the entire margin difference will necessarily reverse automatically.
It indicates that funding structure is an important variable in evaluating the underlying performance.
Are Private Banks Actually Performing Poorly?
Not across the board.
Major private-sector banks reported substantial profits in Q2 FY27.
| Bank | Q2 FY27 net profit | Approx. YoY change |
|---|---|---|
| HDFC Bank | ₹19,510 crore | +4.7% |
| ICICI Bank | ₹14,843 crore | +20.1% |
| Axis Bank | ₹7,003 crore | +38% |
| Kotak Mahindra Bank | ₹4,211 crore | +29% |
These are reported standalone quarterly results, rounded for readability.
The variation demonstrates why broad sector labels are insufficient for selecting individual investments.
HDFC Bank's profit growth was relatively modest, while other private lenders recorded faster increases.
But faster profit growth is not automatically evidence of a stronger investment.
It may reflect base effects, changes in provisions, operating performance or other bank-specific developments.
Axis Bank, for example, reported growth in lending and net interest income alongside the effects of FCNR(B) funding.
The correct interpretation requires examining the underlying financial statements, rather than simply ranking banks by profit growth.
Why Deposit Growth Can Be Misleading
Investors frequently interpret strong deposit growth as positive.
Deposits provide banks with funding that supports lending and financial flexibility.
But not all deposits have the same cost.
Current-account and savings-account deposits, collectively called CASA deposits, often provide relatively inexpensive funding compared with many term deposits.
Banks with strong, stable CASA franchises may have advantages in maintaining funding costs.
However, a rising deposit balance can sometimes reflect expensive funding that produces a smaller immediate profitability benefit.
For example, an increase in FCNR(B) deposits may improve headline deposit growth while affecting interest expenses and reported margins.
Investors should compare total deposits with the mix, price and stability of those deposits.
The relationship between deposit growth and loan growth also matters.
Rapid credit expansion without proportionate stable funding can create additional financial pressure.
Does Stronger PSU Performance Mean Better Bank Stocks?
Not necessarily.
The market value of a bank is influenced by its expected future earnings, asset quality, capital requirements, governance and the valuation investors are willing to pay.
Public-sector bank shares may look attractive when earnings improve and valuations remain relatively low.
However, lower valuations can also reflect concerns about earnings sustainability, historical credit performance or other risks.
Private-sector banks may trade at higher valuations because investors expect stronger profitability, operating efficiency or growth.
Those expectations are not guaranteed.
Business Standard reported on October 21 that public-sector banks had taken a lead in certain return measures, while private lenders retained a valuation premium.
The article also identified concerns about the sustainability of PSU-bank returns.
This is a useful reminder that profitability and market valuation are different concepts.
A company can be financially healthy but expensive as an investment.
Another can appear inexpensive but face risks that justify its lower valuation.
Understanding Price-to-Book Value
Price-to-book value, or P/B, is commonly used when evaluating banking stocks.
It compares a company's market value with its accounting book value.
Consider two hypothetical banks.
Bank A trades at 1.2 times book value and generates a return on equity of 12%.
Bank B trades at 2.0 times book value and generates a return on equity of 18%.
Bank A appears cheaper using P/B alone.
But Bank B generates a higher return on shareholder equity.
Whether the higher valuation is justified depends on the sustainability of those returns, asset quality, growth prospects and risks.
The example shows why investors should avoid choosing bank stocks solely because their P/B ratio is low.
Price-to-book and return on equity should be considered together.
What About Non-Performing Assets?
A non-performing asset, or NPA, is a loan classified as non-performing under applicable banking rules.
Asset quality is one of the most important indicators of risk in banking.
A bank can expand lending and report rising interest income while also increasing exposure to borrowers who may struggle to repay.
If credit losses later rise, provisions can reduce profits and erode capital.
Investors should therefore monitor gross and net NPA ratios, provisions and changes in stressed assets.
The latest results show improvements in asset quality at several private lenders.
For instance, HDFC Bank reported a gross NPA ratio of 1.11% for Q2 FY27.
IndusInd Bank reported a gross NPA ratio of 2.73% and a net NPA ratio of 0.83%.
These different figures should not be compared without considering the banks' loan portfolios, underwriting approaches and other financial characteristics.
A complete assessment includes both profitability and the risks being taken to generate it.
Could the Current Divergence Reverse?
Yes.
The current advantage in margin momentum could narrow if funding conditions change.
For private banks, the costs associated with certain deposit mobilisation activities may become less significant as funds are deployed or repriced.
For public-sector banks, changes in loan yields or deposit costs could reduce recent improvements.
The interest-rate environment also matters.
Banks do not necessarily reprice all deposits and loans simultaneously.
The timing of changes can affect profitability differently across institutions.
Credit demand, competitive intensity and economic conditions can further influence outcomes.
Investors should therefore avoid assuming that one quarter establishes a permanent earnings trend.
What Should Long-Term Banking Investors Track?
Five indicators deserve particular attention.
1. Net interest margin
Is the bank maintaining healthy interest earnings relative to funding costs?
2. Return on assets and return on equity
Are improvements in reported profit translating into sustainable returns?
3. Asset quality
Are bad loans, stressed assets and credit-loss provisions under control?
4. Deposit franchise
Can the bank attract stable deposits at reasonable costs?
5. Valuation
Does the market price reasonably reflect future profitability, capital needs and downside risks?
These indicators should be assessed over multiple quarters.
A bank that performs well in one reporting period may not maintain the same results under different economic conditions.
Should Investors Prefer a Banking ETF?
Some investors may prefer diversified banking-sector exposure rather than selecting individual bank stocks.
A banking ETF can provide exposure to several listed banks through a single market-traded product.
However, diversification within banking does not eliminate sector-specific risks.
Banking ETFs can still be sensitive to interest rates, credit cycles, regulation and concentration in large constituents.
Different indices may also have different allocations to public-sector and private-sector banks.
Investors should examine the underlying index, portfolio concentration, expenses, tracking differences and liquidity before choosing a product.
A diversified broad-market fund may offer different risk characteristics from a banking-sector-specific investment.
The appropriate choice depends on the investor's goals, time horizon and existing portfolio exposure.
What Could Influence Bank Stocks in the Coming Quarters?
The next earnings periods will provide evidence of whether the funding-cost divergence is temporary or persistent.
Important developments include the pricing and deployment of deposits, credit growth, changes in loan yields and asset quality.
The performance of corporate lending and retail loan portfolios will also matter.
Investors should examine whether banks are maintaining financial discipline while competing for customers.
Strong loan growth can support income, but it can also increase future credit risk if underwriting standards weaken.
Likewise, aggressive deposit mobilisation can fund expansion but reduce margins if costs rise too quickly.
The banks that manage this balance most effectively may be better positioned to sustain profitability.
Conclusion
India's Q2 FY27 banking results reveal a meaningful shift in margin momentum.
Public-sector banks are experiencing stronger improvement in net interest margins, while several large private lenders are facing increased funding pressure.
But the distinction is more nuanced than a straightforward victory for one category of banks.
Private lenders continue to report higher absolute margins in the selected comparison and, in many cases, substantial profit growth.
For stock-market investors, the important question is not simply whether public-sector or private-sector banks are doing better today.
It is which institutions can sustain profitability, manage credit risk and justify their market valuations over time.
Banking investments require careful analysis of both the quality of earnings and the price paid for those earnings.
FAQ
1. Are PSU banks performing better than private banks in Q2 FY27?
Select public-sector banks reported stronger net interest margin improvements, but private banks continued to have higher absolute margins in the reviewed comparison. Individual bank performance varies.
2. Why are private bank margins under pressure?
Higher deposit costs and the financial effects of FCNR(B) deposit mobilisation have contributed to margin pressure at several large private lenders.
3. Does higher net profit make a bank stock attractive?
Not automatically. Investors must also consider valuation, asset quality, return on equity, funding costs and the sustainability of earnings.
4. What does NIM mean in banking?
Net interest margin measures a bank's net interest income relative to its average interest-earning assets.
5. Are PSU bank stocks always cheaper?
Public-sector banks have often traded at lower price-to-book valuations than major private lenders, but the difference varies across companies and time.
6. Is a banking ETF safer than buying one bank stock?
A banking ETF can reduce company-specific concentration, but it still carries banking-sector and equity-market risks.
Sources
Click an article title to view the source.
-
PSU vs Private Banks: The Real Story Behind the Q2 Divergence published on 27 October 2026 by The Economic Times.
-
Public-Sector Banks Take Returns Lead; Private Banks Hold Valuation Edge published on 21 October 2026 by Business Standard.
-
Axis Bank Q2 FY27 Financial Results published in October 2026 by Axis Bank.
-
IndusInd Bank Announces Q2 FY27 Financial Results published on 23 October 2026 by IndusInd Bank.
-
HDFC Bank Q2 Profit Rises 4.7% published on 17 October 2026 by Reuters.
-
Kotak Bank Q2 Profit Rises 29% published on 24 October 2026 by Reuters.
Evidence Caveats
The sector-level margin comparison is based on selected banks in CareEdge Ratings research reported by Economic Times, rather than a complete census of Indian banks.
Individual bank profit figures are rounded and refer to standalone quarterly results where specified.
The discussion of valuations is qualitative. No live bank share valuations or stock-price targets are presented.
The price-to-book example is hypothetical and does not represent actual listed banking stocks.
Join the Discussion
If you were investing in India's banking sector today, would you favour improving public-sector bank earnings or the established franchises of major private banks?
Which matters more to you: valuation, consistent profitability, asset quality or long-term growth?
Share your perspective with other readers in the Vantage community.
Thoughtful comparisons can help investors understand the differences between short-term earnings momentum and long-term investment quality.
Disclaimer
This article is for general education and editorial purposes only. It is not personalised financial or investment advice. Banking shares, mutual funds and ETFs involve market and capital-loss risks. Readers should evaluate current financial disclosures, investment objectives, risk tolerance and market valuations before making investment decisions.
From TatvaOps
Property Development
Developing a property?
Structured oversight for multi-unit and investor-led builds.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
1 reply already on Forums
More from Real Estate
Mumbai Luxury Home Data What Buyers Should Check
Luxury registration totals are not a like-for-like price index. Here is how buyers can compare properties and ownership costs.
Binance Security Incident What Holders Can Check
The Binance incident highlights the difference between a displayed balance and access to assets. Here are practical checks for holders.
Gurugram Power Choice What Residents Should Check
A proposed second electricity distributor is on hold. Here is what Gurugram and Nuh residents can check on bills and service.
Inline Intelligence
Key Insight Actions
Connected knowledge for Banking Analysis
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Topic hubs
Conclusion Intelligence
Related Discussions
Was this helpful?
Let us know what you think