
US Fed Rate Hold What Indian Households Can Check
Summary
A practical look at dollar expenses, overseas investments and rupee budgeting after the US Fed rate hold. A US interest rate decision can matter to an Indian family even when it has no US bank account. A dollar denominated tuition bill, an overseas investment or a planned trip can change in rupee cost as exchange rates move. The latest Fed hold is a reason to review that exposure, not proof that a particular currency move will follow. What changed at the Fed?
Published on
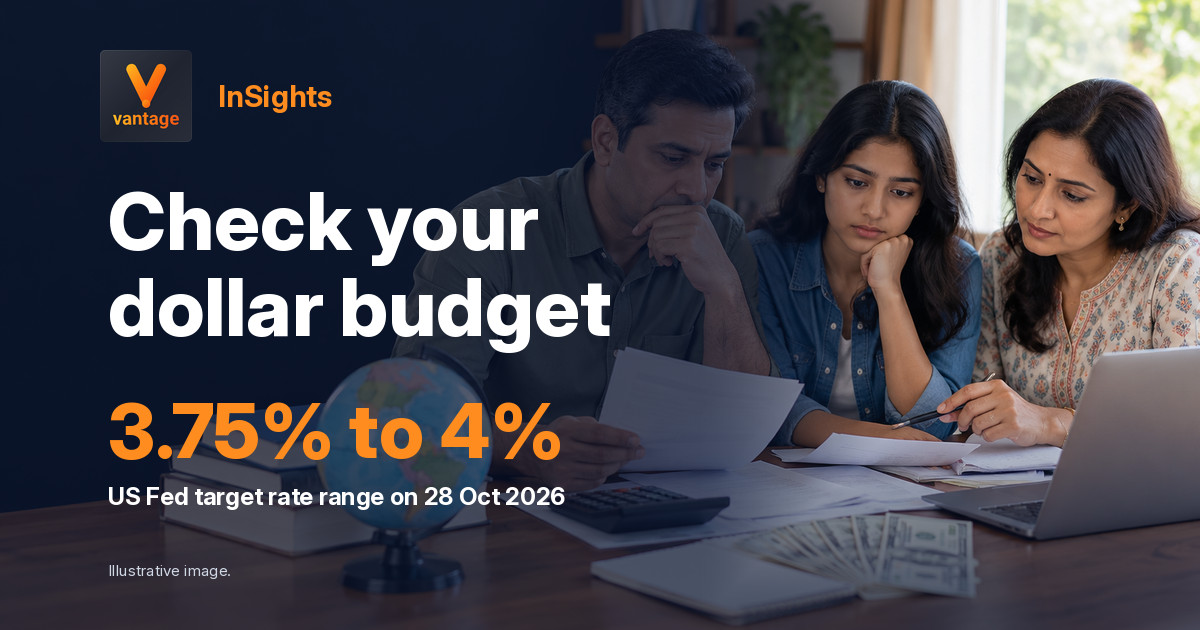
US Fed rate hold and currency exposure illustrated by a family reviewing overseas education costs
Credit: Illustrative image
Inline Intelligence
A US interest-rate decision can matter to an Indian family even when it has no US bank account. A dollar-denominated tuition bill, an overseas investment or a planned trip can change in rupee cost as exchange rates move. The latest Fed hold is a reason to review that exposure, not proof that a particular currency move will follow.
What changed at the Fed?
On 28 October 2026 the Federal Reserve kept its federal funds target range at 3.75% to 4%. Its policy committee voted 10 to 2, with two members preferring a quarter-percentage-point increase. The committee said inflation remained elevated and that additional information would help determine the appropriate stance.
The decision was a hold, not a promise to keep rates unchanged at the next meeting. The Federal Reserve sets US monetary policy; the Reserve Bank of India sets India's policy rate. A US announcement does not automatically change an Indian loan EMI or an Indian deposit rate.
How can a US decision reach a rupee budget?
Rate expectations can affect yields on US assets and the relative appeal of holding dollars. Investors may adjust portfolios in response, influencing capital flows and exchange rates. This is a possible transmission channel rather than a reliable one-step prediction. Oil prices, India's own economic conditions, flows and central bank actions can all matter at the same time.
Reuters reported that the dollar was steady after the decision, while the future rate path remained uncertain. A 29 October early-trade report put the rupee at 95.17 to the US dollar at that moment. Exchange rates change throughout the day, and a retail conversion typically includes a provider's spread and fees. The quoted interbank observation should not be treated as the price available to every household.
Tuition, travel and investments have different risks
A family with a fixed dollar bill due soon faces a budgeting problem: a weaker rupee increases the rupees needed for the same number of dollars. A family with no dollar payment or foreign assets may have no immediate reason to act on this decision. A long-term investor in international assets faces both the asset's market return and the currency movement when measured in rupees. Either can rise or fall, and costs and taxes can reduce the final result.
Consider a hypothetical USD 10,000 fee due in the future. At Rs 95 per dollar, the currency conversion alone is Rs 9.5 lakh. At Rs 100 per dollar, it is Rs 10 lakh, a difference of Rs 50,000. These are illustrative exchange rates, not forecasts or current bank quotes, and exclude remittance charges and taxes. If the rupee strengthens instead, the rupee cost could fall. The family's actual bill depends on the date, provider and terms of conversion.
Investing more overseas simply because US rates are higher would combine several decisions. The investor would need to assess the underlying product, its valuation, exposure, fees, liquidity and time horizon as well as currency risk. A US policy-rate range is not the return promised by an overseas fund or account.
What Households and Retail Investors Can Do Now
- List exposure: Check your tuition invoice, travel booking or investment statement for amounts in foreign currency and the payment or review dates. A fixed near-term bill and a long-term investment need different treatment.
- Calculate a budget range: Compare the provider's current all-in quote with two clearly labelled scenarios above and below it. For example, USD 10,000 at Rs 95 and Rs 100 per dollar differs by Rs 50,000 before fees. These are editorial scenarios, not forecasts.
- Compare conversion costs: Ask your bank or authorised remittance provider for the exchange rate, spread, fees and applicable taxes for the same amount and date. Verify the final quote before authorising a transfer.
- Review investment exposure: Check the latest fund factsheet or broker statement for currency exposure, expense ratio, holdings and redemption terms. Compare those with your goal and existing portfolio rather than the Fed rate alone.
- Set a review date: Check the Fed's official statement, your provider's quote before a payment and the relevant fund disclosure at the next scheduled review.
If a dollar bill is due soon, consider setting a rupee budget and comparing actual conversion quotes; a sudden rate change can affect the amount needed. If your foreign investment is for a long-term goal, consider reviewing overall allocation and product risks instead of reacting to one announcement. If you have no foreign-currency obligation or exposure, no immediate transaction follows from this decision.
Monitor subsequent Fed statements, actual bank conversion quotes and your payment deadline. None provides a guaranteed exchange-rate direction.
FAQ
Did the Fed cut rates?
No. It maintained the target range at 3.75% to 4% on 28 October.
Does this change an Indian home-loan rate immediately?
Not automatically. The RBI, lender benchmark and loan terms govern the direct pricing mechanism.
Will the rupee necessarily weaken?
No. Currency movements depend on several forces and cannot be inferred from the hold alone.
Is the reported market rate the rate my bank will offer?
Not necessarily. Retail quotes can include a spread and fees.
Is the Fed target rate my international fund's return?
No. A fund's performance depends on its holdings, market movements, currency, costs and taxes.
Should everyone convert money now?
No universal timing decision follows. Review the amount, deadline, available quotes and personal circumstances.
Sources
Click an article title to view the source.
- Federal Reserve issues FOMC statement published on 28 October 2026 by the Federal Reserve.
- Dollar steady after Fed hold leaves rate path murky published on 29 October 2026 by Reuters.
- Rupee rises 11 paise to 95.17 against U.S. dollar in early trade on Thursday published on 29 October 2026 by Indmedia News, reproducing reporting attributed to The Hindu.
Evidence Caveats
The Federal Reserve statement establishes the decision and vote. The exchange rate cited is a dated early-trade report rather than a live retail quote. The currency examples are hypothetical, exclude fees and taxes, and are not forecasts. Multiple forces affect exchange rates and investment returns.
How do you plan for currency changes when paying an overseas bill or reviewing foreign investments? Share a question or practical experience in the attached discussion.
Disclaimer
This article is general information, not personalised financial, investment or tax advice. Consider qualified advice appropriate to your circumstances.
From TatvaOps
Property Development
Financing your project?
Explore credit and milestone-secured payment options with Tatva Finance.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
More from Real Estate
Mumbai Luxury Home Data What Buyers Should Check
Luxury registration totals are not a like-for-like price index. Here is how buyers can compare properties and ownership costs.
Binance Security Incident What Holders Can Check
The Binance incident highlights the difference between a displayed balance and access to assets. Here are practical checks for holders.
Gurugram Power Choice What Residents Should Check
A proposed second electricity distributor is on hold. Here is what Gurugram and Nuh residents can check on bills and service.
Inline Intelligence
Key Insight Actions
Connected knowledge for Personal Finance
Move between tutorials, discussions, Studio, and hubs without losing context.
Conclusion Intelligence
Was this helpful?
Let us know what you think