
PNB Deposit Claims What Savers Can Check Now
Summary
PNB reports three settled claims in Greater Noida. Learn how to check deposit records, report discrepancies and review escalation options. A bank's assurance that genuine claims will be honoured can be reassuring, but it does not tell an individual customer whether a particular discrepancy has been verified or when it will be resolved. The Greater Noida allegations make the distinction between a bank's announcement and an individual account record especially important. Punjab National Bank said three claims totalling Rs 43 lakh had been settled as of Wednesday and that it was examining other complaints.
Published on
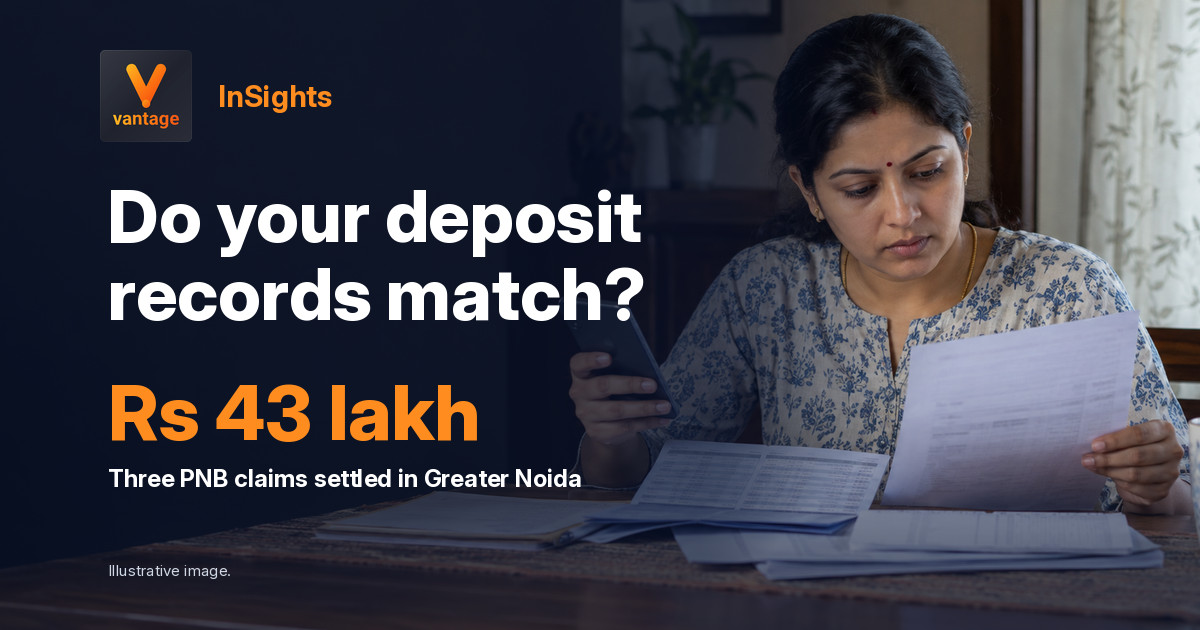
Woman comparing account records at home after PNB deposit claims in Greater Noida
Credit: Illustrative image
Inline Intelligence
A bank's assurance that genuine claims will be honoured can be reassuring, but it does not tell an individual customer whether a particular discrepancy has been verified or when it will be resolved. The Greater Noida allegations make the distinction between a bank's announcement and an individual account record especially important.
What is known about the claims?
Punjab National Bank said three claims totalling Rs 43 lakh had been settled as of Wednesday and that it was examining other complaints. The statement was reported by Business Standard on 29 October. The bank's statement is an assurance, not proof that all remaining claims have been resolved.
Mint's report describes complaints involving savings accounts and fixed deposits and says investigations continue. It distinguishes the amounts in customer complaints from the bank's lower preliminary assessment. The size of the final loss and responsibility for individual transactions are not established here.
What can a depositor verify?
A fixed deposit receipt, a passbook or an earlier statement is a starting point. Compare it with the current account and deposit records obtained through a verified bank channel. Check deposit number, principal, maturity date, status and whether there are transfers or premature closures that you do not recognise. An apparent mismatch may have an explanation, so seek a written transaction history before drawing conclusions.
Electronic transaction disputes have specific rules. In its financial awareness guidance, the Reserve Bank of India advises reporting unauthorised electronic transactions immediately. It describes different liability outcomes depending on the cause and reporting circumstances, including bank negligence and certain third-party breaches. Those provisions cannot be assumed to resolve every disputed deposit or branch transaction without examining its facts.
The bank's customer-liability circular states that the burden of proving customer liability for unauthorised electronic banking transactions lies with the bank. The customer should nevertheless preserve a clear record and request a complaint acknowledgement. Do not give passwords or one-time codes to anyone offering to recover money.
Does a settlement prove all deposits are safe?
No. The three settlements show that PNB reported resolving those particular claims, while the bank continues to examine other complaints. They do not establish how many claims will be accepted or how long each case will take. Nor does an allegation at one branch prove that other branches have the same problem.
The case also illustrates the difference between checking an account and taking an investment decision. A reader with no discrepancy may simply reconcile records regularly. Someone who sees an unknown debit has a more urgent reason to contact the bank and secure their account. Neither situation proves that moving all savings is the right response; liquidity needs, deposit terms and applicable protections also matter.
What Retail Savers Can Do Now
- Reconcile the balance and deposit status using the bank's verified app, statement or branch. Compare account number, deposit principal, maturity and transaction dates with your own records.
- Record each unexplained entry. For example, if a statement shows an unauthorised Rs 20,000 debit from a previously verified Rs 1,00,000 balance, the apparent difference is Rs 20,000, assuming no other transactions. This is an illustration, not an estimated loss in the PNB case.
- Report a disputed electronic transaction immediately to the bank through its official channel. Ask for the complaint reference and written acknowledgement, and preserve statements and deposit receipts. The RBI guidance explains why reporting time and the cause can matter.
- Escalate an unresolved complaint through the bank's grievance process. Review the RBI financial awareness guidance on the Integrated Ombudsman Scheme and complaint process if the scheme's conditions are met. Check eligibility and time limits in the scheme before filing.
- Monitor PNB's written claim decision and investigators' updates. A verified finding on the cause, a claim decision or a change in official guidance could change the next step.
If an unknown transaction appears, consider reporting it immediately and asking the bank to protect the account. If records match and there is no disputed transaction, consider a routine review rather than assuming the reported case affects your account. Keep personal account numbers out of public discussions.
FAQ
Has PNB paid every complainant?
The bank reported three settled claims; the available reports do not establish that all complaints have been resolved.
Is the final loss known?
No. Reported complaint amounts and the bank's preliminary assessment differ, and the investigation continues.
Does the RBI electronic transaction guidance cover every dispute?
No. Its applicability depends on the transaction and circumstances. Ask the bank which rules apply to the particular complaint.
What should I retain?
Keep statements, deposit receipts, transaction details and complaint acknowledgements securely. Avoid sharing credentials.
Where can an unresolved bank complaint be escalated?
First use the bank's complaint process. The RBI's complaint portal and ombudsman scheme set out the conditions for escalation.
Sources
Click an article title to view the source.
- PNB settles 43 lakh in claims amid Greater Noida branch fraud allegations, Press Trust of India in Business Standard, 29 October 2026.
- PNB suspends 12 employees after customers report missing funds, Mint, 30 October 2026.
- Financial Awareness Messages, Reserve Bank of India, accessed 30 October 2026.
- Customer Protection: Limiting Liability of Customers in Unauthorised Electronic Banking Transactions, Reserve Bank of India, 6 July 2017.
Evidence Caveats
The bank's reported settlement figure is attributed to its statement as reproduced by the press; the underlying individual claim decisions were not reviewed. The investigation is ongoing and reported loss estimates differ. The worked example is hypothetical. RBI rules must be applied to the facts of the specific transaction.
What would make a bank's complaint process easier to understand and verify? Share an experience or a constructive suggestion in the attached forum discussion, without identifying an account or individual.
Disclaimer
This article is general information, not financial or legal advice. Outcomes depend on the facts and applicable rules; seek qualified advice for your circumstances.
From TatvaOps
Farm Infrastructure & Self-Sustainability
Comparing contractor quotes?
Line up pricing, scope, and timelines before you sign.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
More from Real Estate
Mumbai Luxury Home Data What Buyers Should Check
Luxury registration totals are not a like-for-like price index. Here is how buyers can compare properties and ownership costs.
Binance Security Incident What Holders Can Check
The Binance incident highlights the difference between a displayed balance and access to assets. Here are practical checks for holders.
Gurugram Power Choice What Residents Should Check
A proposed second electricity distributor is on hold. Here is what Gurugram and Nuh residents can check on bills and service.
Inline Intelligence
Key Insight Actions
Connected knowledge for Banking and Consumer Protection
Move between tutorials, discussions, Studio, and hubs without losing context.
Conclusion Intelligence
Was this helpful?
Let us know what you think