
Inflation Is Above 6. Is Your Household Budget Ready for the Squeeze?

Summary
India’s inflation has crossed 6%, while food inflation is near 9%. Here are the checks that matter. Your home loan EMI may be unchanged. Your salary may be unchanged too. But if groceries and other essentials are taking a larger share of your income, the money left for savings or a home purchase may already be shrinking. India’s retail inflation rose to 6.09% in October 2026, while food inflation reached 8.94%, according to Reuters and Business Standard.
Published on
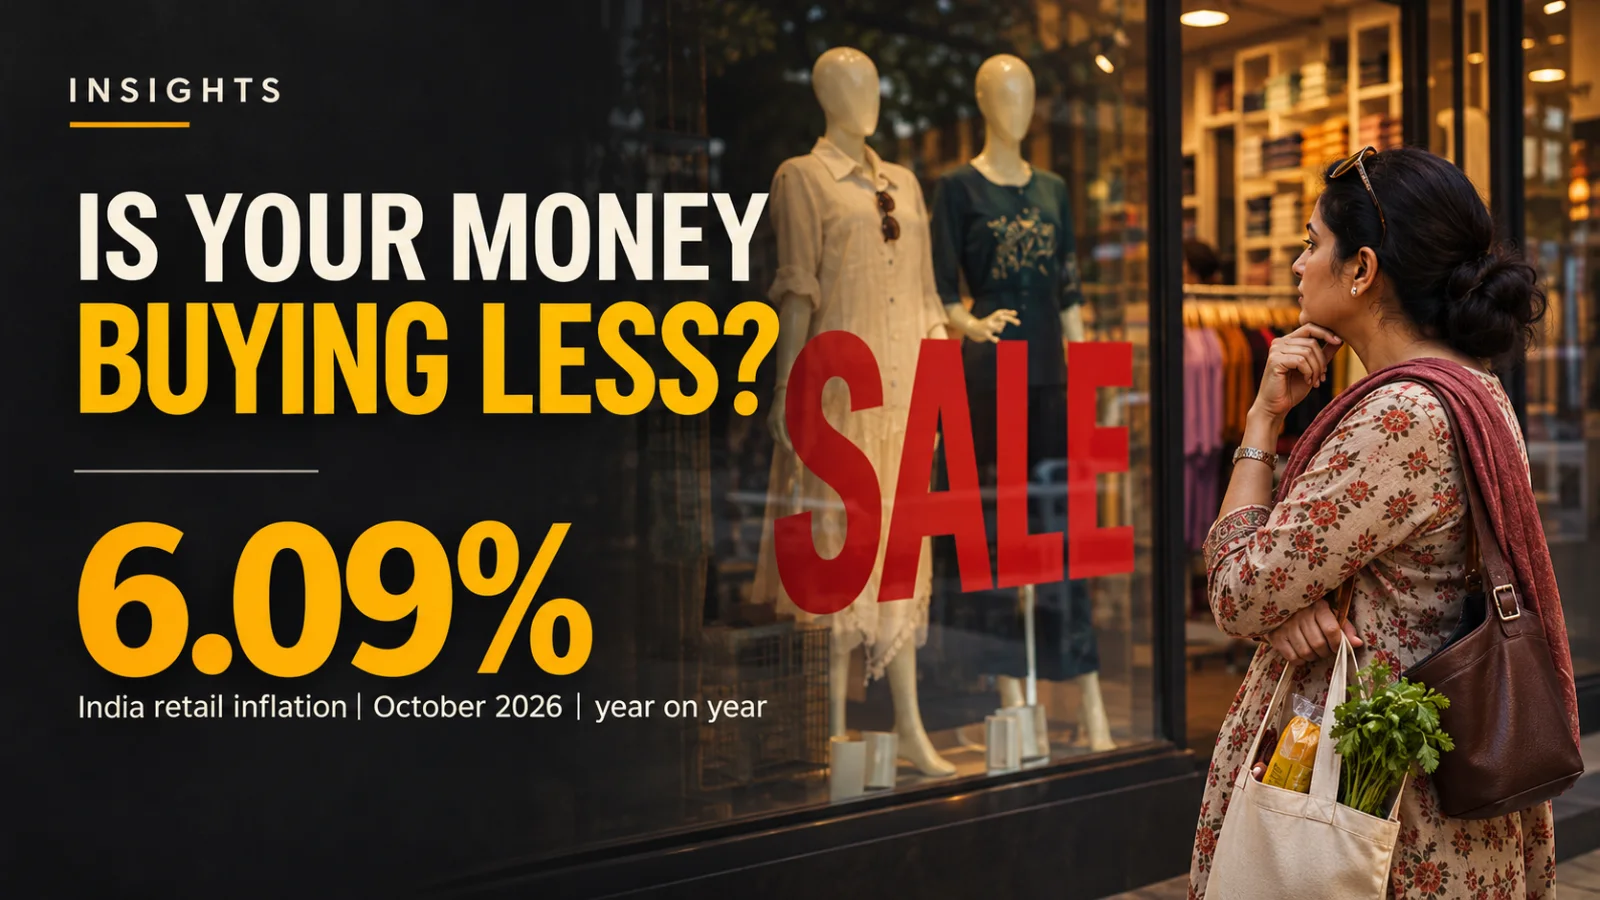
An editorial illustration connects the October inflation figure with a question for households: how far does their money go when prices rise?
Inline Intelligence
Your home-loan EMI may be unchanged. Your salary may be unchanged too.
But if groceries and other essentials are taking a larger share of your income, the money left for savings or a home purchase may already be shrinking.
India’s retail inflation rose to 6.09% in October 2026, while food inflation reached 8.94%, according to Reuters and Business Standard.
The headline raises a practical question for households: how much room is left in your budget if essential costs continue to rise?
First, understand what 6.09% actually means
The retail inflation figure measures the change in the consumer price index compared with October 2025. It does not mean all prices rose by 6.09%, and it does not describe the price increase during October alone.
Your experience may be different from the national average. A household that spends a larger proportion of its income on food may feel rising food prices more sharply than one with a different spending mix.
Food inflation of 8.94% is also an aggregate measure. It does not mean every grocery item increased by that amount.
The pressure can reach your home budget before your EMI changes
Imagine a household that has set aside a fixed amount each month for a future down payment.
If groceries, transport, school fees or other essentials cost more, the family may save less unless income rises or spending elsewhere falls. That can delay the savings goal even if the price of the home itself remains unchanged.
For an existing homeowner, the same pressure can reduce the cushion available after paying the EMI.
That is why it helps to look at two separate questions:
- How much money remains after essential spending and existing obligations?
- What would happen if the applicable home-loan rate changed later?
A tighter monthly budget does not prove that a lender will increase its rate. The two risks should be assessed separately.
Will your home-loan EMI rise?
Not automatically.
The RBI’s inflation target is 4%, with a tolerance band of 2% to 6%. October inflation is above that band, but the reading alone does not determine the RBI’s next decision.
The RBI had already raised the repo rate to 5.50% in October. Whether any future policy change affects your loan depends on your lender, your loan’s benchmark, the reset schedule and the terms of your agreement.
A borrower may face a higher EMI, a longer repayment period or both. A longer tenure can mean paying interest for more time, even if the monthly instalment stays similar.
Vantage’s earlier analysis of the RBI rate hike and housing affordability explains why borrowers who are already close to their affordability limit may be more sensitive to changes.
What about savings and fixed deposits?
Inflation affects what your savings can buy. A positive return in rupees may translate into a smaller gain in purchasing power after inflation and tax.
For a simple illustration, suppose ₹100 grows to ₹106 after one year, before tax. If the cost of the same basket of goods rises from ₹100 to ₹106.09 over that year, the ₹106 would buy slightly less of that basket than the original ₹100 did.
This is only an illustration. It assumes a 6% annual return and 6.09% inflation over the same future year. October’s inflation figure describes the past year and is not a forecast that inflation will remain at 6.09%.
An existing fixed deposit’s contractual rate does not automatically change because inflation rises. Rates on new deposits and renewals are set by providers and can differ.
For another way to think about purchasing power, read Vantage’s earlier analysis: Inflation at 5.54%: Is a 7% Return Really Enough?
Four checks worth making now
1. Review your actual spending. Compare recent spending on essentials with your earlier budget. Focus on the categories that matter most to your household.
2. Check your loan documents. Find your current rate, benchmark, next reset date, outstanding tenure and the lender’s process for communicating changes.
3. Test your home-buying budget. If you are considering a purchase, estimate what would happen to your monthly surplus if essential expenses or the applicable loan rate increased. Keep the scenarios separate so you can see which one creates pressure.
4. Compare returns with your goal. Look at expected returns after applicable taxes and costs, and consider when you will need the money. A down-payment goal due soon may require a different decision from a long-term goal.
Frequently asked questions
Does 6.09% mean prices rose that much in October alone?
No. It compares the consumer price index in October 2026 with the index in October 2025.
Did every food item become 8.94% more expensive?
No. Food inflation is an aggregate. Price changes vary across products and locations.
Does inflation above 6% guarantee an RBI rate hike?
No. The RBI considers the wider inflation and growth outlook. The October data does not predetermine its next policy decision.
Will my home-loan EMI increase immediately?
Not because of the inflation reading alone. Any change depends on your loan terms, benchmark, lender and reset schedule.
Can my loan become more expensive even if my EMI stays the same?
Yes. If your rate rises and the lender extends your tenure instead of increasing the EMI, you may pay interest over a longer period.
Will my existing fixed-deposit rate change automatically?
Generally, an existing fixed deposit follows its agreed contractual rate. Check the terms of your particular deposit and any conditions that apply.
Does this inflation reading predict property prices?
No. Property prices depend on local supply and demand, financing conditions, income and other factors. National consumer inflation does not establish what a particular property will cost.
Sources
Click an article title to view the source.
- India October inflation tops RBI’s 6% limit, strengthens case for rate hikes, Reuters, 12 November 2026.
- Retail inflation at 6.09% in October, breaches RBI’s upper band after 2 yrs, Business Standard, 12 November 2026.
- A 25-Basis-Point RBI Hike Looks Small. For Housing Affordability, the Starting Point Matters, Vantage InSights, October 2026.
- Inflation at 5.54%: Is a 7% Return Really Enough?, Vantage InSights, October 2026.
Evidence caveats
October inflation figures in this article are based on the news reports linked above. The October government release was not independently retrieved for this draft.
The savings example is illustrative and excludes tax, fees and compounding. Individual spending patterns, loan contracts and future inflation will differ.
Which would affect your household more: rising essential expenses, a higher loan rate or lower purchasing power on savings? Share your experience in the discussion.
Disclaimer: This article is for general information and does not constitute investment, tax or financial advice. Review your circumstances and consult a qualified professional before making financial decisions.
From TatvaOps
Finance
Financing your project?
Explore credit and milestone-secured payment options with Tatva Finance.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
More from Real Estate
Bharat Future City Plot Checks Before Paying a Premium
How to check a Bharat Future City plot's planning record, road access and utilities before assigning value to proposed infrastructure.
Telangana House Pattas and What Families Should Check
How Telangana families can trace old house pattas, reconcile loan and allotment records and check collection instructions with their district office.
Amrapali Assets Could Be Auctioned. Will That Bring Your Home Closer?
Amrapali asset sales could help recover funds, but will that bring a waiting buyer closer to possession? Here are the steps between a proposed auction, project funding and a completed home.
Inline Intelligence
Key Insight Actions
Connected knowledge for Personal Finance
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Home Loan EMI: What Does a Smaller Payment Cost?
3 replies
Related discussionThe Fed Paused. Should Indian Investors Change Their Plans?
1 replies
Related discussionYour Savings Have Not Fallen. Why Does the Overseas Goal Cost More?
5 replies
Related discussionInflation at 5.54: Is a 7 Return Really Enough?
1 replies
Related discussion
Topic hubs
Conclusion Intelligence
Related Discussions
Home Loan EMI: What Does a Smaller Payment Cost?
Popular in insights discussions3 replies
The Fed Paused. Should Indian Investors Change Their Plans?
Popular in insights discussions1 reply
Your Savings Have Not Fallen. Why Does the Overseas Goal Cost More?
Popular in insights discussions5 replies
Inflation at 5.54: Is a 7 Return Really Enough?
Popular in insights discussions1 reply
Was this helpful?
Let us know what you think