

Shapoorji Pallonji Shelves Real Estate IPO for Now as 55,000 Crore Debt Challenge Shifts Focus to Tata Sons Stake
Karthik posts articles on Energy and Construction.
Summary
The Shapoorji Pallonji Group has put plans for an initial public offering of its real estate business on the back burner, removing for now one potential route for raising capital and reducing the conglomerate's debt. Moneycontrol reported on 5 October that there is currently no active work underway on the proposed Shapoorji Pallonji Real Estate IPO. The decision is significant because a listing of Shapoorji Pallonji Real Estate, or SPRE, had been considered one possible avenue for raising capital as the wider SP Group manages debt estimated at more than ₹55,000 crore .
Published on
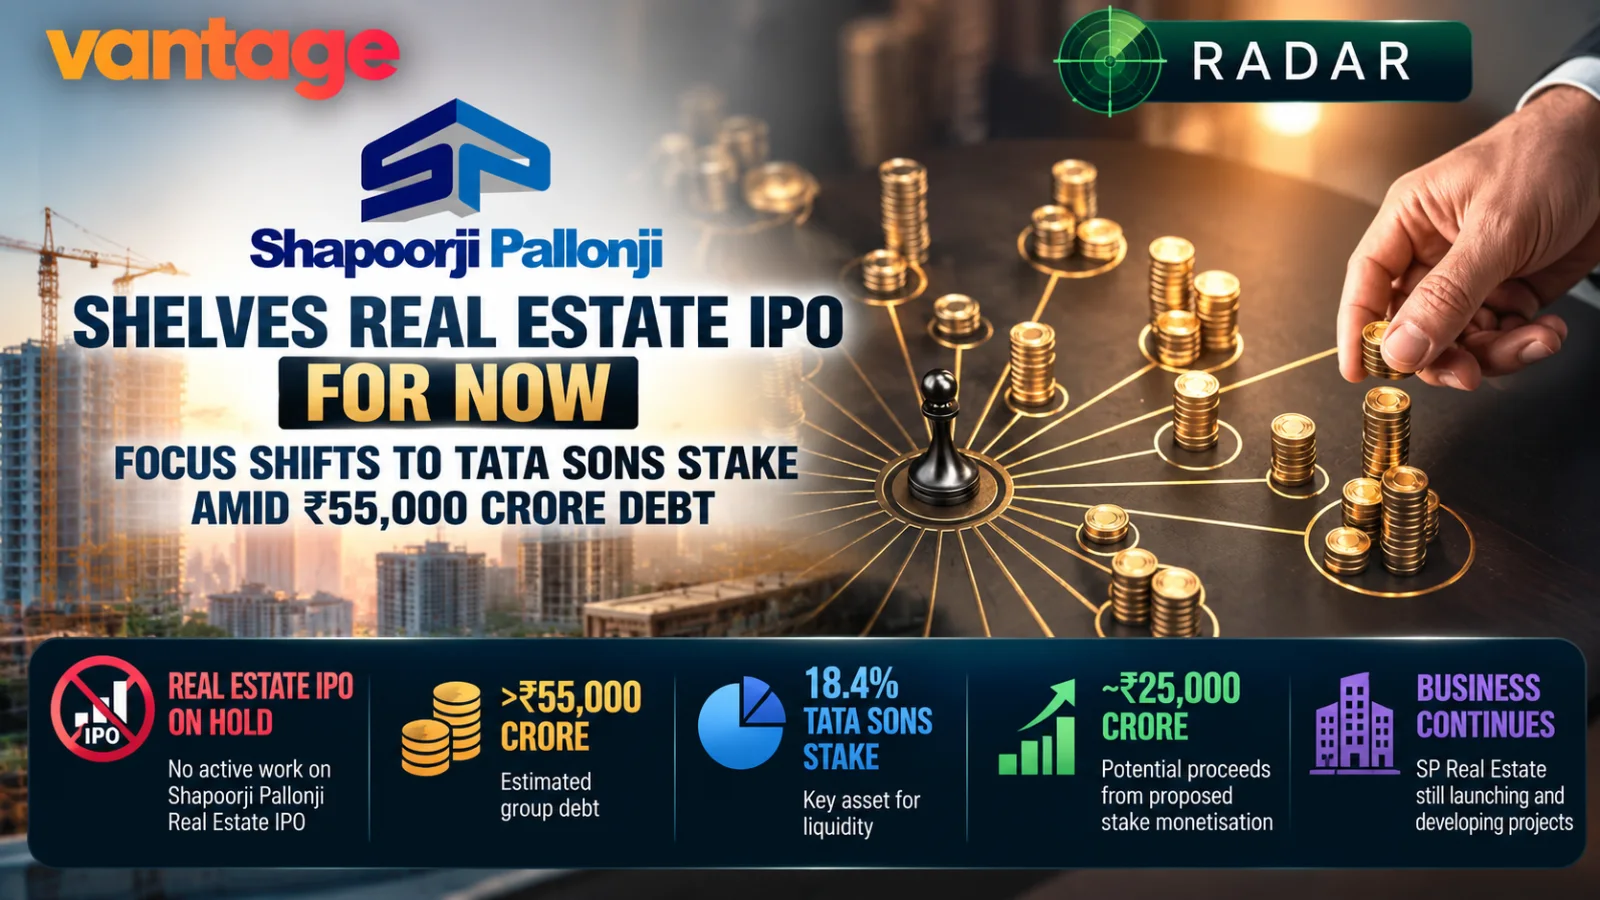
banner showing Shapoorji Pallonji branding against an Indian real estate construction backdrop, with an investor evaluating competing capital strategies. The visual frames the group's estimated debt burden, the shelved real estate IPO, its 18.4% Tata Sons stake and the strategic question of whether potential stake monetisation can provide meaningful liquidity and support deleveraging.
Inline Intelligence
The Shapoorji Pallonji Group has put plans for an initial public offering of its real estate business on the back burner, removing for now one potential route for raising capital and reducing the conglomerate's debt.
Moneycontrol reported on 5 October that there is currently no active work underway on the proposed Shapoorji Pallonji Real Estate IPO.
The decision is significant because a listing of Shapoorji Pallonji Real Estate, or SPRE, had been considered one possible avenue for raising capital as the wider SP Group manages debt estimated at more than ₹55,000 crore.
But the IPO should not be described as permanently cancelled.
The evidence supports a narrower conclusion:
SP Group has shelved the SPRE listing plan for now while exploring other ways to unlock capital.
Attention has increasingly shifted towards the group's 18.4% stake in Tata Sons, potentially a much larger source of liquidity.
What Happened to the Shapoorji Pallonji Real Estate IPO?
Earlier in 2026, SP Group had been working towards a potential listing of its real estate business.
Moneycontrol reported in January that the group had selected six investment banks to begin work on the proposed IPO.
That process is no longer active.
An investment banker familiar with the plans told Moneycontrol that there is currently no active work happening on the IPO.
No new listing timetable was reported.
This means investors should distinguish between:
an IPO being considered,
an IPO process being actively prepared,
and
an IPO actually reaching regulatory filing and execution.
The SPRE proposal has moved backwards along that sequence.
Why Did the SPRE IPO Matter?
An IPO could potentially have served several purposes.
It could have:
- raised capital;
- established a public-market valuation for SPRE;
- created listed equity that could potentially support future fundraising;
- broadened the real estate company's shareholder base; and
- helped the wider group address debt.
The debt angle made the proposed listing particularly important.
Moneycontrol estimates SP Group's debt at more than ₹55,000 crore.
The SPRE IPO had therefore been viewed partly through the group's wider balance-sheet strategy rather than only as a conventional real estate listing.
₹55,000 Crore Is Group Debt, Not SPRE Debt
This distinction is essential.
The more than ₹55,000 crore figure cited by Moneycontrol refers to the wider Shapoorji Pallonji Group's estimated debt.
It should not be presented as the standalone debt of Shapoorji Pallonji Real Estate.
The reviewed evidence does not provide a current standalone SPRE debt figure that can be directly compared with the group's total debt estimate.
Why Is the Tata Sons Stake Now More Important?
SP Group owns approximately 18.4% of Tata Sons, making the Mistry family the holding company's largest minority shareholder.
That stake has become central to the group's attempts to unlock liquidity.
A proposal placed before the Tata Sons board in September involved a selective capital reduction under which Tata Sons could acquire around 3% of the stake held through Mistry family entities.
Moneycontrol reported that such a transaction could generate gross proceeds of approximately ₹25,000 crore.
That is a proposal, not completed liquidity.
₹25,000 Crore Would Be Large Relative to the Debt Estimate
Comparing the reported figures provides a sense of scale.
₹25,000 crore divided by ₹55,000 crore equals approximately 45.5%.
This is a Vantage-derived calculation.
It does not mean the transaction would reduce group debt by 45.5%.
The ₹25,000 crore figure represents potential gross proceeds from the proposed transaction.
Taxes, transaction structure, use of proceeds, refinancing decisions and other obligations could materially change the amount ultimately available for debt reduction.
The comparison simply shows why the Tata Sons stake is strategically important to SP Group.
The Tata Sons Route Is Not Simple
The proposed capital reduction is not a completed transaction.
Moneycontrol reported that monetisation of the Tata Sons stake could be a lengthy process.
Several issues remain unresolved.
These include the structure of any transaction, regulatory considerations and disagreements around the future of Tata Sons.
A potential Tata Sons listing has also been part of the broader debate.
That could create another route for SP Group to unlock value from its holding.
But neither the timing nor the final structure can currently be treated as certain.
SP Group Has Already Been Refinancing Debt
The group has undertaken substantial financing activity during 2026.
In July, Business Standard reported that SP Group completed approximately ₹15,100 crore of private-credit financing to refinance debt.
More recently, Moneycontrol reported that the group repaid ₹3,500 crore to bondholders after securing fresh loans from existing lenders.
The Economic Times also reported plans to raise $125 million through a tap issue of existing dollar bonds and ₹3,250 crore through rupee-denominated bonds for refinancing.
These transactions show that SP Group's capital strategy extends well beyond the proposed SPRE IPO.
Refinancing Is Different From Deleveraging
This distinction matters when evaluating the group's financial strategy.
Refinancing replaces or restructures existing borrowing.
Deleveraging reduces the amount of debt outstanding.
A new bond or private-credit facility can address maturities and liquidity without necessarily reducing overall indebtedness.
Monetising an equity asset and using the proceeds to repay borrowings could have a more direct deleveraging effect.
That is why the Tata Sons stake remains strategically significant.
Does Shelving the IPO Hurt Shapoorji Pallonji Real Estate?
Not necessarily at an operating level.
SPRE continues to develop and launch projects.
The company has a portfolio spanning residential and commercial real estate, including platforms such as Joyville and redevelopment-focused SD Corp.
Business Standard has reported SPRE launches during 2026 in markets including Mumbai and Pune.
The IPO decision therefore concerns ownership and capital strategy rather than evidence that the operating real estate business has stopped expanding.
But the IPO Would Have Created Another Funding Channel
Public equity markets can provide developers with access to a different form of capital.
Unlike debt, equity does not create scheduled interest and principal repayment obligations.
A listed company can also potentially return to capital markets later, subject to market conditions and shareholder approval.
By shelving the IPO, SPRE does not currently gain that additional listed-equity channel.
The wider group must therefore continue relying on other financing and asset-monetisation options.
Why Might a Group Delay an IPO?
The reviewed evidence does not establish a single reason for SP Group's decision.
It would therefore be inappropriate to attribute the move to IPO-market weakness, valuation concerns or poor investor demand without supporting evidence.
Possible strategic considerations exist, but they remain speculation unless confirmed.
What is observable is that SP Group is simultaneously pursuing other liquidity options, particularly around Tata Sons.
The Tata Sons Stake Changes the Capital-Allocation Equation
SP Group's financial position is unusual because it combines substantial debt with ownership of a valuable but historically illiquid minority stake in Tata Sons.
This creates a liquidity problem rather than a simple asset-availability problem.
The group owns an asset that could potentially unlock significant capital.
But converting that stake into cash depends on transaction structure, counterparties, governance and regulatory developments.
The proposed ₹25,000 crore capital-reduction route illustrates the scale of the opportunity.
It also illustrates the complexity.
What Does This Mean for SPRE Homebuyers?
For homebuyers, the most relevant questions remain at the project level.
They include:
- RERA registration;
- construction progress;
- escrow compliance;
- possession timelines;
- approvals;
- project-specific financing; and
- developer disclosures.
A parent group's financing strategy should be monitored, but it should not automatically be treated as evidence of a problem at every individual project.
Similarly, shelving an IPO does not establish that SPRE projects face delivery problems.
No such conclusion is supported by the reviewed evidence.
What Should Credit Investors Watch?
For lenders and credit investors, several indicators are more relevant.
Tata Sons monetisation
Does the proposed capital reduction or another transaction actually occur?
Debt reduction
Do asset-monetisation proceeds translate into lower group debt?
Refinancing costs
Can SP Group reduce the cost of its borrowing?
Maturity extension
Does refinancing provide enough time for larger asset-monetisation transactions?
SPRE cash generation
How much cash can the real estate business generate independently?
These indicators will matter more than the IPO headline alone.
What Would Bring the SPRE IPO Back?
The current evidence does not provide a timetable.
A future revival could depend on several factors, including:
- group liquidity;
- debt reduction;
- SPRE operating performance;
- equity-market conditions;
- valuation expectations; and
- the outcome of Tata Sons monetisation discussions.
Until a formal process resumes, the SPRE IPO should be described as shelved for now.
The Bigger Story Is Capital Structure
At first glance, this is an IPO story.
At a deeper level, it is a capital-structure story.
SP Group has several potential routes for managing its financial obligations:
refinance debt,
monetise assets,
sell or reduce part of the Tata Sons stake,
raise equity,
or
combine several of these approaches.
The SPRE IPO represented one possible route.
It is currently not active.
That increases the importance of the alternatives.
What Happens Next?
The most important development to watch is not whether an SPRE draft prospectus suddenly appears.
It is whether SP Group can convert the value embedded in its assets into permanent debt reduction.
The proposed Tata Sons capital reduction could potentially generate around ₹25,000 crore of gross proceeds.
That is large relative to the group's reported debt estimate.
But it remains unresolved.
For now, SP Group has removed one capital-raising option from the immediate agenda while continuing to pursue refinancing and potential asset monetisation.
The central question is therefore no longer:
When will Shapoorji Pallonji Real Estate list?
It is:
Can SP Group materially reduce its debt without needing the real estate IPO?
Frequently Asked Questions
Is the Shapoorji Pallonji Real Estate IPO cancelled?
The available evidence says the IPO has been shelved or put on the back burner for now. It does not establish that the listing has been permanently cancelled.
How much debt does Shapoorji Pallonji Group have?
Moneycontrol estimates the wider SP Group's debt at more than ₹55,000 crore. This should not be confused with standalone SPRE debt.
Why was Shapoorji Pallonji Real Estate considering an IPO?
The proposed IPO was one potential way to raise capital and could have contributed to the wider group's debt-management strategy.
How much of Tata Sons does Shapoorji Pallonji Group own?
SP Group owns approximately 18.4% of Tata Sons through Mistry family entities.
Could SP Group receive ₹25,000 crore from Tata Sons?
A proposed selective capital reduction involving around 3% of SP Group's Tata Sons stake could generate approximately ₹25,000 crore of gross proceeds, according to Moneycontrol. The transaction has not been completed.
Would ₹25,000 crore eliminate SP Group's debt?
No. The group's debt is estimated at more than ₹55,000 crore, and gross transaction proceeds would not necessarily be used entirely for debt repayment.
Is Shapoorji Pallonji Real Estate still launching projects?
Yes. SPRE has continued launching and marketing real estate projects during 2026. Shelving the IPO does not mean the operating business has stopped.
Could the SPRE IPO return later?
Yes, but the reviewed evidence provides no timetable or assurance that the IPO process will restart.
Sources
Click on article title to view article.
“Shapoorji Pallonji Group shelves plans to list real estate arm” published on 5 October 2026 in Moneycontrol
“SP Group renews push to monetise Tata Sons stake before listing, seeks relief from costly debt” published on 1 October 2026 in Moneycontrol
“Shapoorji Pallonji Group closes one of India's biggest private credit deals” published on 20 July 2026 in Business Standard
Evidence Caveats
- The SPRE IPO is shelved for now, not verified as permanently cancelled.
- More than ₹55,000 crore is an estimate of wider SP Group debt, not standalone SPRE debt.
- Approximately ₹25,000 crore represents potential gross proceeds from a proposed Tata Sons transaction, not completed cash proceeds.
- The approximately 45.5% comparison is a Vantage-derived scale indicator, not a forecast of debt reduction.
- Refinancing should not be treated as equivalent to deleveraging.
- The reviewed evidence does not establish that shelving the IPO has affected SPRE project execution.
- Standalone SPRE debt, current valuation, IPO valuation, project-level cash flows and the amount of future Tata Sons proceeds available for debt repayment are unavailable.

From TatvaOps
Residential Construction
Need a reliable project estimate?
Structured costing and BOQ support before you commit budget.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this Radar article is filed under Radar.
More from Real Estate
LTCG and STT: Review Reports Do Not Mean a Tax Cut
Finance Minister Nirmala Sitharaman’s comments on equity taxation have reopened a consequential debate for investors. Speaking at the Bloomberg New Economy Forum in New Delhi on 13 October, she welcomed views on long term capital gains tax and securities transaction tax without committing to…
Blackstone Targets 100 Billion in India Investments
Blackstone aims to double its India investments to approximately $100 billion over about five years, president and chief operating officer Jonathan Gray said in interviews reported this week. The ambition spans private equity and real estate, alongside potential expansion in infrastructure, credit…
Property Registrations Flagged Over Fictitious PAN
Nearly 25,000 property registrations over two years at Badshahpur tehsil in Gurugram reportedly carried the same fictitious PAN, according to The Times of India’s 9 October report on an Income Tax Department survey. The finding raises questions about taxpayer identification and transaction…
Inline Intelligence
Key Insight Actions
Connected knowledge for Financial Updates
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Topic hubs
Conclusion Intelligence
Related Discussions
Was this helpful?
Let us know what you think