
Cyclone Arnab: Who Pays When Coastal Homes Flood?
Summary
Before you commit to a number, when a cyclone approaches, the first priority is protecting lives — worth a full read? When a cyclone approaches, the first priority is protecting lives. But after the winds weaken and floodwater recedes, another difficult question emerges. Who pays to repair the damaged home? Is the loss covered by insurance, absorbed by the homeowner, financed through borrowing or partly supported by disaster relief? Cyclone Arnab's arrival on India's east coast on 28 October 2026 puts that question into focus for coastal homeowners, property investors and businesses.
Published on
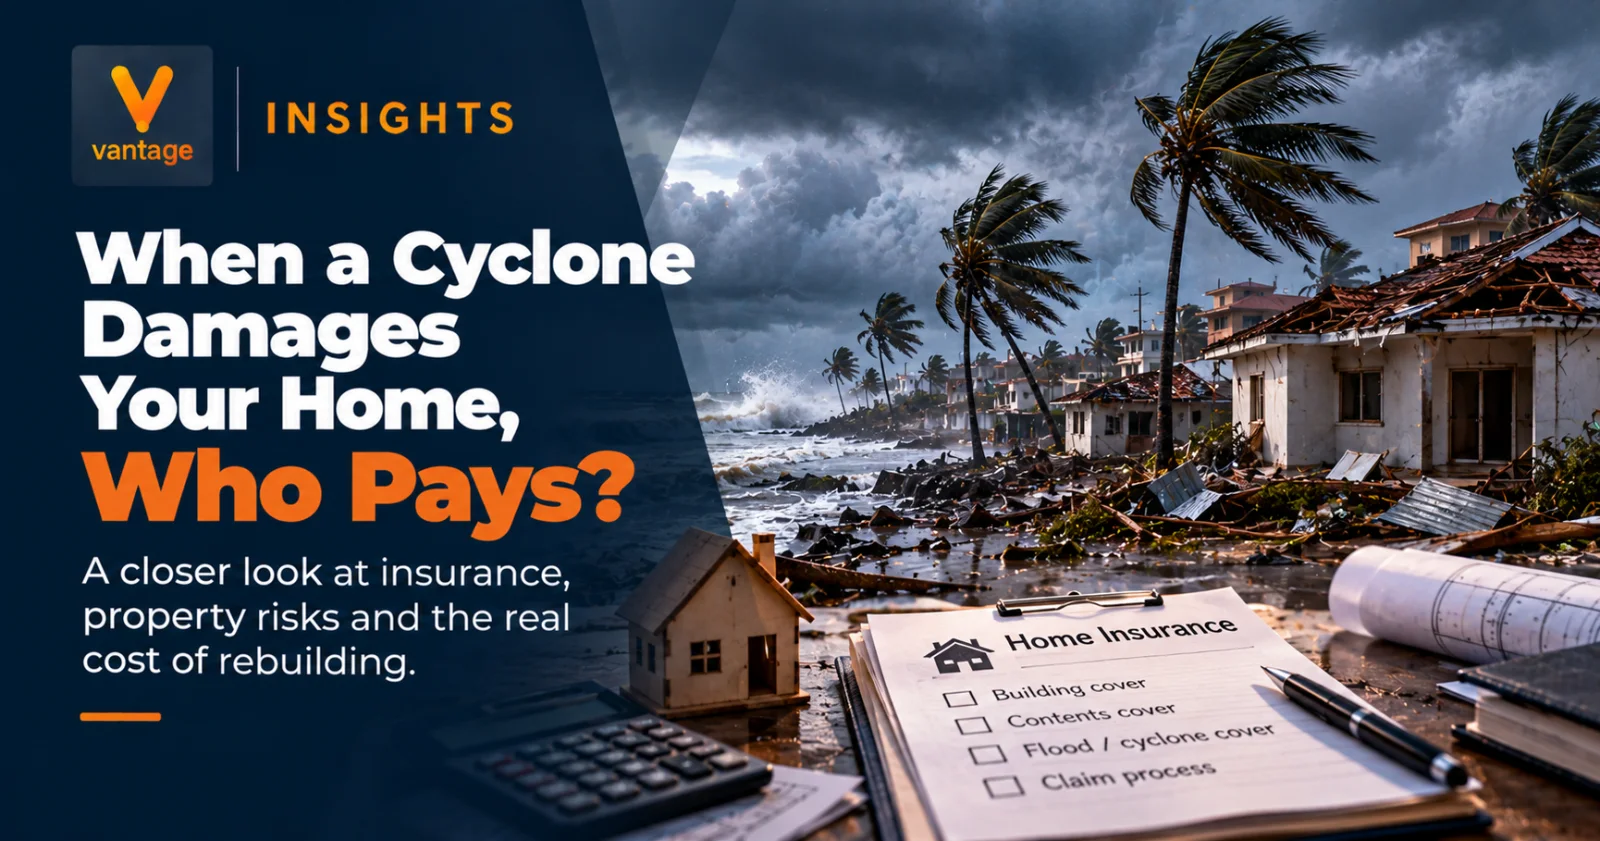
Cyclone damage to coastal homes in India raises questions about home insurance coverage, property repairs and rebuilding expenses. Explore who bears the financial losses after severe storms, what cyclone and flood insurance may cover, and how homeowners can protect their property.
Inline Intelligence
When a cyclone approaches, the first priority is protecting lives.
But after the winds weaken and floodwater recedes, another difficult question emerges.
Who pays to repair the damaged home?
Is the loss covered by insurance, absorbed by the homeowner, financed through borrowing or partly supported by disaster relief?
Cyclone Arnab's arrival on India's east coast on 28 October 2026 puts that question into focus for coastal homeowners, property investors and businesses.
The event also highlights a frequently overlooked distinction: owning a valuable property does not mean being financially protected against its destruction.
What Happened During Cyclone Arnab?
Cyclone Arnab approached Andhra Pradesh as a very severe cyclonic storm.
The India Meteorological Department's morning bulletin on 28 October placed the storm close to the coast near Narsapur and Yanam.
IMD forecast sustained winds of 115–125 km/h, with gusts reaching 140 km/h, during the landfall period.
Reuters reported evacuations of more than 180,000 people across Andhra Pradesh and Odisha.
The cyclone disrupted power supplies, damaged homes, uprooted trees and interrupted transport services.
Authorities also warned of a possible 1–1.5 metre storm surge above normal tide in vulnerable coastal areas.
These early reports establish serious exposure, but they do not establish a final economic loss figure.
Damage assessments can take time, especially where access is restricted, communications fail or flooding persists.
Why Is Coastal Property Particularly Vulnerable?
A cyclone can affect a building through several mechanisms.
Wind damage
Strong winds may dislodge roofing materials, damage doors and windows, and create dangerous flying debris.
Poor connections between structural elements can increase vulnerability.
Storm surge
Storm surge is seawater pushed above its usual level by storm conditions.
Low-lying coastal neighbourhoods can experience flooding even where ordinary rainfall alone would not create the same level of inundation.
Heavy rainfall and drainage failure
Intense rain can overwhelm drainage networks, enter ground-floor spaces and affect electrical installations.
A property's distance from the shoreline does not establish that it is free from flood risk.
Infrastructure disruption
Electricity networks, roads, drinking-water systems and communication services can be damaged.
A structurally intact building may still become temporarily difficult to occupy.
The overall risk depends on elevation, local topography, drainage, surrounding infrastructure, construction quality and the storm's path.
Why Can a Cyclone Become a Household Financial Crisis?
A house is both a place to live and, for many families, a major financial asset.
Damage creates more than a repair bill.
A household may face simultaneous expenses for:
- Emergency accommodation
- Structural inspections and repairs
- Replacement of furniture and appliances
- Electrical-system restoration
- Cleaning and drying
- Business or rental-income interruption
- Existing housing-loan repayments
Consider a hypothetical household with the following expenses after flood damage.
| Expense | Illustrative amount |
|---|---|
| Building and electrical repairs | ₹2,00,000 |
| Furniture and appliance replacement | ₹75,000 |
| Temporary accommodation | ₹45,000 |
| Cleaning and related expenses | ₹30,000 |
| Total cash requirement | ₹3,50,000 |
These are invented scenario figures for explaining financial exposure, not estimates of losses from Cyclone Arnab.
Some expenses may be recoverable under applicable insurance coverage. Others may be excluded or subject to policy limits.
The household's eventual out-of-pocket cost therefore depends on both the damage and its financial protection.
Does Home Insurance Cover Cyclone Damage in India?
Some home insurance products cover specified natural catastrophes, including storm, cyclone and flood-related damage.
However, the exact protection depends on the policy.
A homeowner should not assume that all losses are automatically covered simply because the policy is described as home insurance.
Important distinctions include:
Building cover: Protection for the insured physical structure, subject to the terms, valuation basis and exclusions.
Contents cover: Protection for eligible belongings, which may need to be insured separately or selected as an additional component.
Additional living expenses: Some products may provide limited support for temporary accommodation or related expenses. This should never be assumed without checking the wording.
Business or rental-income losses: These may require specific cover and may not be included in a standard household policy.
The sum insured, deductibles, exclusions and policy conditions influence the final claim.
For apartment owners, it is also important to establish whether the housing association or another entity maintains building insurance, what that insurance covers and whether individual contents remain uninsured.
An insurance policy's existence does not establish that a particular claim will be accepted.
What Should Property Owners Check in Their Insurance Policy?
Five questions can reveal important gaps.
1. Is the building insured against cyclone and flood damage?
Look for the covered perils and relevant exclusions.
The answer should come from the actual policy schedule and wording rather than a general marketing description.
2. Are household contents included?
Building insurance and contents insurance are different.
A policy that covers the structure may not automatically cover furniture, electronics or other belongings.
3. Is the sum insured adequate?
An inadequate sum insured may leave the homeowner exposed to substantial rebuilding or repair costs.
The correct valuation approach depends on the product.
4. Are there deductibles or special conditions?
Some policies require the policyholder to bear part of a loss or comply with specific conditions.
5. How must a claim be reported?
The reporting process, required information and applicable deadlines should be checked directly with the insurer.
Policyholders should not assume that rules applied during another cyclone automatically apply to Arnab.
What Should Homeowners Do After Damage?
Personal safety comes first.
Do not enter a visibly unstable building, reconnect flood-affected electrical equipment or approach fallen power lines without appropriate clearance.
Once authorities consider the area safe, the following steps can help organise recovery.
Document the damage. Photograph affected walls, roofing, contents and visible water levels where safe.
Notify the insurer promptly. Use the company's official claim channels and retain the claim reference.
Preserve relevant records. Keep policy documents, purchase invoices, repair quotations and receipts where available.
Avoid unsafe or unnecessary demolition. Emergency measures may be required to prevent further loss, but significant repairs should be coordinated with qualified professionals and the insurer where appropriate.
Request written explanations. If a claim is reduced or rejected, ask for the policy provision and assessment supporting the decision.
During earlier disasters, India's insurance regulator instructed insurers to mobilise resources for cyclone-related claims.
For example, IRDAI issued claims-response directions following Cyclone Remal in June 2024.
That historical precedent illustrates the importance of organised claims handling. It does not prove that an identical special direction has been issued for Cyclone Arnab.
What Happens When There Is No Insurance?
An uninsured homeowner may have to finance repairs through savings, family support, borrowing, assistance programmes or other resources.
This can create a difficult financial trade-off.
Money originally intended for education, retirement, medical expenses or debt repayment may be redirected toward rebuilding.
Some affected households may qualify for government assistance, depending on applicable schemes, damage assessments and eligibility rules.
But government disaster assistance should not be assumed to replace the complete value of damaged property.
Relief and insurance are distinct systems with different purposes and conditions.
For households already carrying substantial debt, the combination of repairs and interrupted income can create additional financial vulnerability.
Does Cyclone Risk Reduce Coastal Property Values?
It can, but there is no simple universal formula.
A property's market value reflects many factors, including location, employment opportunities, infrastructure, amenities, supply and demand.
Repeated flooding, poor drainage or high insurance expenses may make a property less attractive to some buyers.
Conversely, locations with stronger flood protection, reliable infrastructure and better building standards may retain advantages.
One severe weather event does not establish how far a specific property's market value will change.
A reliable assessment requires local transaction evidence, physical risk information and comparable properties.
This matters for buyers considering coastal apartments, independent houses, holiday homes and commercial assets.
A low purchase price is not necessarily attractive if future ownership involves substantial physical or financial risk.
What Should Buyers Investigate Before Purchasing Coastal Property?
Alongside title, approvals and price, buyers should examine the property's exposure to extreme weather.
Relevant checks include:
- Flood and storm history: Have the property or surrounding roads experienced repeated inundation?
- Site elevation and drainage: How does the plot sit relative to surrounding land, water bodies and drainage routes?
- Construction quality: Are the structure, roof connections, openings and electrical installations appropriate for the location?
- Insurance availability: Can suitable protection be obtained, and on what terms?
- Emergency access: Are there safe evacuation routes and accessible shelters?
- Infrastructure resilience: How frequently are power, water and transport services interrupted during severe weather?
Independent engineering assessment may be appropriate for high-value or high-exposure purchases.
Buyers should distinguish a property's appearance and advertised features from its actual vulnerability.
What About Rental and Commercial Property Investors?
For investors, cyclone exposure can affect returns in ways not visible in headline rental yields.
Potential financial consequences include:
- Higher maintenance and repair expenditure
- Insurance premiums and deductibles
- Longer vacancy periods after damage
- Business interruptions affecting tenants
- Temporary loss of rental income
- Reduced resale liquidity in highly exposed locations
A property yielding attractive rent in normal conditions may deliver lower net returns after accounting for uninsured damage and downtime.
Investors should therefore distinguish gross rental yield from income remaining after realistic costs and risks.
Climate exposure should be considered alongside financing, taxation, market demand and property condition.
Can Better Building Design Reduce Cyclone Damage?
Appropriate construction and maintenance can improve resilience, although no design can eliminate all risk.
Important measures may include properly engineered roof connections, secure openings, suitable drainage, elevated placement of vulnerable electrical systems and safe storage of essential equipment.
The correct solutions depend on the site, local building regulations, expected hazards and professional engineering assessment.
Flood barriers, drainage changes and structural modifications should not be implemented without considering potential effects on neighbouring properties and the wider drainage system.
A useful principle is to evaluate resilience before construction or purchase, rather than treating it only as a repair problem after a disaster.
The Bigger Lesson From Cyclone Arnab
Cyclone Arnab is first and foremost an emergency affecting people's safety and livelihoods.
Its longer-term financial lesson concerns the difference between asset ownership and asset protection.
A home may represent years of savings.
But its financial security depends partly on construction quality, hazard exposure, insurance and the household's ability to manage unexpected expenses.
For homeowners, the practical objective is not to predict every future cyclone.
It is to understand which losses they could absorb, which risks may be insured and which vulnerabilities could be reduced before another severe event.
For property investors, the question is equally important.
The value of a property should be considered alongside the cost of keeping it safe, functional and insurable.
FAQ
1. When did Cyclone Arnab reach Andhra Pradesh?
Cyclone Arnab made landfall along the Andhra Pradesh coast on 28 October 2026. IMD bulletins documented the storm's position and intensity during the landfall period.
2. How many people were evacuated?
Reuters reported more than 180,000 evacuations across Andhra Pradesh and Odisha as of 28 October. Numbers may change as authorities update their assessments.
3. Can cyclone damage be covered by home insurance?
Yes, certain Indian home insurance policies cover specified cyclone, storm and flood damage. The extent of coverage depends on the particular policy.
4. Does building insurance cover furniture?
Not necessarily. Buildings and contents may require different coverage selections.
5. Will insurance pay the full cost of rebuilding?
Not automatically. The claim depends on insured value, covered losses, deductibles, exclusions and other policy terms.
6. What should homeowners do immediately after a cyclone?
Follow official safety instructions, avoid unsafe buildings and electrical hazards, document damage when safe, and contact the insurer using official channels.
7. Does a cyclone automatically reduce property prices?
No. Its effects depend on actual damage, recurring risk, infrastructure, market conditions and buyer preferences.
8. Can property buyers assess flood risk before purchase?
Buyers can review local flood history, drainage, site elevation, building condition, insurance options and official hazard information. Specialist assessment may be necessary.
Sources
Click an article title to view the source.
- India Evacuates Over 180,000 as Cyclone Arnab Hits Coast updated on 28 October 2026 by Reuters.
- Cyclone Arnab Hits India's Andhra Pradesh State as Tens of Thousands Evacuate published on 28 October 2026 by Associated Press.
- IMD Sea Area Bulletin, 28 October 2026 issued on 28 October 2026 by the India Meteorological Department.
- Government Reviews Preparedness for Cyclone Arnab published on 26 October 2026 by the Press Information Bureau.
- IRDAI Claims Directions Following Cyclone Remal dated 4 June 2024, reproducing an IRDAI circular.
Evidence Caveats
This analysis uses storm information available on 28 October 2026. Subsequent official updates may revise reported conditions, damage or evacuation figures.
No complete verified monetary estimate of Arnab-related residential property damage or insured losses was available in the reviewed material.
The hypothetical ₹3.5 lakh household expense example is not based on an actual cyclone claim or loss assessment.
Insurance availability, coverage, exclusions, claim procedures and payment amounts depend on the relevant policy and insurer. Historical IRDAI measures for other cyclones do not establish Arnab-specific relief or claim rules.
The discussion of property values and investment returns is analytical, not a claim that a quantified property-price change has already occurred.
What is the biggest gap in coastal property protection: building quality, flood planning, insurance or awareness? Share practical experiences, local evidence and different perspectives in the Vantage community. Please prioritise safety and recovery before contributing.
Disclaimer
This article is for general educational and informational purposes. It does not constitute personalised insurance, financial, legal, engineering or investment advice. Follow official emergency instructions and consult qualified insurers, engineers and other professionals for decisions concerning damaged or vulnerable property.
From TatvaOps
Home Maintenance & Appliance Care
Financing your project?
Explore credit and milestone-secured payment options with Tatva Finance.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
2 replies already on Forums
More from Real Estate
Mumbai Luxury Home Data What Buyers Should Check
Luxury registration totals are not a like-for-like price index. Here is how buyers can compare properties and ownership costs.
Binance Security Incident What Holders Can Check
The Binance incident highlights the difference between a displayed balance and access to assets. Here are practical checks for holders.
Gurugram Power Choice What Residents Should Check
A proposed second electricity distributor is on hold. Here is what Gurugram and Nuh residents can check on bills and service.
Inline Intelligence
Key Insight Actions
Connected knowledge for Disaster Risk & Insurance
Move between tutorials, discussions, Studio, and hubs without losing context.
Conclusion Intelligence
Was this helpful?
Let us know what you think