

Anarock Profit Rose 53, but Cash Flow Turned Negative: What Should IPO Investors Trust More?
Karthik posts articles on Energy and Construction.
Summary
Anarock's FY26 profit rose 53.4% to ₹93.22 crore, but operating cash flow swung to a ₹12.07 crore outflow as trade receivables climbed to ₹464.21 crore. Ahead of its proposed ₹1,000 crore IPO, the key investor question is whether rapid earnings growth can translate into stronger cash generation whil Anarock Property Consultants is approaching the public market with an attractive earnings growth story. FY26 revenue increased 33.8% to ₹881.90 crore . Profit increased 53.4% to ₹93.22 crore . Yet operating cash flow moved from approximately ₹93 crore positive in FY25 to ₹12.07 crore negative in FY26 .
Published on
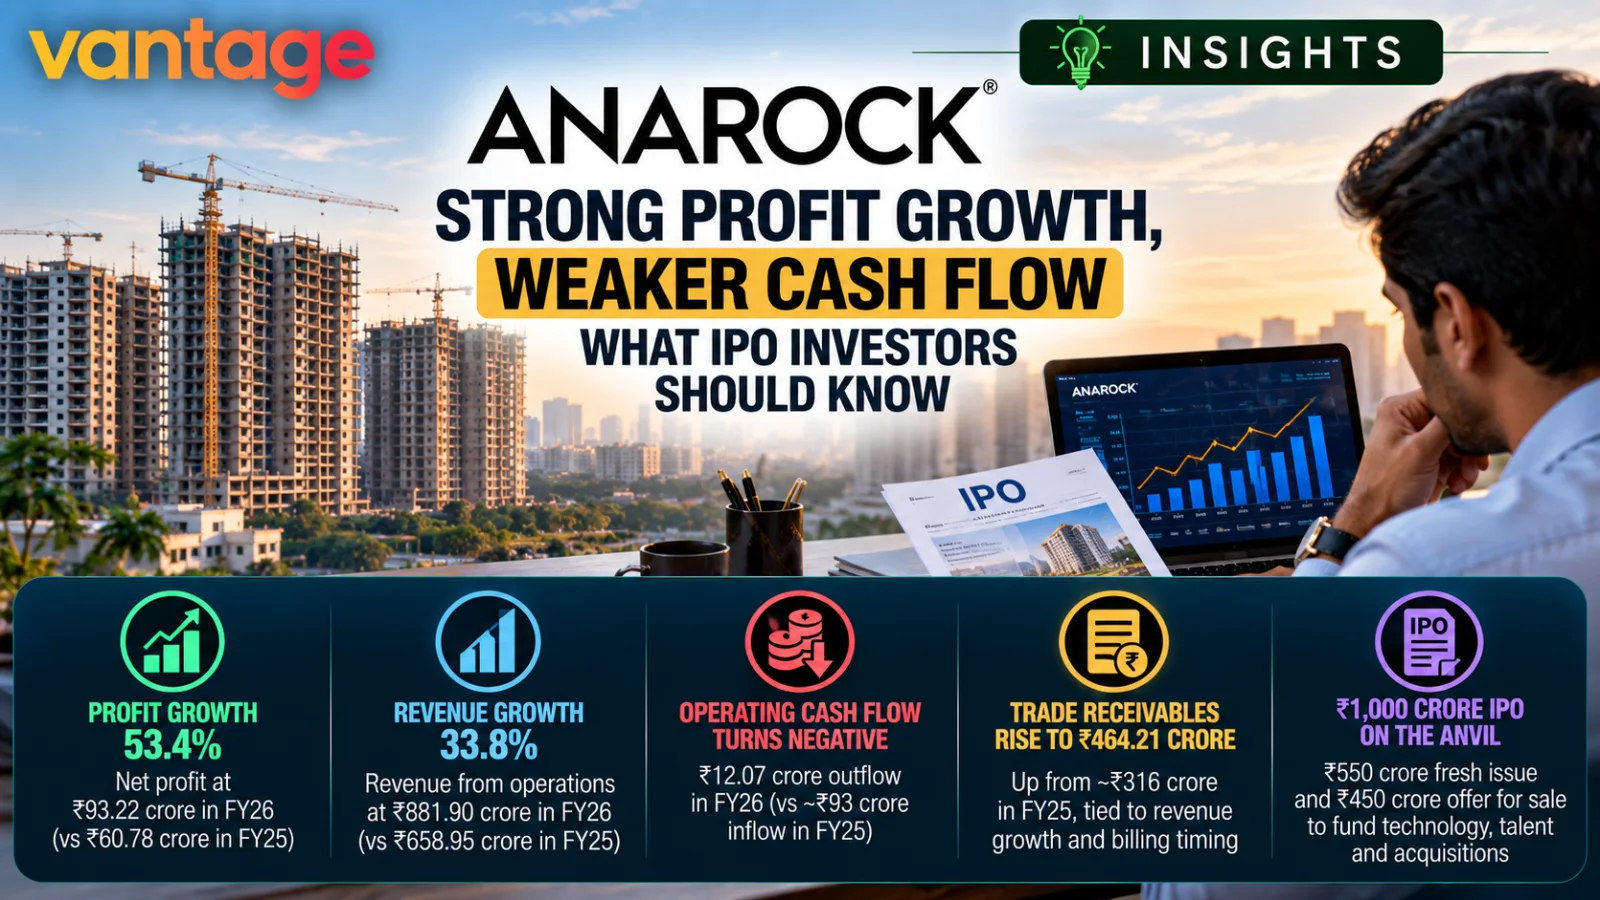
InSights editorial banner showing an investor reviewing Anarock IPO and financial data against an Indian residential construction backdrop. The visual contrasts Anarock's strong FY26 profit and revenue growth with negative operating cash flow and higher trade receivables, framing the key question for prospective IPO investors around earnings quality, cash conversion and deployment of fresh capital.
Inline Intelligence
Anarock Property Consultants is approaching the public market with an attractive earnings-growth story.
FY26 revenue increased 33.8% to ₹881.90 crore.
Profit increased 53.4% to ₹93.22 crore.
Yet operating cash flow moved from approximately ₹93 crore positive in FY25 to ₹12.07 crore negative in FY26.
Trade receivables simultaneously increased to ₹464.21 crore.
That creates one of the most useful questions an IPO investor can ask:
When profit and cash flow point in different directions, which one deserves more attention?
The answer is not one or the other.
Investors need to understand why they diverged and whether that divergence is temporary.
Profit Measures Economics Differently From Cash Flow
Accounting profit attempts to measure revenue earned and expenses incurred during a period.
Cash flow measures money actually moving through the business.
Those timelines frequently differ.
A consultancy can complete work and recognise revenue before the customer pays.
The unpaid amount becomes a trade receivable.
The company records revenue and potentially profit.
But it does not yet have the cash.
That appears central to Anarock's FY26 divergence.
Receivables Are the Core Metric
Trade receivables increased from approximately ₹316 crore to ₹464.21 crore.
That is an increase of approximately ₹148.21 crore.
For context, Anarock's FY26 net profit was ₹93.22 crore.
The increase in receivables was therefore approximately 1.6 times FY26 net profit.
This is a Vantage-derived scale comparison.
It does not mean ₹148 crore is uncollectible.
It illustrates how strongly working capital can influence cash generation even while reported profit rises.
Does This Mean Anarock Has a Collection Problem?
Not based on the available evidence.
Anarock said revenue growth and the timing of billing and revenue recognition contributed to the increase.
Revenue booked near the end of March has less time to turn into cash before the financial year closes.
That explanation is plausible.
The important test comes next.
If receivables convert into cash during FY27, the FY26 divergence may largely reflect timing.
If receivables continue increasing materially faster than revenue, investors may need to ask harder questions about collection cycles and working-capital intensity.
Cash Conversion Is a Trend, Not a One-Year Verdict
One negative operating cash-flow year should not be analysed in isolation.
Businesses can experience temporary working-capital swings.
What matters is whether cash generation follows earnings over a longer period.
For Anarock, investors should monitor:
profit growth,
receivables growth,
operating cash flow,
and
actual collection of prior-year receivables.
Those four numbers together will reveal much more than the FY26 profit figure alone.
No Outstanding Borrowings Changes the Risk
Anarock reportedly had no outstanding borrowings at FY26-end.
This is an important distinction.
A highly leveraged company with negative operating cash flow may need external capital simply to meet financing obligations.
Anarock's situation is different.
The current issue appears to be working-capital conversion rather than a disclosed debt-servicing problem.
That does not make cash flow irrelevant.
It changes the nature of the risk.
The IPO Adds ₹550 Crore of Potential Fresh Capital
Anarock's proposed IPO totals ₹1,000 crore.
But only up to ₹550 crore represents fresh issuance.
The remaining ₹450 crore is an OFS.
This means 45% of the proposed offer represents existing shareholders selling shares rather than capital entering Anarock.
There is nothing inherently unusual about an OFS.
But IPO investors should understand where their money goes.
Technology Is a Significant Use of Proceeds
Anarock plans to allocate approximately ₹120 crore towards AI and technology across certain businesses.
That represents approximately 21.8% of the proposed ₹550 crore fresh issue.
This is a Vantage-derived calculation.
Another ₹89.5 crore is intended for talent and specialised services.
₹148 crore is proposed for additional DSP Design equity.
Together, those three identified uses total ₹357.5 crore, approximately 65% of the maximum ₹550 crore fresh issue.
This is also a Vantage-derived calculation.
The remaining proceeds are intended for acquisitions, strategic initiatives and general corporate purposes.
DSP Makes the IPO Story More Complicated
Anarock acquired 53.68% of DSP Design shortly before filing its IPO papers.
DSP adds architecture, design, fit-out and project-management capabilities.
Strategically, that can broaden Anarock's relationship with corporate real estate clients.
Financially, however, DSP has lower profitability than Anarock.
DSP generated ₹241.97 crore of FY26 revenue and ₹6.86 crore of profit.
That implies a net profit margin of approximately 2.83%.
Anarock's reported FY26 margin was approximately 10.57%.
Scale Could Come With Margin Dilution
The DRHP's pro forma numbers illustrate the trade-off.
If DSP had been consolidated for all of FY26:
revenue would have increased to approximately ₹1,123.87 crore,
while net profit would have increased to approximately ₹100.07 crore.
That means revenue would have been around 27% higher than Anarock's reported number, while profit would have been only around 7% higher.
The combined net margin would have fallen to approximately 8.9%.
This does not mean the acquisition destroys value.
It means the strategic case depends on more than adding revenue.
Anarock needs integration, cross-selling, operating leverage or improved DSP profitability to make the combination more valuable over time.
DSP Also Had Negative Operating Cash Flow
DSP reported a ₹1.61 crore operating cash outflow in FY26.
A year earlier it generated approximately ₹11.95 crore of positive operating cash flow.
That means Anarock is acquiring a business that also experienced negative operating cash conversion during FY26.
Again, one year does not establish a structural problem.
But it makes working-capital management more relevant after consolidation.
The IPO Is Funding Growth, Not Debt Repayment
This is another important feature.
Because Anarock reportedly had no outstanding borrowings at FY26-end, the proposed fresh issue is not primarily a debt-repayment IPO.
Capital is being directed towards:
technology,
talent,
DSP,
future acquisitions,
and general corporate purposes.
For investors, that shifts the evaluation.
The question is not whether IPO proceeds repair a leveraged balance sheet.
It is whether management can generate attractive returns on new growth capital.
The Valuation Will Ultimately Decide the Investment Case
Strong growth can justify a higher valuation.
Weak cash conversion can justify greater caution.
Acquisitions can create upside or execution risk.
But none of these tells investors whether the IPO is attractive without knowing the price.
The price band has not yet been established in the reviewed evidence.
Therefore, no conclusion about whether Anarock's IPO is cheap, expensive or fairly valued is currently supportable.
What Should Investors Measure After Listing?
If Anarock completes the IPO, several indicators will matter more than quarterly headlines.
Receivable days
How quickly are customers paying?
Operating cash flow
Does cash generation converge with reported earnings?
DSP margins
Does the acquired business become more profitable?
Return on IPO capital
Does spending on AI, technology and talent generate measurable returns?
Acquisition discipline
Does Anarock buy businesses that improve long-term economics rather than simply increasing revenue?
Margin progression
Does diversification improve or dilute group profitability?
What Would Strengthen the IPO Story?
The case becomes stronger if Anarock demonstrates:
- continued double-digit revenue growth;
- stable or improving profit margins;
- receivables converting into cash;
- positive operating cash flow;
- successful DSP integration; and
- disciplined deployment of IPO proceeds.
What Would Weaken It?
Potential warning signs would include:
- receivables continuing to outpace revenue;
- repeated negative operating cash flow;
- deterioration in consolidated margins;
- weak returns from acquisitions;
- aggressive revenue growth without cash conversion; or
- an IPO valuation that assumes unusually optimistic future growth.
These are indicators to monitor, not findings about future performance.
Profit or Cash Flow?
Investors sometimes frame the question incorrectly.
Profit is not meaningless because cash flow is negative.
Cash flow is not irrelevant because profit is rising.
The two statements can simultaneously be true:
Anarock's FY26 earnings performance was strong.
And:
Anarock's FY26 cash conversion weakened materially.
The investment question lies in reconciling them.
If FY27 shows receivables being collected and operating cash flow recovering, FY26 may look like a temporary working-capital event during rapid growth.
If the divergence persists, investors may place greater weight on cash generation than headline profit growth.
That is why Anarock's next cash-flow statement could matter as much as its IPO valuation.
Frequently Asked Questions
Why can Anarock report profit while operating cash flow is negative?
Revenue can be recognised before customers pay. The resulting unpaid balances appear as trade receivables, allowing accounting profit and cash flow to diverge.
How much did Anarock's receivables increase?
Trade receivables increased by approximately ₹148.21 crore, from around ₹316 crore to ₹464.21 crore.
Are Anarock's receivables bad debt?
The reviewed evidence does not establish that. Anarock attributed the increase partly to revenue growth and billing timing.
Does Anarock have outstanding debt?
Business Standard reported no outstanding borrowings as of 31 March 2026.
How much fresh money will Anarock receive from the IPO?
The proposed fresh issue is up to ₹550 crore. The remaining ₹450 crore of the ₹1,000 crore IPO is an OFS.
Why is Anarock buying DSP Design?
The acquisition expands Anarock into architecture, design, corporate fit-outs and project-management services and is intended to support broader client offerings.
Will DSP reduce Anarock's profit margin?
FY26 pro forma data show a lower combined margin than Anarock's standalone reported margin. Future margins will depend on integration and business performance.
Is the Anarock IPO worth investing in?
The current evidence is insufficient to make that judgement. The eventual price band, valuation, FY27 cash conversion and investor-specific risk tolerance would need to be considered.
Sources
Click on article title to view article.
“IPO-bound Anarock’s FY26 operating cash flow turns negative despite 53% rise in profit” published on 5 October 2026 in Moneycontrol
“Anarock Property Consultants files DRHP to raise ₹1,000 cr via IPO” published on 1 October 2026 in Business Standard
Evidence Caveats
- Cash-flow interpretation is Vantage editorial analysis based on reported DRHP figures.
- Higher receivables do not by themselves establish weak collections or bad debt.
- Approximately ₹148.21 crore receivables growth, 1.6 times net-profit comparison, 21.8% technology allocation and 65% identified-use comparison are Vantage-derived indicators.
- Pro forma DSP figures are hypothetical combined FY26 figures rather than Anarock's reported financial results.
- DSP's future contribution, synergies and margins are unknown.
- The IPO price band and valuation are unavailable, so no investment-value conclusion is supportable.

From TatvaOps
Property Development
Developing a property?
Structured oversight for multi-unit and investor-led builds.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
1 reply already on Forums
More from Real Estate
LTCG Tax Debate: Should You Delay Selling Investments?
Could waiting for LTCG tax relief cost more than it saves? With proposals under discussion, we examine how your current tax liability, market exposure and cash deadline should shape a planned investment sale.
Blackstones India Bet: What Should You Check?
Blackstone’s $100-billion India ambition is a useful signal. For your own money, the harder questions are access, valuation, cash flow and risk. Here is what to check before turning institutional optimism into a personal investment decision.
Senior Living: Buy the Home, Examine the Services: what most readers overlook
Rustomjee’s senior-living evaluation raises a household question: can you afford and rely on the services after buying the home? We examine recurring charges, operator responsibilities, changing support needs and exit flexibility.
Inline Intelligence
Key Insight Actions
Connected knowledge for IPO & Financial Analysis
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Topic hubs
Conclusion Intelligence
Related Discussions
Blackstones India Bet: What Should You Check?
Popular in insights discussions1 reply
Gaurs Sold 1,088 Yamuna Expressway Homes for 1,800 Crore: Is Airport-Led Housing Demand Becoming Sustainable?
Popular in insights discussions1 reply
GST ITC Relief: Can Property Investors Count on Savings?
Popular in insights discussions1 reply
Was this helpful?
Let us know what you think