
LTCG Tax Cut: Would Investors Really Benefit?
Summary
Budget 2027 could bring changes to India's long term capital gains tax, but no cut is approved. Discover how lower LTCG rates might affect equity investors, mutual funds and property sellers, with practical tax saving examples. India may be considering a reduction in long term capital gains tax ahead of Budget 2027. For investors holding shares or equity mutual funds, that sounds promising. Paying less tax on investment profits could mean retaining more of the gains earned over time. But there is a more important question.
Published on
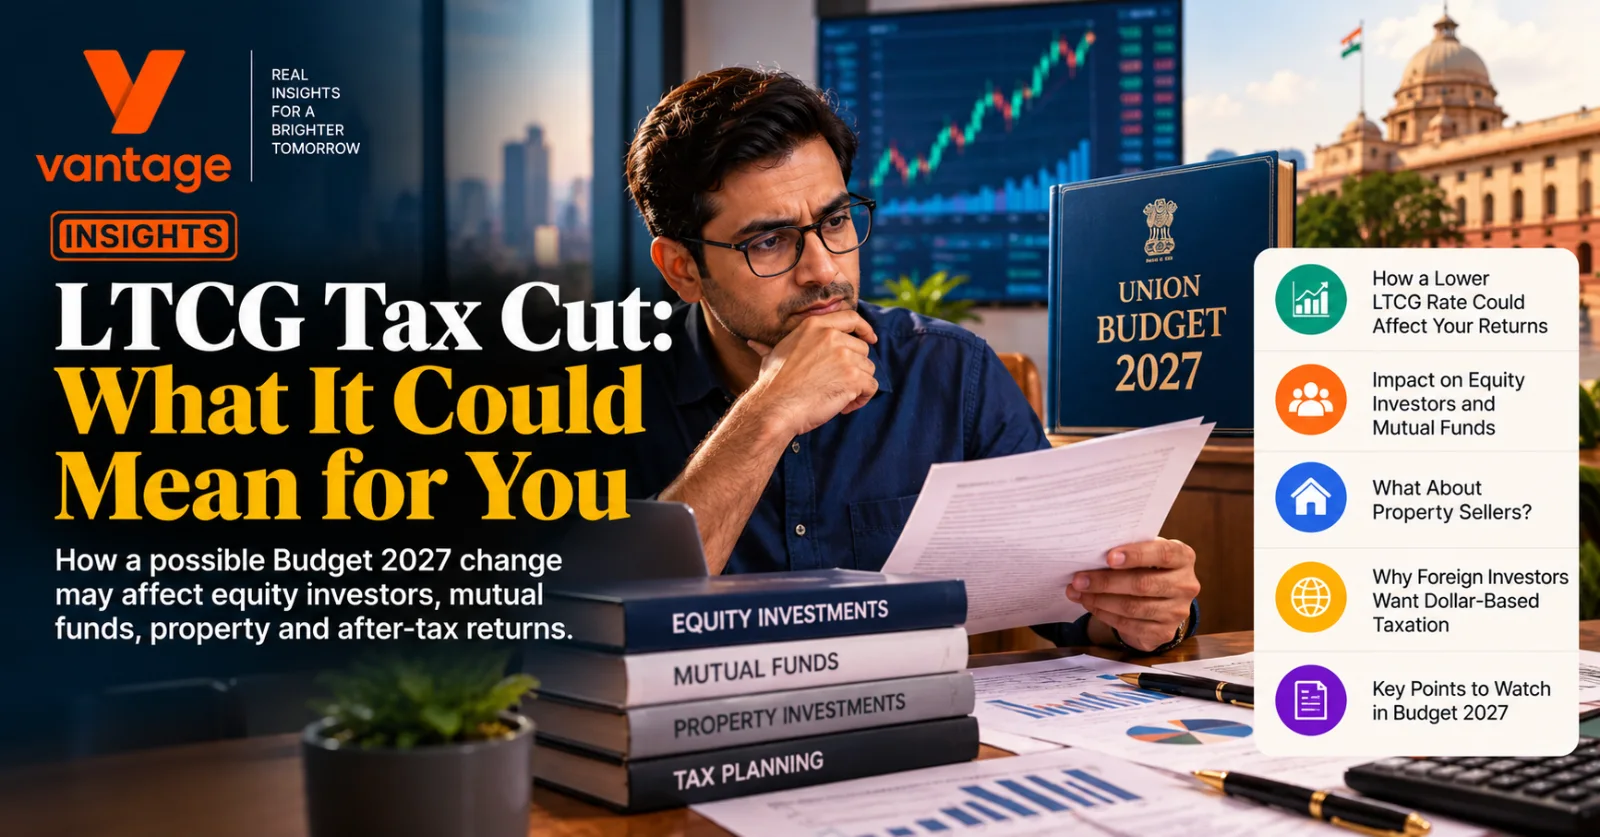
The image explores how a potential long-term capital gains tax reduction in Budget 2027 could affect Indian investors. It highlights the implications for equity investments, mutual funds, after-tax returns and the proposed dollar-based taxation of foreign investors. No tax cut has been officially announced.
Inline Intelligence
India may be considering a reduction in long-term capital gains tax ahead of Budget 2027.
For investors holding shares or equity mutual funds, that sounds promising. Paying less tax on investment profits could mean retaining more of the gains earned over time.
But there is a more important question.
How much would a lower LTCG tax rate actually improve your financial outcome, and would it justify changing your investment decisions?
The answer depends on the eventual policy, the size and nature of the gains, investment costs, time horizon and market performance.
For now, no new rate has been approved.
What Is Changing in the Capital Gains Tax Debate?
An Indian Express report dated 26 October 2026 says the government is discussing a reduction in long-term capital gains taxation and possible dollar-based capital gains calculations for foreign portfolio investors.
These discussions are reportedly taking place amid concerns over subdued equity-market returns and overseas capital flows.
They build on an earlier public discussion about equity taxation involving Finance Minister Nirmala Sitharaman.
Vantage examined that earlier stage in -> LTCG and STT: Review Reports Do Not Mean a Tax Cut.
The new reporting introduces more detail about the options being considered.
However, discussion of a policy change and implementation of that policy are separate events.
Investors should not calculate their current tax liability using an unannounced rate.
How Much LTCG Tax Do Equity Investors Currently Pay?
Under the published framework, qualifying long-term capital gains from specified listed equity shares and equity-oriented mutual funds are taxed at a 12.5% base rate on aggregate eligible gains exceeding ₹1.25 lakh during the financial year.
This treatment is subject to eligibility requirements, including relevant securities transaction tax conditions.
Cess and any applicable surcharge are additional considerations.
The Income Tax Department's official guidance explains the current rates and asset-specific rules.
The tax treatment of an investment also depends on whether its gains qualify as long-term or short-term.
A policy announcement reducing one rate would not automatically change every other tax on investing.
What Could a Lower LTCG Tax Rate Save?
Consider a hypothetical resident investor who sells eligible equity mutual fund units after satisfying the applicable long-term holding-period requirements.
Assume the investor has an aggregate realised long-term gain of ₹5 lakh for the year and qualifies for the ₹1.25 lakh annual threshold.
The taxable amount, before considering other circumstances, is ₹3.75 lakh.
At the current 12.5% base rate:
₹3,75,000 × 12.5% = ₹46,875.
Now imagine a purely hypothetical future policy reducing that base rate to 10%, while retaining the same exemption threshold and other relevant rules.
At 10%:
₹3,75,000 × 10% = ₹37,500.
The difference would be ₹9,375 before cess and any applicable surcharge.
| Hypothetical calculation | Current base rate | Illustrative lower rate |
|---|---|---|
| Eligible taxable gain | ₹3,75,000 | ₹3,75,000 |
| LTCG base tax rate | 12.5% | 10% |
| Base tax | ₹46,875 | ₹37,500 |
| Difference | ₹9,375 |
The 10% rate is an illustration, not an announced government proposal.
The final outcome of any actual reform could differ because the government might change rates, thresholds, eligibility rules or implementation dates together.
For an investor with no taxable eligible gains after the applicable threshold, a lower rate may produce no immediate benefit.
Could Tax Relief Make a Poor Investment Attractive?
Not automatically.
Suppose two investors purchase different securities.
One investment generates strong underlying earnings growth and reasonable price appreciation.
The other experiences declining business performance and loses value.
A reduction in capital gains tax may improve the after-tax outcome for realised taxable profits, but it cannot turn a loss-making investment into a guaranteed positive return.
Investment quality and tax efficiency are related but distinct.
Investors should consider business fundamentals, portfolio diversification, costs, liquidity and risk before giving tax treatment excessive importance.
The lowest-tax investment is not necessarily the best investment.
Why Are Foreign Investors Asking About Dollar-Based Gains?
Foreign portfolio investors may invest funds sourced in foreign currency and assess performance in US dollars or other international currencies.
Consider a simplified example.
An overseas investor converts $10,000 into rupees when the exchange rate is ₹80 per dollar.
The initial rupee investment is ₹8,00,000.
Later, the investor sells the asset for ₹9,00,000 when the exchange rate is ₹95 per dollar.
Measured in rupees, the transaction produces a ₹1,00,000 gain before expenses and taxes.
But the proceeds are equivalent to approximately $9,474 at the later exchange rate.
The investor therefore receives approximately $526 less than the initial $10,000 when measured in dollars.
This simplified example demonstrates how a positive rupee return can coexist with a negative foreign-currency return.
It does not establish the actual tax liability of a particular FPI.
The applicable laws, investor classification, security type, currency-conversion provisions and tax treaty rules can materially change the result.
Would Dollar-Based Taxation Benefit Indian Retail Investors?
Not necessarily.
The Indian Express specifically reports discussions concerning foreign portfolio investors.
A rule designed for overseas investors would not automatically extend to Indian residents investing in domestic shares or mutual funds.
Similarly, tax rules applicable to foreign securities, international funds and other overseas investments can differ from those applicable to Indian listed equities.
Readers should avoid assuming that a proposed foreign-investor relief would change their own tax treatment.
The final legal language would determine who qualifies.
Why Could the Government Consider Reducing LTCG Tax?
Tax policy can influence investors' decisions by changing the difference between pre-tax and after-tax returns.
If an investor retains a larger portion of realised profits, the investment's after-tax outcome may improve.
However, reducing tax rates can also affect government revenue.
The government must consider whether the potential economic benefits of a concession justify its fiscal cost.
Lowering LTCG tax would not necessarily resolve concerns about market valuations, corporate earnings, international interest rates or currency volatility.
These factors can influence investment decisions independently of tax rates.
That creates a genuine policy trade-off: encouraging long-term investment while maintaining a coherent and sustainable tax framework.
What About Real Estate Capital Gains?
Property owners should not assume that an equity-market tax discussion automatically applies to property sales.
The Indian capital gains framework includes rules that differ by asset type and acquisition date.
Under current official guidance, qualifying long-term gains from many assets are generally subject to a 12.5% base rate without indexation, subject to applicable exceptions.
Resident individuals and Hindu Undivided Families disposing of eligible land or buildings acquired before 23 July 2024 can, under the specified grandfathering provision, compare the applicable 12.5% treatment without indexation with the permitted 20% treatment using indexation.
Other provisions, including qualifying reinvestment relief, may be relevant depending on the transaction.
The Income Tax Department's property and capital gains guidance should be consulted alongside current legislation.
A proposed equity-market reform is not sufficient evidence that property capital gains rates, exemptions or grandfathering provisions will change.
For someone planning to sell a property, the correct calculation requires the actual acquisition details, sale date, qualifying costs, exemptions and applicable legal provisions.
Could Investors Benefit Even Without Selling?
A reduction in the tax charged on future realised gains could increase the potential after-tax value of an investment.
However, the practical tax benefit generally becomes relevant when a qualifying taxable transaction occurs.
A change in expected future taxation might also influence market sentiment or valuation expectations.
But it would be difficult to isolate that effect from other market developments.
The existence of a tax proposal does not mean an investor's portfolio value will rise.
Should Investors Delay Selling Until Budget 2027?
A possible tax cut alone is not a sufficient reason to delay a necessary transaction.
Consider someone who needs funds for a home down payment or another fixed obligation.
Waiting for a hypothetical tax benefit may expose the money to additional market volatility.
If the asset declines substantially while the investor waits, the capital loss could outweigh any potential tax saving.
The eventual reform may also have an effective date, eligibility conditions or transitional rules different from those investors expect.
An investment sale should therefore be evaluated using current law and the investor's actual objectives.
If the transaction involves significant tax consequences, a qualified tax professional can assess the relevant options.
What Should Investors Watch Next?
1. Verify the actual legal announcement
A media report, ministerial comment or policy discussion is not equivalent to enacted tax legislation.
Check the Budget documents and subsequent legal provisions.
2. Identify the investments covered
Determine whether any reform applies to listed shares, equity mutual funds, business trust units, foreign investors or other specified assets.
Do not assume a universal tax reduction.
3. Examine rates and thresholds together
A reduction in the headline rate may be accompanied by changes to exemption thresholds, qualifying periods or other conditions.
Evaluate the complete calculation.
4. Consider taxes alongside investment risk
Review the investment's expected role, costs, liquidity requirements and downside risk.
Tax relief is only one component of a financial decision.
The Bigger Question for Budget 2027
India's equity-tax discussions reflect a wider challenge: how to encourage sustained investment participation when market returns and investor expectations are under pressure.
A lower LTCG rate could improve after-tax realised gains for eligible investors.
Dollar-based calculations could address an important currency-related concern for some foreign investors.
But neither proposal has been enacted, and neither can guarantee higher market returns.
For Indian households, the useful response is to understand the existing law, evaluate what a potential change could actually save and avoid making financial decisions based on assumed Budget outcomes.
A better tax rate can improve investment returns after tax. It cannot replace a sound investment decision.
FAQ
1. Has India announced an LTCG tax cut for Budget 2027?
No. As of 26 October 2026, available reporting describes government discussions, not an enacted reduction or confirmed Budget provision.
2. What is the current LTCG tax rate on eligible Indian equities?
Under the published rules, qualifying long-term gains from specified listed shares and equity-oriented mutual funds are subject to a 12.5% base rate on aggregate eligible gains exceeding ₹1.25 lakh, subject to conditions and additional applicable taxes.
3. Could the LTCG tax rate fall to 10%?
That is one possible hypothetical scenario, not a confirmed government proposal. No revised rate has been formally announced.
4. Would a lower LTCG rate apply to mutual funds?
It would depend on the final legislation and the categories of mutual funds covered. Not all mutual funds receive identical capital gains tax treatment.
5. Would property sellers automatically benefit?
No. A reported review of equity capital gains taxation does not establish any change to property capital gains tax.
6. What is dollar-based taxation for foreign investors?
It broadly refers to calculating relevant taxable investment gains in foreign-currency terms, potentially reducing distortions arising from exchange-rate movements. The precise treatment would depend on legislation.
7. Does an LTCG tax cut guarantee higher stock market returns?
No. Tax changes affect after-tax outcomes but do not guarantee investment price appreciation or positive returns.
8. Should investors sell shares before Budget 2027?
The answer depends on investment goals, market risk, liquidity needs, current legal rules and individual circumstances. A reported possibility of tax changes is not a reliable basis for timing a transaction.
9. Are short-term capital gains and STT being removed?
No such change has been confirmed in the reporting reviewed for this article. Different taxes and transaction categories must be considered separately.
10. How can investors confirm any future tax change?
Consult official Union Budget documents, enacted legislation, notifications and updated Income Tax Department guidance rather than relying solely on news headlines.
Sources
Click an article title to view the source.
- Budget 2027: Govt weighs LTCG tax cut, dollar-based taxation for FPIs, published on 26 October 2026 in The Indian Express.
- Capital Gain, updated on 27 May 2026 by the Income Tax Department, Government of India.
- Tax on Sale of Shares in India, available in October 2026 from the Income Tax Department, Government of India.
- Tax Rates and Computation, available in October 2026 from the Income Tax Department, Government of India.
- LTCG and STT: Review Reports Do Not Mean a Tax Cut, published on 15 October 2026 in Vantage Radar.
Evidence Caveats
The 26 October reporting cites government discussions and unnamed official sources. No formal revised LTCG tax rate, foreign-investor currency-conversion method or implementation date has been established.
The illustrative 10% tax scenario is hypothetical and is not an announced government rate.
The financial examples simplify tax calculations and exclude some potentially applicable items, including transaction costs, cess, surcharge and individual tax circumstances.
The foreign-currency example demonstrates an economic return difference, not the actual taxable gain of a specific investor.
Tax rules can vary by asset class, holding period, taxpayer status, transaction date and applicable exemptions. The property discussion does not imply that any proposed equity-tax change applies to real estate.
Join the discussion: Would a lower capital gains tax rate influence how long you hold your investments, or would business performance and market valuation remain more important? Do you think currency-adjusted taxation is necessary to attract foreign investors? Share your reasoning and alternative perspectives in the attached forum discussion.
Disclaimer
This article is for general educational and informational purposes only. It is not personalised financial, investment, legal or tax advice. No future tax reduction or investment outcome is guaranteed. Readers should verify applicable law and seek advice from appropriately qualified professionals before making significant investment or tax decisions.
From TatvaOps
Property Development
Developing a property?
Structured oversight for multi-unit and investor-led builds.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
1 reply already on Forums
More from Real Estate
Mumbai Luxury Home Data What Buyers Should Check
Luxury registration totals are not a like-for-like price index. Here is how buyers can compare properties and ownership costs.
Binance Security Incident What Holders Can Check
The Binance incident highlights the difference between a displayed balance and access to assets. Here are practical checks for holders.
Gurugram Power Choice What Residents Should Check
A proposed second electricity distributor is on hold. Here is what Gurugram and Nuh residents can check on bills and service.
Inline Intelligence
Key Insight Actions
Connected knowledge for Taxation & Investment
Move between tutorials, discussions, Studio, and hubs without losing context.
Conclusion Intelligence
Was this helpful?
Let us know what you think