
Is Nifty 50 Undervalued? What Investors Should Check
Summary
But is the Indian stock market genuinely undervalued? Explore PEG ratios, earnings forecasts, bond yields and the risks investors should examine. The Nifty 50's valuation has fallen considerably from its 2024 peak. According to research cited by The Economic Times, its forward price to earnings ratio declined from 24.8 in September 2024 to 17.2 in September 2026. The index's price/earnings to growth ratio is also approaching one of its lowest levels in a decade. For investors, that sounds like a potential opportunity. But there is a fundamental question behind the numbers.
Published on
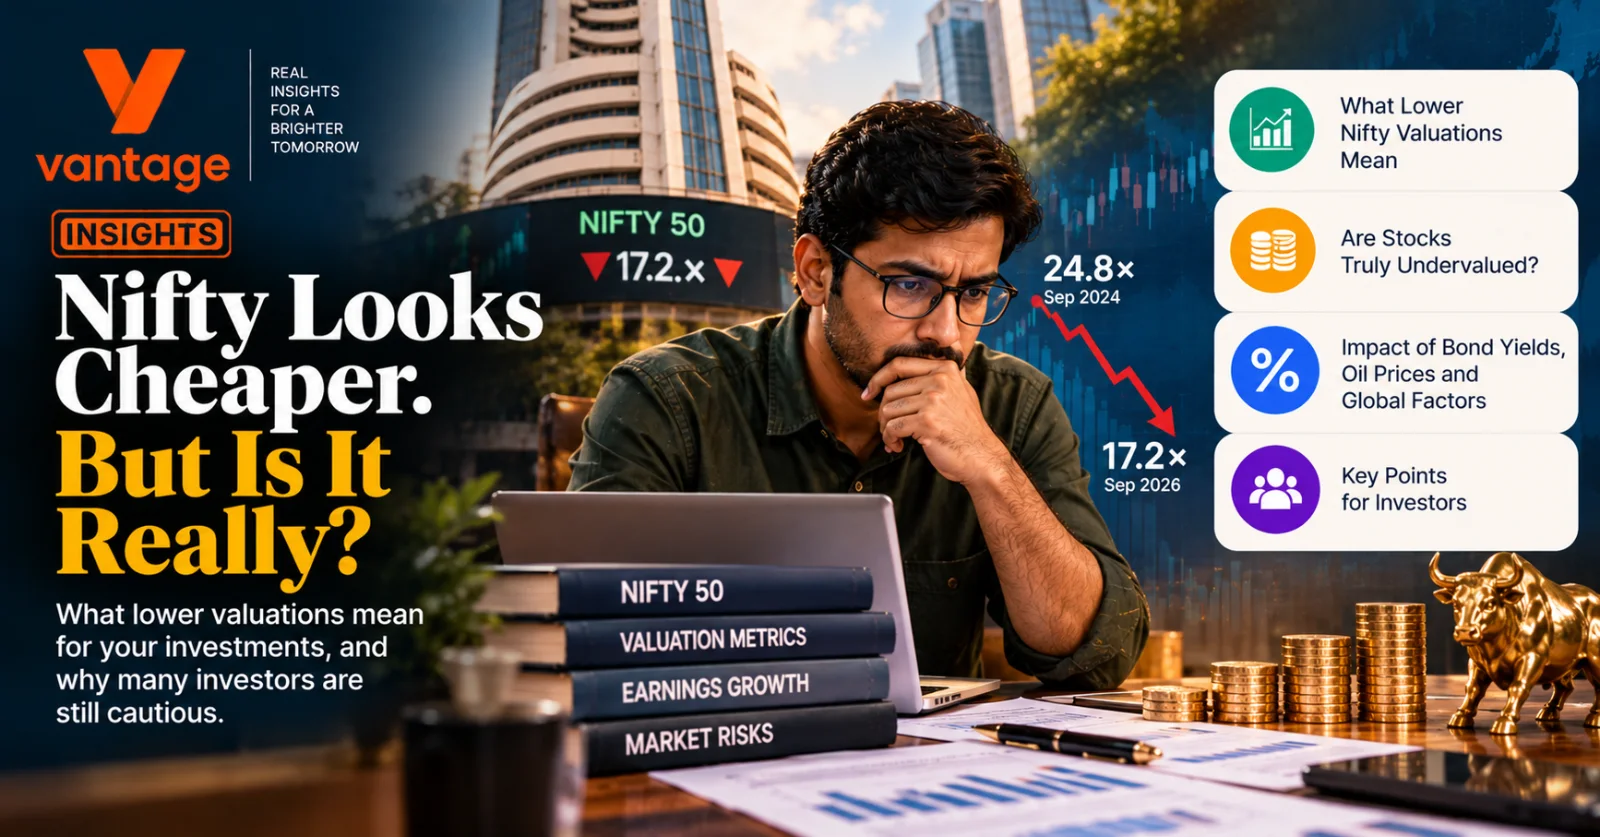
India's Nifty 50 forward P/E ratio declined from 24.8× in September 2024 to 17.2× in September 2026, making stock market valuations appear more attractive. The image explores whether Indian equities are genuinely undervalued amid earnings uncertainty, higher bond yields and global market risks.
Inline Intelligence
The Nifty 50's valuation has fallen considerably from its 2024 peak.
According to research cited by The Economic Times, its forward price-to-earnings ratio declined from 24.8 in September 2024 to 17.2 in September 2026.
The index's price/earnings-to-growth ratio is also approaching one of its lowest levels in a decade.
For investors, that sounds like a potential opportunity.
But there is a fundamental question behind the numbers.
Does paying less for expected earnings automatically mean you are getting a good investment?
Not necessarily.
A lower valuation can improve potential future returns, but only when the underlying business prospects and risks justify the price.
Why Does the Nifty Look Cheaper?
A price-to-earnings ratio, or P/E, expresses how much investors are paying for each rupee of a company's earnings.
For a stock index, the ratio reflects the valuation of its constituent companies using the applicable index methodology.
A forward P/E uses estimated future earnings rather than profits already reported.
Consider a hypothetical business expected to earn ₹10 per share over the coming year.
At a share price of ₹250, it trades at 25 times expected earnings.
If its share price falls to ₹180 while its earnings estimate remains unchanged, the forward P/E falls to 18.
Investors are now paying a lower price for the same projected earnings.
That can make the investment more attractive, provided the earnings estimate remains realistic.
The complication is that expected earnings may change.
If analysts later reduce the business's expected earnings to ₹7.50 per share, the stock trading at ₹180 would again have a forward P/E of 24.
The share price did not rise, but the stock became more expensive relative to its revised earnings forecast.
This is one reason analysts hesitate to describe a market as cheap solely because its forward P/E has declined.
What Does the Latest Nifty Data Tell Us?
A 26 October Economic Times analysis cited Bajaj Asset Management research showing the Nifty 50's forward P/E falling from 24.8 to 17.2 over two years.
The index's valuation multiple contracted by approximately 30.6%.
The research also reported a divergence between index prices and expected earnings.
The Nifty declined around 8% year-on-year in September 2026 while its forward earnings-per-share estimate increased 9.62%.
That makes the valuation reset more interesting than a simple price decline.
However, the earnings improvement is partly based on forecasts.
Future results may confirm, exceed or disappoint those expectations.
What Is a PEG Ratio, and Why Does It Matter?
The PEG ratio is a valuation measure that compares a P/E multiple with an expected earnings growth rate, conventionally expressed as a percentage.
For example, consider two hypothetical companies.
| Measure | Company A | Company B |
|---|---|---|
| Forward P/E | 20 | 30 |
| Expected annual earnings growth | 20% | 10% |
| PEG ratio | 1.0 | 3.0 |
Company A has the lower PEG ratio because its valuation is lower relative to its projected growth.
An investor might therefore consider it more attractive on that particular measure.
But the comparison depends on the reliability of both growth forecasts.
Company A may operate in a cyclical industry where earnings growth is unusually strong for one year and difficult to sustain.
Company B may have slower but more predictable growth.
The PEG ratio does not independently capture business quality, debt, cash flow, liquidity or interest-rate risks.
That is why a low PEG ratio should be treated as an analytical starting point rather than a buying signal.
Why Can Stocks Remain Expensive Even at Lower P/E Ratios?
Valuation is relative.
An equity investment competes with other assets for investors' capital.
If government bond yields rise, investors may require greater expected returns from stocks to justify their additional risk.
The relationship can be illustrated through earnings yield, calculated as the reciprocal of the P/E ratio.
At a forward P/E of 17.2, the corresponding forward earnings yield is approximately 5.8%.
That does not mean an investor receives a guaranteed 5.8% cash return.
It is an accounting-based valuation measure using projected earnings.
It also should not be compared directly with a bond's promised coupon or redemption yield without considering earnings growth, reinvestment, inflation and risk.
A bond may offer contractually specified cash flows, subject to issuer and other risks.
Equity earnings are uncertain and do not necessarily translate into shareholder distributions.
If bond yields rise while expected equity earnings weaken, a lower P/E multiple may still be insufficient compensation for the risks of stock ownership.
What If Corporate Earnings Do Not Recover?
Expected earnings growth is central to the current valuation argument.
Bajaj AMC's research, cited by Economic Times, projects BSE 500 earnings growth of 17% in FY2027 and 16% in FY2028.
These figures are forecasts, not achieved results.
Corporate earnings depend on consumer demand, borrowing costs, input prices, foreign demand and company-specific performance.
Elevated crude oil prices could increase costs for energy-intensive businesses.
Higher interest rates could affect financing expenses and demand.
Currency volatility could help some exporters while creating difficulties for companies dependent on imported inputs.
If earnings growth falls short of expectations, an apparently reasonable forward P/E could become less attractive.
Conversely, sustained earnings growth could strengthen the case for current valuations.
This is the tension investors are trying to resolve.
Is India Cheap Compared With Other Markets?
A market can be inexpensive relative to its own past and expensive compared with other countries.
A second Economic Times report dated 26 October examined the dollar-denominated MSCI India Index.
It reported that MSCI India traded at approximately 18.5 times forward earnings, below its 10-year average of 19.7.
However, the broader MSCI Emerging Markets Index traded at approximately 8.7 times forward earnings.
These indices have different compositions and market exposures, so their multiples cannot be interpreted as directly comparable measures of quality.
The valuation premium may reflect differing growth expectations, sector structures, governance considerations or perceived risks.
For overseas investors, the comparison also involves currency returns.
An Indian equity investment may produce a positive rupee return while generating a weaker dollar return if the rupee depreciates.
A lower domestic valuation is therefore not guaranteed to attract foreign capital.
Should Investors Prefer Large-Cap Funds Now?
Not automatically.
The Nifty 50's valuation reset appears more substantial than the reset in some smaller-company indices.
Research cited by Economic Times reported the Nifty Midcap 150 forward multiple falling to 22.8 and the Nifty Smallcap 250 to 23.2 in September 2026.
Those figures can support further examination of relative valuations.
But large-cap, mid-cap and small-cap funds serve different potential roles in a portfolio.
Large companies may offer relatively established businesses and greater share-trading liquidity, but they remain exposed to earnings disappointments and market declines.
Mid-cap and small-cap businesses may offer attractive growth opportunities, but their shares can experience greater volatility or liquidity constraints.
Fund selection should account for the investor's objective, investment horizon, existing exposures, costs and capacity to withstand losses.
A fund is not suitable simply because its underlying index has become cheaper.
What Does This Mean for SIP Investors?
A systematic investment plan allows an investor to make contributions at regular intervals.
When a fund's net asset value declines, a fixed contribution generally purchases more units.
This can reduce dependence on making one investment at a particular market level.
However, continuing a SIP does not guarantee positive future returns.
The underlying fund can still experience prolonged losses or underperform its benchmark.
Investors with long-term goals may assess whether regular contributions remain appropriate, rather than reacting solely to a valuation headline.
Those approaching a fixed financial deadline may face different risks.
For example, someone accumulating money for a property down payment within the next year may have less flexibility to tolerate a large market decline than someone investing for retirement decades away.
Should Investors Buy Immediately Because Valuations Are Lower?
A lower valuation does not create a reliable deadline for investing.
Markets can become cheaper and remain cheap for extended periods.
Earnings estimates may fall, bond yields may rise, and global economic risks may continue.
A hypothetical investor buying an index fund at a lower P/E can still experience losses if its underlying shares decline further.
Investors should also avoid assuming that a lower P/E guarantees the market will return to its previous valuation multiple.
Valuations may remain below past averages if growth expectations, interest rates or risk perceptions have changed.
The relevant question is not simply whether the current multiple is below its historical peak.
It is whether expected earnings and potential future returns reasonably compensate for the risks being taken.
What Should Investors Check Next?
1. Look beyond the index's current P/E
Compare forward and trailing P/E ratios, earnings forecasts and valuation history.
Understand why different research providers may report different multiples.
2. Examine earnings expectations
Review whether expected corporate growth is supported by recent results, margins, cash flows and business conditions.
Forecast upgrades and downgrades can change the valuation picture.
3. Check portfolio concentration
An investor holding several equity funds may still have significant exposure to the same large companies.
Review the underlying holdings and allocation across sectors and company sizes.
4. Match risk with financial goals
Consider investment horizon, emergency liquidity, near-term payment obligations and tolerance for temporary losses.
A market valuation signal should not override the purpose for which money is being invested.
The Bigger Lesson: Cheap Is Not the Same as Good Value
India's large-cap equity market is clearly less expensive on certain valuation measures than it was two years earlier.
The Nifty 50's lower forward P/E and improving PEG ratio deserve attention.
But an attractive investment requires more than a favourable historical comparison.
Future earnings must support current prices. Interest rates must be considered. The risks of alternative investments and the broader economic environment remain relevant.
For long-term investors, today's figures may justify examining opportunities more closely.
They do not establish a risk-free bargain or predict the next market rally.
The goal is not to buy because the market looks cheaper. It is to understand whether the price offers enough value for the risks involved.
FAQ
1. What is the Nifty 50 forward P/E in September 2026?
Bajaj AMC research cited by Economic Times estimated a 12-month forward P/E of 17.2 for September 2026. Other providers may report different figures because of methodology and earnings forecasts.
2. Is the Nifty 50 at its lowest valuation in ten years?
Its PEG ratio is reportedly approaching one of its lowest levels in a decade. This does not mean every Nifty valuation measure is at a ten-year low.
3. What is a good PEG ratio?
A PEG near 1 is sometimes considered attractive, but no universal threshold establishes fair value. Forecast reliability and business risks matter.
4. Does a lower P/E mean stocks will rise?
No. Prices may fall further, and earnings expectations can change.
5. Why do higher bond yields affect stock valuations?
Higher bond yields can increase the opportunity cost of owning equities and the returns investors require for taking additional risk.
6. Is India cheaper than other emerging markets?
India's valuation has fallen relative to its own history, but research reports that Indian equities still trade at a substantial forward earnings premium to the wider emerging-market benchmark.
7. Are large-cap mutual funds safer than small-cap funds?
Large-cap funds may differ in liquidity and business exposure, but they remain subject to market risk. Suitability depends on individual goals and circumstances.
8. Should SIP investors change their investments because the Nifty P/E has fallen?
A valuation decline alone is insufficient. Investors should assess their goals, existing allocation, fund characteristics and risk tolerance.
9. What could cause Nifty valuations to fall further?
Potential drivers include weaker earnings forecasts, rising interest rates, economic uncertainty, foreign investor selling and changing risk sentiment.
10. Can current valuations predict future returns?
Valuation measures can inform expectations and risk assessments, but they cannot reliably predict the timing or magnitude of future returns.
Sources
Click an article title to view the source.
- Nifty's PEG ratio near 10-year low but why don't stocks look cheap yet? Valuation paradox explained, published on 26 October 2026 in The Economic Times.
- India valuations hit six-year low, but more expensive than emerging market peers, published on 26 October 2026 in The Economic Times.
- Nifty valuations near post-Covid lows: Alchemy Capital's Alok Agarwal explains what investors should buy now, published on 2 October 2026 in The Economic Times.
Evidence Caveats
The forward P/E, PEG and earnings-growth figures are attributed to institutional research reported by The Economic Times. The full underlying proprietary research models were not independently examined.
The Nifty 50 and MSCI India indices use different methodologies and constituent universes. Their valuations should not be treated as interchangeable.
PEG ratios depend on expected earnings growth and can change substantially when forecasts are revised.
Illustrative examples use hypothetical companies and simplified assumptions. They exclude taxes, expenses and company-specific changes in capital structure.
No valuation measure guarantees a future return or identifies a reliable market bottom.
Join the discussion: Is the Nifty's falling P/E an opportunity to increase long-term equity exposure, or do earnings uncertainty and global risks still justify caution? Which valuation measures do you find most useful, and where do they fall short? Share your reasoning and supporting evidence in the attached forum discussion.
Disclaimer
This article is for general educational and informational purposes only. It is not personalised investment, financial, legal or tax advice. No specific security, index fund or investment strategy is recommended. Securities and mutual funds carry market risk, including potential capital loss. Readers should evaluate their circumstances and consult appropriately qualified advisers where necessary.
From TatvaOps
Property Development
Developing a property?
Structured oversight for multi-unit and investor-led builds.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
2 replies already on Forums
More from Real Estate
Mumbai Luxury Home Data What Buyers Should Check
Luxury registration totals are not a like-for-like price index. Here is how buyers can compare properties and ownership costs.
Binance Security Incident What Holders Can Check
The Binance incident highlights the difference between a displayed balance and access to assets. Here are practical checks for holders.
Gurugram Power Choice What Residents Should Check
A proposed second electricity distributor is on hold. Here is what Gurugram and Nuh residents can check on bills and service.
Inline Intelligence
Key Insight Actions
Connected knowledge for Market Analysis
Move between tutorials, discussions, Studio, and hubs without losing context.
Conclusion Intelligence
Was this helpful?
Let us know what you think