

GCCs Now Drive 42 of India's Office Leasing: Is Commercial Real Estate Becoming Too Dependent on Them?
Karthik posts articles on Energy and Construction.
Summary
India's office market absorbed a record 66.4 million sq ft in the first nine months of 2026, with GCCs accounting for 28 million sq ft. The opportunity is significant, but rising supply and growing tenant concentration make building quality, location and diversification increasingly important. India's office market has reached another record. But underneath that headline sits an even more important number. Global Capability Centres leased approximately 28 million sq ft. That is around 42% of India's nine month office absorption . GCC demand increased 16% year on year, faster than the overall office market.
Published on
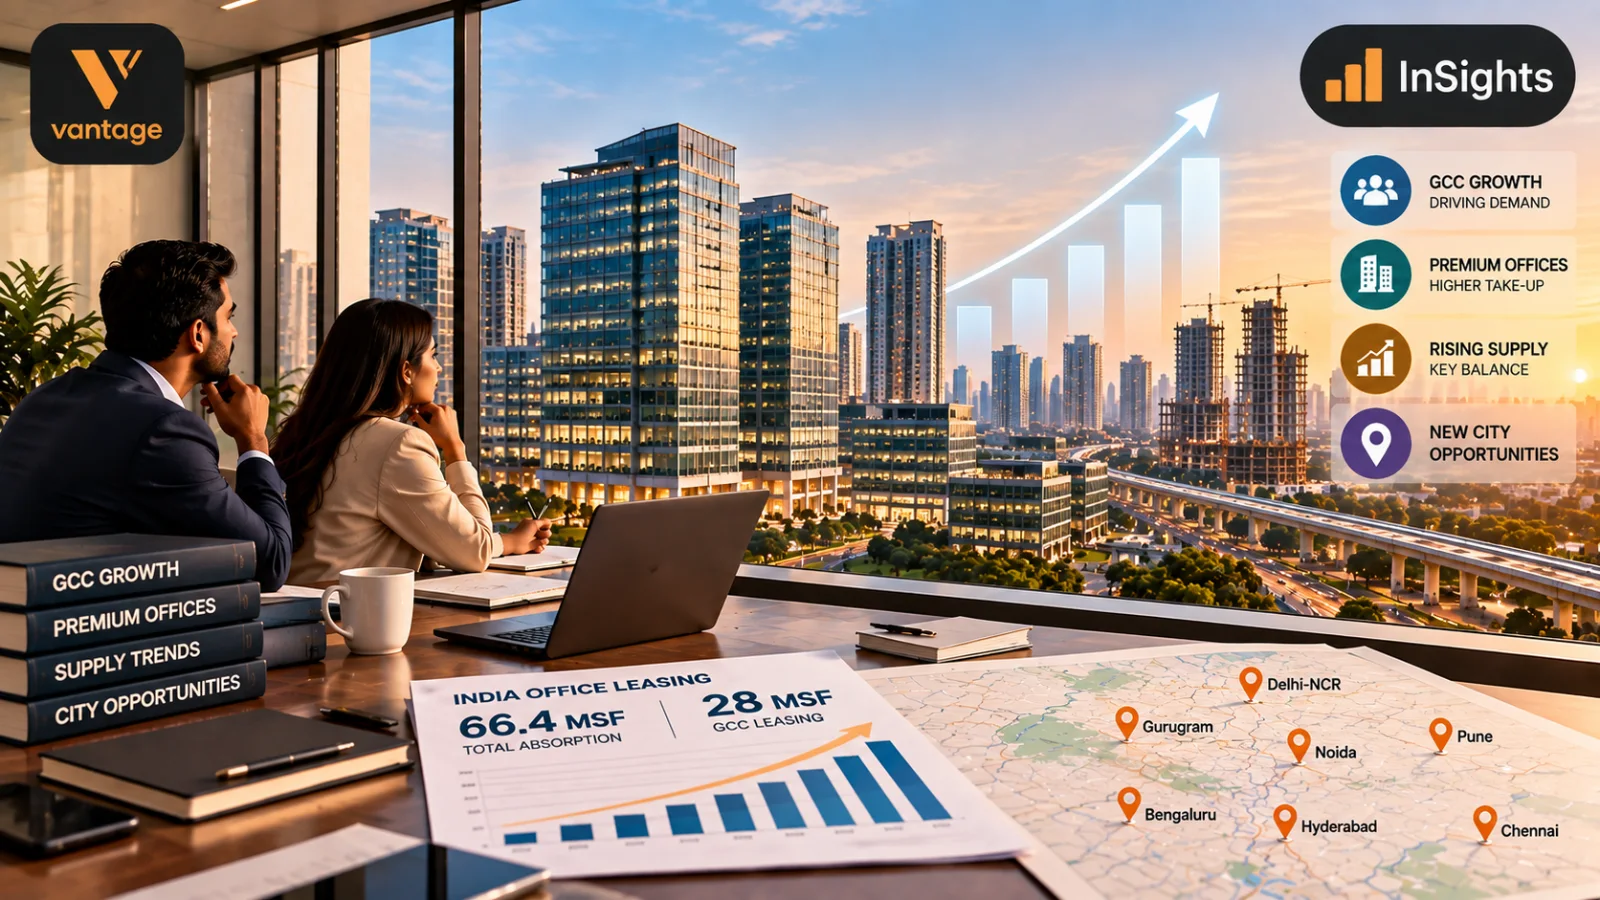
A modern Indian commercial business district with occupied glass office towers and new office construction, illustrating record office absorption and GCC-led leasing demand.
Inline Intelligence
India's office market has reached another record.
Approximately 66.4 million sq ft was absorbed during the first nine months of 2026, up 8% year-on-year.
But underneath that headline sits an even more important number.
Global Capability Centres leased approximately 28 million sq ft.
That is around 42% of India's nine-month office absorption.
GCC demand increased 16% year-on-year, faster than the overall office market.
And in Q3, GCCs accounted for 59% of transactions larger than 100,000 sq ft.
For commercial real estate, this is a powerful structural demand engine.
It also creates a question worth examining:
Is India's office market becoming increasingly dependent on the expansion strategies of global corporations?
The GCC Share Is Large Enough to Change the Market
Twenty-eight million sq ft is not an additional market sitting beside India's 66.4 million sq ft office total.
It is part of it.
Dividing 28 million by 66.4 million gives approximately 42.2%, a Vantage-derived calculation that broadly matches CBRE's reported 42% GCC share.
This means more than four out of every ten square feet absorbed during the period was associated with GCC demand.
That is large enough to influence:
- development decisions;
- building specifications;
- location strategy;
- floor-plate design;
- sustainability standards;
- infrastructure requirements; and
- landlord leasing strategies.
GCCs are no longer a niche subset of India's office market.
They are one of its defining forces.
Why GCCs Need So Much Office Space
The nature of GCCs has changed.
Historically, many multinational operations in India were associated primarily with cost-efficient back-office work.
Today's GCCs increasingly handle:
- artificial intelligence;
- engineering;
- research;
- analytics;
- cybersecurity;
- finance;
- product development; and
- other specialised functions.
These operations can employ large teams.
They can also require high-quality offices capable of supporting technology infrastructure, employee amenities, security and collaboration.
That helps explain why GCCs represented 59% of Q3 office transactions above 100,000 sq ft.
This is not simply a high number of small leases.
It is demand for scale.
Hyderabad and Bengaluru Still Have a Major Advantage
Hyderabad captured approximately 37% of Q3 GCC leasing.
Bengaluru captured approximately 28%.
Together, they represented roughly 65% of quarterly GCC leasing.
That concentration reflects more than available office buildings.
GCC location decisions depend heavily on access to talent.
Cities with deep pools of engineers, technology professionals, finance specialists and experienced managers have an advantage that cannot be reproduced simply by constructing new office towers.
For commercial-property developers, this means office supply does not automatically create GCC demand.
The surrounding employment ecosystem matters.
But the Next GCC Cycle Could Spread Beyond the Largest Hubs
Vantage previously examined CBRE research suggesting that GCC expansion could push office demand into additional Indian cities.
State governments are competing for these operations through GCC policies and incentives.
Companies, meanwhile, may seek:
- lower operating costs;
- access to different talent pools;
- business-continuity diversification; and
- expansion capacity outside expensive core markets.
This creates a potential second-order commercial real-estate opportunity.
The first GCC cycle strengthened India's established technology hubs.
The next one could create institutional-grade office demand in a wider set of cities.
But policy incentives alone will not guarantee success.
Cities still need talent, infrastructure and suitable commercial buildings.
The Bigger Risk Is Not GCC Demand Disappearing Overnight
The more realistic risk is concentration.
If developers assume every new Grade A building will attract a GCC, too much similar supply could emerge in particular corridors.
The national numbers already deserve attention here.
Office absorption increased 8% during January to September.
New supply increased 18%.
That does not establish oversupply because absorption remained larger than new completions and the market contains existing inventory.
But it does show that supply is growing faster than demand on a percentage basis.
The balance therefore needs to be examined city by city.
The 51 Million Sq Ft Supply Record Changes the Question
India added approximately 51 million sq ft of office supply during the first nine months of 2026.
That was also a nine-month record.
This is encouraging if demand continues.
It becomes more complicated if developers add capacity in the wrong places or with the wrong specifications.
Commercial real estate is highly local.
A city can have strong headline leasing while one peripheral micro-market still struggles with vacancy.
Likewise, an older building can lose tenants even while citywide demand rises.
The national record therefore does not mean every office asset benefits equally.
The Flight to Quality Is Becoming Hard to Ignore
Perhaps the most important number for existing landlords is 82%.
Green-certified assets accounted for approximately 82% of Q3 leasing.
They also represented around 80% of new supply.
More than half of new supply was premium Grade A+ stock.
This suggests India's office cycle increasingly contains two different markets:
high-quality modern offices that large occupiers actively want,
and
older or less competitive stock that may need upgrading to retain demand.
Record leasing can therefore coexist with obsolescence.
That is a crucial point for office investors.
An Old Office Building Does Not Automatically Benefit From a Record Market
Suppose national office absorption reaches a record.
A landlord owning an ageing building might assume that stronger demand will automatically improve occupancy and rent.
But if corporate occupiers increasingly require:
- green certification;
- modern HVAC;
- large efficient floor plates;
- better digital infrastructure;
- employee amenities;
- stronger transport connectivity; and
- sustainability compliance,
then demand can migrate towards newer properties.
The record can actually widen the performance gap between high-quality and obsolete assets.
Flexible Workspace Adds Another Layer
Flexible workspace operators accounted for approximately 24% of Q3 leasing, making them the largest sectoral occupier category in CBRE's quarterly breakdown.
This does not conflict with GCCs accounting for 41% of Q3 demand because the categories describe the market through different lenses and can overlap in how corporate workspace is ultimately delivered.
A multinational company may establish a GCC while using:
- directly leased offices;
- managed offices;
- flexible workspace;
- or a combination of these.
That makes India's commercial-property ecosystem more layered.
The landlord may not always lease directly to the corporation occupying the desks.
What Does This Mean for REIT Investors?
The GCC cycle can be supportive for office REITs because many listed portfolios contain institutional-grade properties in India's largest business markets.
Strong demand can potentially improve:
- occupancy;
- lease renewals;
- rental growth;
- tenant diversification; and
- asset values.
But investors should avoid treating national leasing records as a direct REIT earnings forecast.
Individual REIT outcomes depend on:
- asset locations;
- tenant concentration;
- vacancies;
- lease expiries;
- debt;
- rent escalations;
- development pipelines; and
- acquisitions.
Vantage recently reported that India's six listed REITs distributed ₹3,136 crore to investors in Q1 FY27.
The office-leasing record strengthens the demand backdrop, but asset-level fundamentals still determine distributions.
GCC Concentration Can Be Both a Strength and a Risk
Large multinational tenants can offer landlords several advantages.
They may sign substantial leases, invest in fit-outs and create long-term campus requirements.
But large leases create concentration.
A building heavily dependent on one occupier can face significant vacancy if that company eventually consolidates operations.
The right question is therefore not whether GCC tenants are good or bad.
It is:
How diversified is the income stream behind the asset?
That question becomes more important as individual GCC transactions get larger.
Domestic Demand Makes the Market More Resilient
One reason the 42% GCC share should not automatically be interpreted as dangerous dependence is that India's office market has other substantial demand engines.
Domestic occupiers accounted for approximately 46% of nine-month office take-up.
Flexible workspace, BFSI and technology companies were all active.
CBRE described the breadth of demand as one of the strengths of the current cycle.
That diversification provides a useful counterweight to GCC concentration.
The market is increasingly GCC-led, but it is not GCC-only.
Could GCC Growth Change Which Cities Win?
Yes.
The cities that attract the next generation of GCCs can benefit through more than office leasing.
Large capability centres can support:
- professional employment;
- residential demand;
- retail consumption;
- transport infrastructure;
- hospitality;
- business services; and
- additional commercial development.
That makes GCC attraction an urban-development issue, not simply an office-leasing statistic.
But the benefits depend on execution.
A city offering incentives without reliable infrastructure or talent depth may struggle to convert policy ambition into actual leases.
What Should Developers Watch?
The national record should not be interpreted as permission to build indiscriminately.
Developers should monitor:
Pre-leasing
Is demand committed before completion?
GCC enquiry pipelines
Are large occupiers actively considering the micro-market?
Talent availability
Can companies hire at scale in the location?
Competing supply
How much Grade A and Grade A+ stock is arriving nearby?
Sustainability
Can the building meet the requirements of multinational occupiers?
Transport
Can employees reach the property efficiently?
These factors can matter more than national absorption records when deciding whether a specific office development is viable.
What Should Office Investors Watch?
For investors, five signals stand out.
First, GCC leasing growth.
The current 16% increase is stronger than overall absorption growth.
Second, the supply-demand balance.
Supply is growing faster in percentage terms than absorption.
Third, large-deal concentration.
GCCs already dominate transactions above 100,000 sq ft.
Fourth, building quality.
The 82% green-certified leasing share indicates a pronounced flight to quality.
Fifth, geographic diversification.
The next stage of GCC expansion could broaden demand beyond established hubs, but only some cities will successfully convert that opportunity.
The Real Opportunity Is More Specific Than "Buy Offices"
Record leasing can make the investment thesis sound simple:
India needs more offices.
The evidence suggests something more precise.
India appears to need more of the offices that expanding enterprises actually want.
Those are increasingly:
- premium;
- sustainable;
- technology-enabled;
- well connected;
- located near talent; and
- capable of accommodating large occupiers.
That distinction matters enormously.
A record office market does not protect weak buildings from obsolescence.
It can make the strongest buildings even more valuable.
The Next Test for India's Office Boom
India has now recorded 66.4 million sq ft of nine-month absorption.
GCCs contributed 28 million sq ft.
Supply reached 51 million sq ft.
Green-certified assets captured 82% of quarterly leasing.
Those are exceptionally strong operating signals.
The next test is whether the market can maintain the right balance between:
GCC expansion and tenant diversification,
new supply and absorption,
premium buildings and ageing stock,
and
established office hubs and emerging cities.
If that balance holds, GCC expansion could support a much larger institutional commercial real-estate market.
If supply begins chasing the headline faster than genuine occupier demand, the national record could conceal weaker individual micro-markets.
That is the trade-off investors should watch.
Frequently Asked Questions
Are GCCs driving India's office leasing boom?
Yes. GCCs leased approximately 28 million sq ft during January to September 2026, accounting for about 42% of India's 66.4 million sq ft of office absorption.
Is India's office market too dependent on GCCs?
GCCs represent a very large share of demand, but domestic occupiers, flexible workspace operators, BFSI and technology companies also contribute significantly. The main risk is concentration at individual asset and micro-market levels rather than the 42% national figure alone.
Why are GCCs leasing large offices in India?
Global companies are expanding capability centres handling technology, finance, engineering, analytics, AI and other specialised functions. Large teams can require substantial, high-quality office space.
Which cities benefit most from GCC office leasing?
Hyderabad and Bengaluru led Q3 2026 GCC leasing, accounting for 37% and 28% respectively. Chennai and Delhi-NCR each contributed around 11%.
Does record office leasing mean commercial property prices will rise?
Not necessarily. Leasing can support property fundamentals, but asset values also depend on rents, vacancies, interest rates, cap rates, building quality, lease structures and location.
Why are green-certified offices attracting more tenants?
Green-certified assets accounted for approximately 82% of Q3 leasing. Large corporations increasingly prioritise sustainability, building efficiency, employee experience and high-quality workplaces.
Could Tier-2 cities benefit from GCC expansion?
Potentially. GCC expansion can create new office demand beyond major hubs, but emerging cities need suitable buildings, talent, infrastructure and effective policy execution to capture that demand.
Sources
Click on article title to view article.
“India office absorption rises 8% to 66.4 million sq ft in Jan-Sep 2026: Report” published on 2 October 2026 in ETRealty
“Office leasing at record 66.4 mn sq ft in Jan-Sep across top 9 cities, driven by GCCs: CBRE” published on 2 October 2026 in The Economic Times
“Office space leasing increases by 6% on-year during July–September” published on 1 October 2026 in The Economic Times
“India Office Figures Q3 2026” published in October 2026 by CBRE
Related Vantage Coverage
Click on article title to view article.
“GCC expansion could take India's next office boom beyond major cities” published on 15 August 2026 in Vantage-Radar
“Six listed Indian REITs distribute Rs 3,136 crore to investors in Q1 FY27” published on 17 August 2026 in Vantage-Radar
Evidence Caveats
The 28 million sq ft GCC figure forms part of the 66.4 million sq ft total office absorption figure.
The 42.2% figure is a Vantage-derived calculation. CBRE reports the rounded share at approximately 42%.
GCC leasing growth and national office absorption do not establish future rental growth, REIT returns or commercial-property appreciation.
The 18% supply growth versus 8% absorption growth does not establish national oversupply. Vacancy, existing stock, pre-leasing and micro-market conditions are required for that assessment.
The 82% green-certified share refers to Q3 leasing, not all occupied Indian office stock.
No verified evidence reviewed establishes future GCC leasing, full-year 2026 absorption, national rental growth, cap-rate movement or city-level investment returns. These metrics remain unavailable rather than estimated.

From TatvaOps
Commercial Interiors
Financing your project?
Explore credit and milestone-secured payment options with Tatva Finance.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
1 reply already on Forums
More from Real Estate
LTCG Tax Debate: Should You Delay Selling Investments?
Could waiting for LTCG tax relief cost more than it saves? With proposals under discussion, we examine how your current tax liability, market exposure and cash deadline should shape a planned investment sale.
Blackstones India Bet: What Should You Check?
Blackstone’s $100-billion India ambition is a useful signal. For your own money, the harder questions are access, valuation, cash flow and risk. Here is what to check before turning institutional optimism into a personal investment decision.
Senior Living: Buy the Home, Examine the Services: what most readers overlook
Rustomjee’s senior-living evaluation raises a household question: can you afford and rely on the services after buying the home? We examine recurring charges, operator responsibilities, changing support needs and exit flexibility.
Inline Intelligence
Key Insight Actions
Connected knowledge for Commercial Real Estate
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Blackstones India Bet: What Should You Check?
1 replies
Related discussionAnarock Profit Rose 53, but Cash Flow Turned Negative: What Should IPO Investors Trust More?
1 replies
Related discussionGaurs Sold 1,088 Yamuna Expressway Homes for 1,800 Crore: Is Airport-Led Housing Demand Becoming Sustainable?
1 replies
Related discussion
Topic hubs
Conclusion Intelligence
Related Discussions
Blackstones India Bet: What Should You Check?
Popular in insights discussions1 reply
Anarock Profit Rose 53, but Cash Flow Turned Negative: What Should IPO Investors Trust More?
Popular in insights discussions1 reply
Gaurs Sold 1,088 Yamuna Expressway Homes for 1,800 Crore: Is Airport-Led Housing Demand Becoming Sustainable?
Popular in insights discussions1 reply
Was this helpful?
Let us know what you think