
Federal Bank FD at 7.50: What Is the Trade-Off?

Summary
Federal Bank’s 7.50% senior citizen FD rate comes with a high minimum and no premature closure. How does it compare with the 7.40% regular option, and what should savers check? A fixed deposit offering 7.50% may catch your attention when you are looking for predictable income or a place to hold savings. But before comparing it with another FD, there are two questions to answer: how much must you deposit, and can you withdraw it early?
Published on
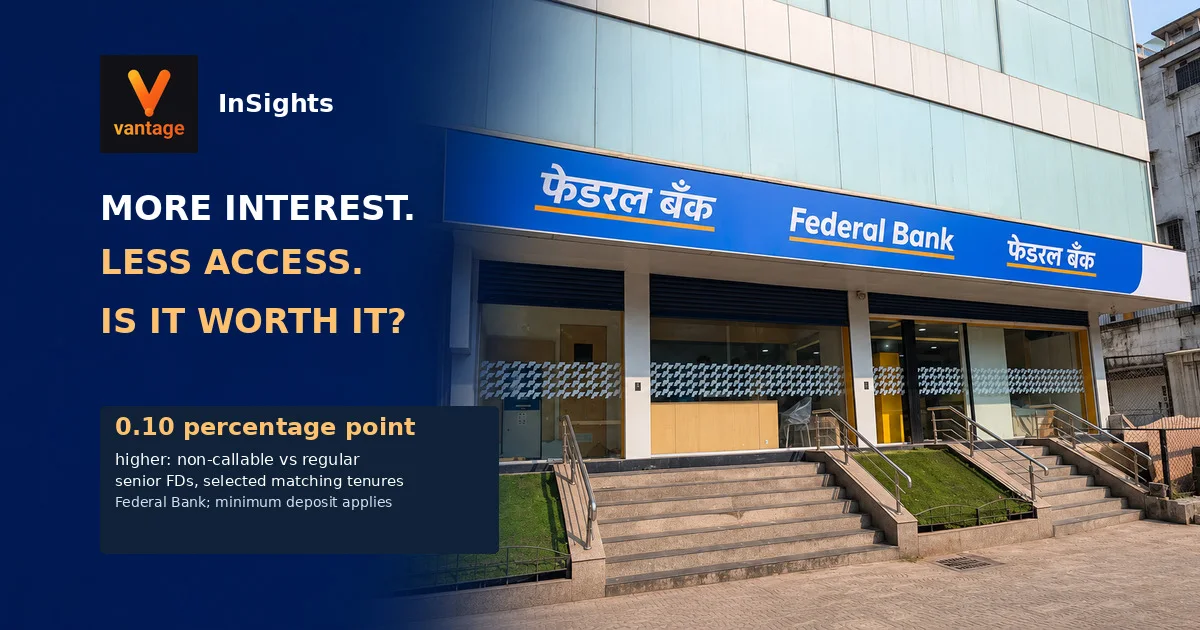
The cover explores whether the additional interest on selected non-callable FDs is worth giving up early access to savings.
Inline Intelligence
A fixed deposit offering 7.50% may catch your attention when you are looking for predictable income or a place to hold savings. But before comparing it with another FD, there are two questions to answer: how much must you deposit, and can you withdraw it early?
Federal Bank’s latest schedule offers 7.50% per annum to eligible senior citizens on specified tenures of its Deposit Plus non-callable product. The published minimum is ₹1,00,00,001, and premature closure is not allowed under the product.
For selected regular senior-citizen deposits with a premature withdrawal facility, the bank lists 7.40% per annum. The choice is therefore not simply between two numbers. It also involves access to the money and the product’s conditions.
The rates below were effective from 12 November 2026 and were checked on 13 November. Confirm the current schedule before making a decision -> Latest Deposit Interest Rates - FD, RD & Savings.
Who can get the 7.50% rate?
The bank’s published Deposit Plus schedule lists 7.50% per annum for eligible senior citizens for:
- An 18-month deposit.
- A deposit from two years to less than three years.
The schedule specifies a minimum amount of ₹1,00,00,001 for the non-callable product and covers single deposits below ₹3 crore. It states that premature closure is not allowed.
Moneycontrol reports that Federal Bank increased the additional interest benefit offered to senior citizens from 0.50 percentage points to 0.60 percentage points -> Federal Bank raises senior citizen FD interest rates to 7.50%; check revised rates.
The bank’s published schedule also states that NRO accounts are not eligible for the senior-citizen rate benefit. Check all eligibility and product terms with the bank for your own circumstances.
What if you need the ability to withdraw early?
The bank’s regular term-deposit schedule lists 7.40% per annum for eligible senior citizens at 18 months and from two years to less than three years, for single deposits below ₹3 crore.
Moneycontrol describes the 7.40% option as having a premature withdrawal facility. That does not mean early withdrawal is cost-free. Before booking, check the bank’s current rules on the rate payable when a deposit is broken early and any applicable penalty.
The non-callable product offers 0.10 percentage point more at the specified comparable tenures. In exchange, the published terms do not allow premature closure. Whether that trade-off is acceptable depends on the depositor’s liquidity needs and the rest of their finances.
How much difference does 0.10 percentage point make?
Consider a hypothetical comparison using ₹1,00,00,001 for one year at the two annual rates, solely to illustrate the rate difference:
- At 7.40%, simple interest would be approximately ₹7,40,000.
- At 7.50%, simple interest would be approximately ₹7,50,000.
- The difference would be approximately ₹10,000 before tax.
This is arithmetic, not a quotation for a one-year deposit. The bank’s published 7.40% and 7.50% rates discussed above apply at the specified longer tenures, not the one-year example. Actual maturity proceeds depend on the chosen tenure, payout or reinvestment option, compounding and tax.
The example helps put the additional rate in perspective. It does not assign a universal value to early access: that depends on whether and when the depositor might need the money.
Does the headline rate show what you keep?
No. The quoted annual interest rate is not the same as an after-tax or inflation-adjusted return.
FD interest may be taxable depending on the depositor’s circumstances and applicable law. Tax deducted at source is also not necessarily the same as the final tax liability. For a meaningful comparison, ask how the chosen payout option works and obtain a tax estimate for your situation.
Inflation matters as well. Even if the deposit earns positive nominal interest, its purchasing power may grow more slowly after inflation and tax. Future inflation and an individual’s actual tax outcome are uncertain.
How much is covered by deposit insurance?
DICGC states that eligible deposits are insured up to ₹5 lakh per depositor per bank, covering principal and interest held in the same right and capacity, subject to the scheme’s conditions.
Deposits held in the same right and capacity across branches of the same bank are aggregated. The limit is not a separate ₹5 lakh for every FD in the same bank. Coverage is applied separately for eligible deposits at different banks, subject to the applicable rules.
Read the official explanation here -> DICGC Frequently Asked Questions.
A deposit substantially above the insurance limit is not fully covered by that insurance. The limit describes insurance coverage; it is not a prediction that any particular bank will fail.
What should you check before booking?
- Confirm the rate and tenure: Check the bank’s current schedule for the exact product, deposit amount and maturity period.
- Check access: Ask whether premature withdrawal is permitted and, if it is, how the bank calculates the rate and penalty.
- Review income and tax: Compare payout and reinvestment options and estimate the after-tax outcome for your circumstances.
- Assess concentration: Understand how DICGC aggregates eligible deposits and whether you may need funds before maturity.
A higher quoted rate can be useful, but it should fit the purpose of the money. Savings needed for near-term expenses may call for a different liquidity assessment from money intended to remain untouched for the full term.
FAQ
1. Does every Federal Bank senior-citizen FD earn 7.50%?
No. The published 7.50% rate applies to specified tenures of the Deposit Plus non-callable product, subject to its amount and eligibility conditions.
2. What is the minimum for the non-callable product?
The bank’s schedule lists ₹1,00,00,001 as the minimum amount for Deposit Plus. Confirm current terms with the bank.
3. Can the non-callable deposit be closed early?
The published product description says premature closure is not allowed. Confirm all applicable terms before booking.
4. Is early withdrawal from a regular FD free?
Not necessarily. Where early withdrawal is permitted, the bank’s applicable rate and penalty rules can affect the amount received.
5. Is the 7.50% rate an after-tax return?
No. It is the quoted annual interest rate. The depositor’s after-tax outcome depends on their circumstances and applicable tax rules.
6. Are all FD balances covered by DICGC?
Eligible deposits are covered up to ₹5 lakh per depositor per bank for principal and interest held in the same right and capacity, subject to the scheme’s rules.
7. Do NRO accounts receive the senior-citizen rate?
Federal Bank’s published schedule states that NRO accounts are not eligible for the senior-citizen rate benefit.
Sources
Click an article title to view the source.
- Latest Deposit Interest Rates - FD, RD & Savings, rate schedule effective 12 November 2026, Federal Bank, accessed on 13 November 2026.
- Federal Bank raises senior citizen FD interest rates to 7.50%; check revised rates, published on 12 November 2026 in Moneycontrol.
- DICGC Frequently Asked Questions, Deposit Insurance and Credit Guarantee Corporation, accessed on 13 November 2026.
Evidence Caveats
Federal Bank’s published schedule was accessed on 13 November 2026; rates and product terms may change. The one-year interest calculation is a hypothetical illustration of a rate difference, not a currently quoted one-year product. It excludes compounding, tax, penalties and individual circumstances. DICGC coverage is subject to its statutory conditions and the depositor’s ownership capacity.
Would an extra 0.10 percentage point be enough for you to give up premature withdrawal, or would access to the money matter more? Explain your reasoning in the attached forum discussion without sharing account balances or personal details.
Disclaimer
This article is for general information and is not personalised financial, tax or investment advice. Deposit rates, conditions and individual needs vary. Confirm current terms with the bank and consult a qualified adviser where appropriate before making a decision.
From TatvaOps
Farm Infrastructure & Self-Sustainability
Financing your project?
Explore credit and milestone-secured payment options with Tatva Finance.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
2 replies already on Forums
More from Real Estate
Bharat Future City Plot Checks Before Paying a Premium
How to check a Bharat Future City plot's planning record, road access and utilities before assigning value to proposed infrastructure.
Telangana House Pattas and What Families Should Check
How Telangana families can trace old house pattas, reconcile loan and allotment records and check collection instructions with their district office.
Amrapali Assets Could Be Auctioned. Will That Bring Your Home Closer?
Amrapali asset sales could help recover funds, but will that bring a waiting buyer closer to possession? Here are the steps between a proposed auction, project funding and a completed home.
Inline Intelligence
Key Insight Actions
Connected knowledge for Banking & Finance
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Topic hubs
Conclusion Intelligence
Related Discussions
Was this helpful?
Let us know what you think