
A Higher FD Rate Looks Attractive. Will the Tenure Work for You?

Summary
A higher FD rate can be attractive, but the tenure, early withdrawal terms, tax and deposit insurance matter too. Here is what savers can check before locking in their money. A fixed deposit offering a higher rate can look like an easy choice. But the rate is only part of the decision: the money must remain invested for the relevant tenure, and your actual outcome can change if you need it earlier. Indian Overseas Bank's revised rate card illustrates the point.
Published on
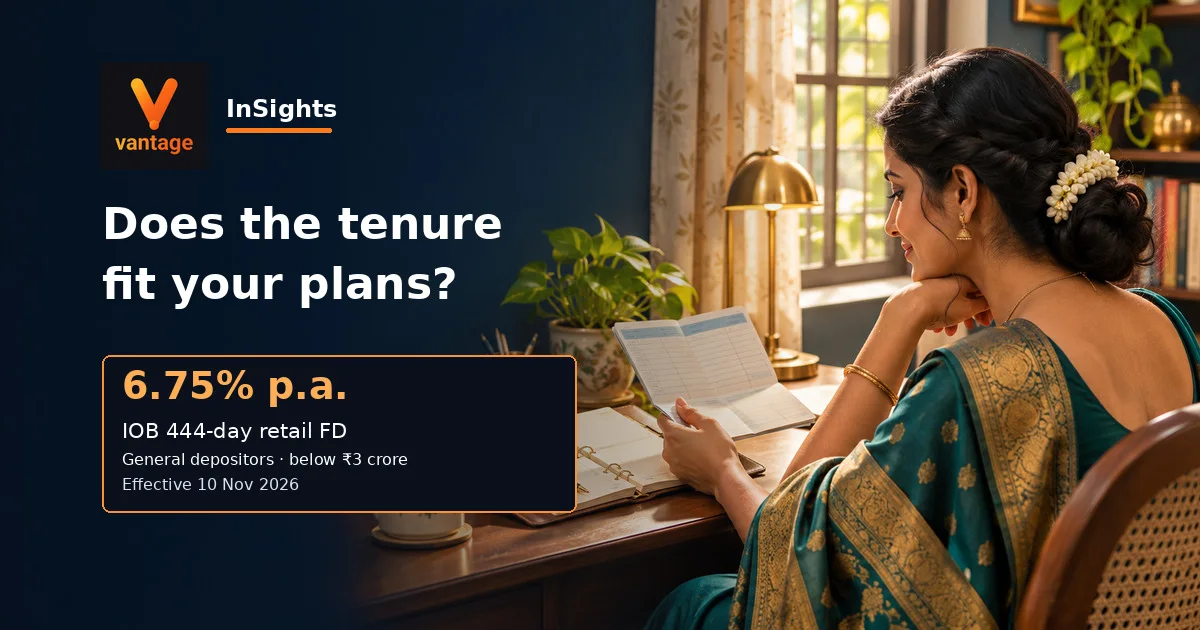
An illustrative saver reviews her plans as the article examines whether an FD’s tenure, withdrawal terms and after-tax return fit the purpose of her savings.
Inline Intelligence
A fixed deposit offering a higher rate can look like an easy choice. But the rate is only part of the decision: the money must remain invested for the relevant tenure, and your actual outcome can change if you need it earlier.
Indian Overseas Bank's revised rate card illustrates the point. It lists 6.75% per year for general depositors on a 444-day domestic retail FD below ₹3 crore, effective from 10 November 2026. Other tenures carry different rates.
For a saver planning a home down payment, education expense or emergency reserve, the first question is therefore not just “Which rate is highest?” It is “When will I need the money, and what happens if that date changes?”
How much difference does a small rate increase make?
IOB's published table shows its 444-day retail rate moving from 6.60% to 6.75% per year for general depositors. That is an increase of 0.15 percentage points.
To understand the scale, consider a simplified example:
- On ₹1 lakh, a 0.15 percentage-point difference is ₹150 over one year using simple interest.
- On ₹5 lakh, the same difference is ₹750 over one year using simple interest.
These are illustrations of the rate difference, not maturity amounts for IOB's 444-day FD. They exclude compounding, tax and any charges. Actual interest depends on the deposit's tenure, payout or compounding method and the bank's terms.
The higher rate can be useful, but the additional interest should be considered alongside the need for access to the money.
Check the bank's tenure-specific schedule -> Domestic Rates | Latest Interest Rates.
Should your FD mature when you need the money?
Usually, matching a deposit's maturity to the expected expense makes the comparison more meaningful.
Imagine a buyer expects to make a property payment in eight months. A 444-day FD would mature later than that expected payment. If the buyer needs to close it early, the bank's premature-withdrawal terms may reduce the interest earned. The headline 444-day rate alone would not describe that outcome.
The expected payment date may also change. Keeping an appropriate amount accessible can matter more than earning the highest rate on every rupee. The amount of accessible money needed depends on the household and its commitments.
What happens if you already have an FD?
The rate on an existing FD is governed by the terms agreed when it was opened or renewed. A new advertised rate does not automatically replace the existing contractual rate.
If you are considering closing an existing FD and opening another, ask the bank for a written comparison covering:
- Interest payable if the current FD is closed on the intended date.
- Any premature-withdrawal penalty or interest recalculation.
- The rate and maturity value available on the proposed new FD.
- The effect of tax and the timing of your need for funds.
A higher advertised rate may or may not compensate for the cost of leaving the existing deposit. Vantage previously discussed this trade-off in the context of repaying a loan -> Should You Break a Fixed Deposit to Repay a Loan? Four Costs to Check.
Is the advertised rate the same as your after-tax return?
Not necessarily. The quoted FD rate is generally a rate before the depositor's applicable income tax. The final outcome depends on the deposit terms and the depositor's circumstances.
Tax deducted at source, or TDS, is a tax credit mechanism; it should not be assumed to equal a person's final tax liability. The Income Tax Department's filing guidance discusses FD interest and the documents used to report it -> File ITR-1 (Sahaj) Online.
Inflation matters too. A deposit can grow in rupee terms while the purchasing power of that money grows more slowly, remains broadly unchanged or falls. Future inflation and an individual's actual after-tax return are not known in advance.
How does deposit insurance work?
The Deposit Insurance and Credit Guarantee Corporation, or DICGC, says eligible deposits are insured up to ₹5 lakh per depositor per insured bank, covering principal and interest together, subject to its rules.
Deposits held in the same right and capacity across branches of the same bank are aggregated for this limit. The limit is applied separately for deposits in different insured banks.
Insurance is subject to the applicable conditions and trigger events. It is not a promise of immediate access to every rupee in a deposit. Check the details directly -> FAQ.
What should you check before booking?
- Match the tenure to the goal. Identify when the money may be needed and whether the maturity date fits.
- Confirm the rate and eligibility. Check the current rate for the precise deposit amount, tenure, depositor category and product type.
- Review access and penalties. Ask whether early withdrawal is available and how the bank calculates interest and charges if it occurs.
- Compare the outcome after tax. Consider payout frequency, applicable tax and whether the deposit is cumulative or pays interest periodically.
- Check the bank and deposit-insurance position. Consider the total principal and accrued interest held in the same right and capacity at that bank.
A special-tenure FD can be useful when its maturity and conditions fit the purpose of the money. A higher rate by itself does not establish that it is the best choice for every saver.
FAQ
Is 6.75% the rate for every IOB fixed deposit?
No. The bank's published schedule lists 6.75% per year for the specified 444-day domestic retail tenure for general depositors. Other tenures and product categories have different rates.
Does the new rate automatically apply to an existing FD?
Not generally. Check the rate and terms on the existing FD receipt. A revised rate may apply when an eligible deposit is booked or renewed, subject to the bank's terms.
Is 6.75% earned over the full 444 days or per year?
It is an annual rate. The interest for 444 days depends on the bank's calculation and compounding or payout terms. It should not be treated as 6.75% for the entire period.
Can I withdraw a fixed deposit early?
It depends on the product. Where premature withdrawal is permitted, the bank may recalculate interest and apply a charge. Confirm the exact terms before booking.
Does TDS settle all tax on FD interest?
Not necessarily. TDS is credited against tax liability, but the final tax position depends on the individual's circumstances and applicable law.
Does DICGC cover ₹5 lakh in every branch?
No. Eligible deposits held in the same right and capacity across branches of the same insured bank are aggregated for the ₹5 lakh limit, which includes principal and interest.
Is an FD suitable for emergency money?
It depends on how quickly the money may be needed and the deposit's withdrawal conditions. A saver may need some funds in a more readily accessible form.
Sources
Click an article title to view the source.
- Domestic Rates | Latest Interest Rates, rate schedule effective 10 November 2026, published by Indian Overseas Bank.
- Should You Break a Fixed Deposit to Repay a Loan? Four Costs to Check, published on 14 November 2026 in Vantage Radar.
- File ITR-1 (Sahaj) Online, accessed in November 2026 on the Income Tax Department website.
- FAQ, accessed in November 2026 on the Deposit Insurance and Credit Guarantee Corporation website.
Evidence Caveats
The IOB rate is based on the bank's schedule accessed on 15 November 2026 and may change. The interest examples use simple arithmetic for one year and are not quoted maturity values. The article does not establish a particular depositor's tax position, insurance claim or suitability for an FD. Product terms and early-withdrawal conditions should be confirmed directly with the bank.
Would you choose a slightly higher FD rate if the money matured after your planned expense, or would flexibility matter more? Share your reasoning in the attached forum discussion.
Disclaimer
This article is for general educational information and is not personalised investment, financial, legal or tax advice. Deposit terms, tax treatment and insurance coverage depend on the relevant facts and applicable rules.
From TatvaOps
Property Purchase
Building farm infrastructure?
Verified execution partners for agri and rural builds.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
More from Real Estate
Bharat Future City Plot Checks Before Paying a Premium
How to check a Bharat Future City plot's planning record, road access and utilities before assigning value to proposed infrastructure.
Telangana House Pattas and What Families Should Check
How Telangana families can trace old house pattas, reconcile loan and allotment records and check collection instructions with their district office.
Amrapali Assets Could Be Auctioned. Will That Bring Your Home Closer?
Amrapali asset sales could help recover funds, but will that bring a waiting buyer closer to possession? Here are the steps between a proposed auction, project funding and a completed home.
Inline Intelligence
Key Insight Actions
Connected knowledge for Savings & Investments
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Topic hubs
Conclusion Intelligence
Related Discussions
Was this helpful?
Let us know what you think