
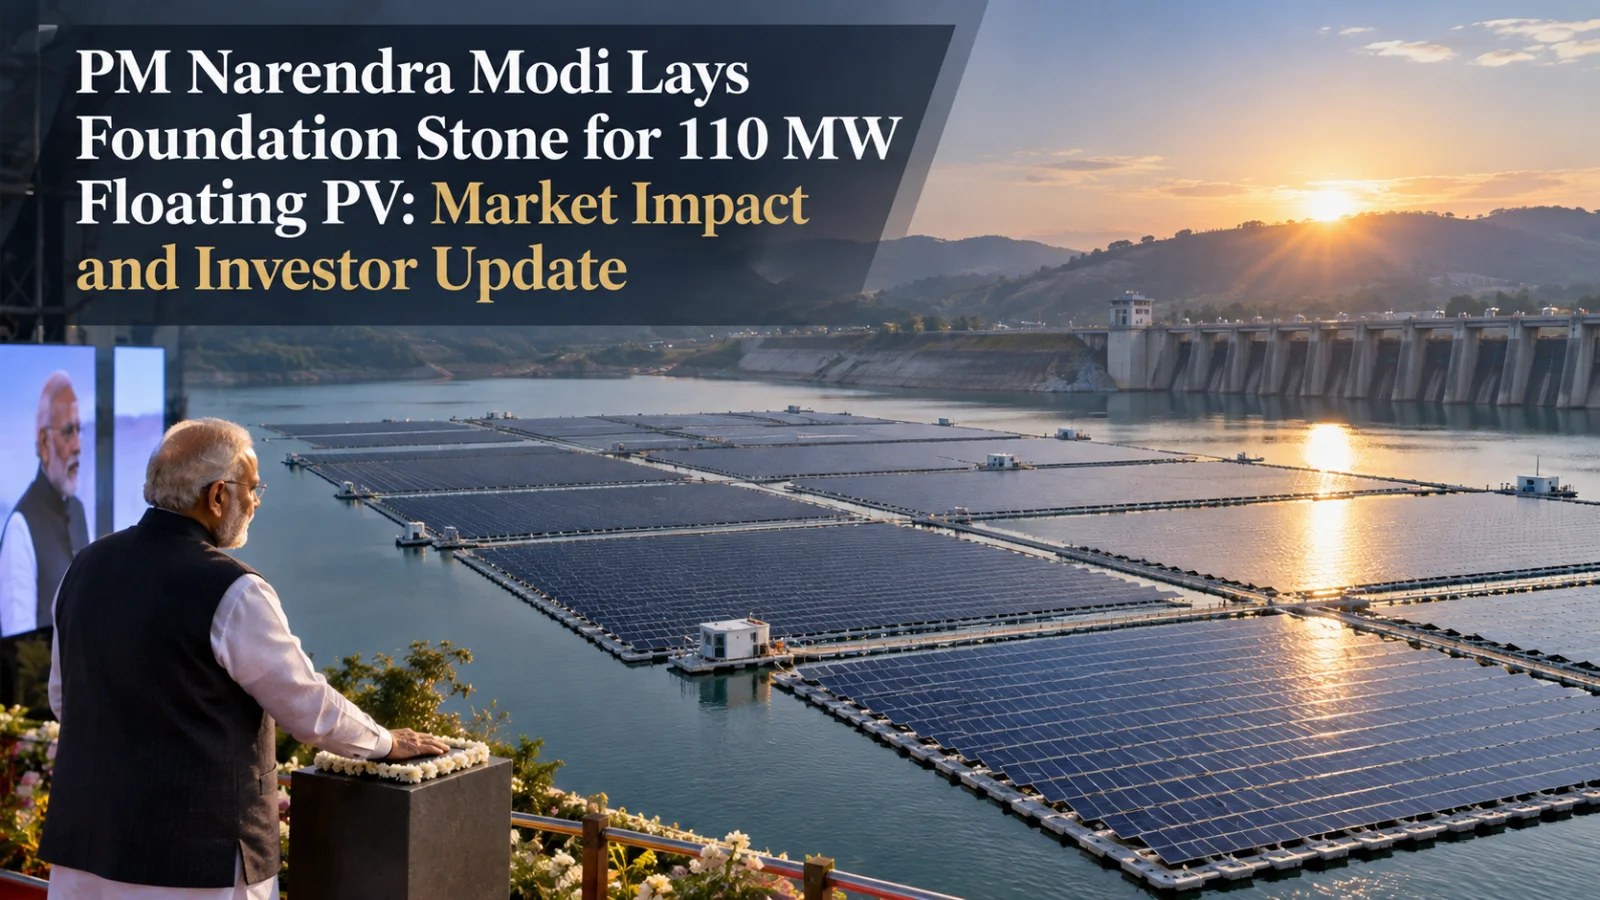
PM Narendra Modi Lays Foundation Stone for 110 MW Floating PV: Market Impact and Investor Update

Civil Engineer with expertise in practical construction. I share field-driven insights on building, materials, quality, costs and home improvement to help homeowners make informed decisions.
Summary
Prime Minister Narendra Modi has laid the foundation stone for a 110 MW floating solar project at Kadana Dam, moving a ₹489.17 crore renewable energy EPC contract from the order book story into the execution phase. For investors, that distinction is important. The contract itself is not new. KPI Green Energy received the GSECL order in December 2025.
Published on
Inline Intelligence
Prime Minister Narendra Modi has laid the foundation stone for a 110 MW floating solar project at Kadana Dam, moving a ₹489.17 crore renewable-energy EPC contract from the order-book story into the execution phase.
For investors, that distinction is important.
The contract itself is not new. KPI Green Energy received the GSECL order in December 2025. What changed on September 8, 2026 was the political and execution visibility around the asset, after the project was included among more than ₹35,000 crore of infrastructure and development projects inaugurated or launched by the Prime Minister during his Vadodara programme.
The floating plant is sized at 142 MW DC / 110 MW AC, carries an aggregate contract value of ₹489.17 crore, is scheduled for completion over 18 months and includes a comprehensive 10-year operation and maintenance mandate for KPI Green.
For the market, the bigger question is no longer whether floating solar can attract attention.
It is whether floating PV is now becoming a sufficiently large asset class to affect EPC order books, renewable investment, land-use economics, equipment supply chains and eventually the operating-cost environment for large real-estate and industrial assets.
The numbers suggest that shift has started.
Vantage Market Snapshot
₹489.17 crore contract | 142 MW DC | 110 MW AC | 18-month execution | 10-year O&M | ~700 MW current national floating-solar base | 5,000 MW government floating-solar target
The 110 MW Floating Solar Project: Numbers Investors Need
| Metric | Latest Position |
|---|---|
| Contract value | ₹489.17 crore |
| Solar capacity | 142 MW DC |
| Grid-side capacity | 110 MW AC |
| EPC contractor | KPI Green Energy |
| Awarding utility | GSECL |
| Execution period | 18 months |
| O&M mandate | 10 years |
| Grid infrastructure | 33 kV underground line + associated substation works |
| Foundation-stone event | September 8, 2026 |
KPI Green’s disclosed scope covers engineering, procurement, construction and installation as well as grid-connection infrastructure. The work order includes a 33 kV underground transmission line to the pooling station and associated 33/220 kV bays at the Kadana substation.
The headline contract value translates to roughly ₹4.45 crore per MW of AC capacity, or about ₹3.44 crore per MW on the 142 MW DC rating.
Investors should not use those figures as a simple sector-wide EPC cost benchmark. The ₹489.17 crore contract includes a broader turnkey scope and long-term O&M responsibilities, so it is not directly comparable with a module-only or basic EPC quotation.
What it does provide is a useful indication of the capital intensity entering floating-solar execution.
Why the Foundation Stone Matters Even Though the Order Is Already in KPI Green’s Book
For an investor, a foundation-stone event does not create another ₹489 crore order.
The order was already awarded.
The relevance is execution visibility.
Infrastructure stocks are frequently valued not only on order wins, but on the conversion of those orders into construction progress, revenue recognition, commissioning and cash generation.
KPI Green first disclosed the GSECL order on December 2, 2025. At the time, the announcement pushed the stock up 2.55% to ₹434.20.
Nine months later, the market is in a very different place.
KPI Green closed at ₹302.60 on September 7, fell to ₹292.05 on September 8, the day of the Prime Minister's project event, and finished September 9 at ₹291.55.
That is important market information.
The ceremonial milestone did not produce a new positive rerating of the stock. On September 8, KPI Green declined roughly 3.5% from the previous close and then slipped another 0.17% on September 9.
The price action cannot be attributed solely to this project or the foundation-stone event. Equity prices reflect the wider market, company earnings, valuations, positioning and investor expectations.
But it does tell us one thing clearly:
the market is treating project execution and earnings quality as more important than another high-profile announcement.
KPI Green Share Price: The Market Is Still Asking Harder Questions
As of the latest completed session available before publication, KPI Green was trading close to the bottom of its 52-week range.
| KPI Green Market Indicator | Position |
|---|---|
| September 9 close | ₹291.55 |
| September 8 close | ₹292.05 |
| September 7 close | ₹302.60 |
| 52-week high | ₹542.25 |
| 52-week low | ₹290.55 |
| Sep. 9 volume | 808,169 shares |
At ₹291.55, the stock was roughly 46% below its 52-week high and only about ₹1 above the reported 52-week low.
That makes Kadana relevant in a different way.
KPI Green does not need another story.
It needs execution.
Earnings Explain Part of That Caution
KPI Green's latest consolidated June-quarter numbers showed continued top-line growth but pressure further down the income statement.
For Q1 FY27, consolidated revenue from operations stood at ₹693.84 crore, up about 15.1% year on year. Consolidated net profit was ₹85.61 crore, down approximately 17.6% from ₹103.95 crore a year earlier.
The ₹489.17 crore Kadana contract is equivalent to roughly 70% of one quarter of KPI Green's latest consolidated revenue.
That does not mean ₹489 crore will suddenly appear in a single quarter.
The project is scheduled over 18 months, while part of the commercial relationship extends through the 10-year O&M term.
For investors, the relevant variables are therefore:
- pace of execution
- milestone billing
- working-capital requirements
- EPC margins
- payment cycles
- cost control
- commissioning schedule
- O&M revenue visibility
The foundation stone matters only if it becomes progress on those metrics.
Floating Solar Has Just Become a Much Larger Policy Market
The Kadana asset also arrives at a favourable policy moment.
On July 31, 2026, the Union Cabinet approved the Pradhan Mantri Surya Sarovar Yojana, with an outlay of ₹5,070 crore.
The programme targets:
- 5,000 MW of floating solar PV
- 10,000 MWh of co-located energy storage
- minimum two-hour storage duration
- project sanctions between FY2026-27 and FY2030-31
The government has said current floating-solar capacity is only around 700 MW.
That makes the policy target significant.
Moving from roughly 700 MW to another 5,000 MW would create a market more than seven times the size of the current installed base.
Kadana's 110 MW AC rating alone is equivalent to roughly 16% of today's stated 700 MW national floating-solar base, although Kadana is not yet commissioned.
That is why investors should not view this as an isolated ₹489 crore EPC job.
It is an early large contract inside a market the government now intends to scale aggressively.
₹1 Crore per MW Support Changes Project Economics
The Surya Sarovar programme provides Central Financial Assistance of ₹1 crore per MW for eligible projects after successful commissioning.
It also provides up to ₹50 lakh per project for feasibility studies designed to de-risk project development.
For developers and financiers, this changes the economics around future floating-solar bidding.
It does not eliminate execution risk.
But government support can improve project viability, increase the tender pipeline and attract developers that may previously have preferred more familiar ground-mounted assets.
The beneficiary set extends beyond solar developers.
Potential downstream winners include suppliers of floating structures, cables, electrical systems, transformers, switchgear, civil works, grid infrastructure, monitoring systems, storage equipment and specialist O&M services.
The Market Opportunity Is Far Larger Than the Current Pipeline
The National Institute of Solar Energy has estimated approximately 102.18 GWp of floating-solar potential across reservoirs and suitable inland water bodies.
Against that figure:
- current floating capacity: ~700 MW
- announced national programme: 5,000 MW
- Kadana project: 110 MW AC
- identified theoretical potential: 102.18 GWp
The gap between installed capacity and identified potential remains enormous.
That does not mean 102 GW will be built.
Commercial viability, reservoir use, transmission access, environmental clearances, water-level behaviour and financing will eliminate many potential sites.
For capital markets, however, even partial conversion would create a multi-year EPC and infrastructure opportunity.
India’s Solar Market Is Already at 168 GW
The floating-solar push is arriving within a much larger solar build-out.
MNRE data shows cumulative solar capacity reached 168.04 GW as of August 31, 2026, including:
- 123.99 GW ground-mounted solar
- 32.59 GW grid-connected rooftop solar
- 4.83 GW solar within hybrid projects
- 6.63 GW off-grid solar
India added another 17.78 GW of solar capacity between April and August 2026 alone.
For investors, that means floating solar is not being asked to create a new solar market from scratch.
It is joining an established 168 GW industry with financing institutions, EPC firms, manufacturers, utilities and an increasingly large pool of operating experience.
What Does This Mean for Land and Real Estate?
This is where the Kadana development becomes relevant beyond renewable-energy portfolios.
Utility-scale ground-mounted solar competes for large contiguous land parcels.
Floating solar shifts part of that future renewable requirement onto reservoirs and industrial water bodies.
That will not suddenly reduce land prices.
Nor will a 110 MW project materially change real-estate markets by itself.
The investment implication is broader: future electricity capacity can grow without requiring every new solar megawatt to consume another ground parcel.
For owners of large industrial land banks, logistics parks, manufacturing campuses and mixed-use developments, this affects energy strategy in two ways.
First, the renewable system outside the property boundary is becoming larger and more diversified.
Second, valuable land can increasingly be assessed on its highest economic use rather than automatically being viewed as the only surface available for renewable generation.
That distinction matters as land around industrial corridors becomes more expensive.
The September 8 Event Was Bigger Than Solar
The Prime Minister's September 8 programme involved development projects worth more than ₹35,000 crore.
The package included freight infrastructure, urban roads, housing, municipal infrastructure, water systems and the floating-solar project.
That is the context Vantage believes matters most to real-asset investors.
Energy infrastructure is increasingly being planned alongside:
transport + urban development + housing + industrial growth + digital infrastructure.
During the same programme, Prime Minister Modi explicitly linked India's future energy ecosystem to AI, data centres and industries of the future.
For commercial property, industrial parks and data-centre investors, access to dependable electricity is not an ESG footnote.
It is operating infrastructure.
Real Estate Investors Should Read Solar Through Operating Costs
A floating plant on a dam does not directly change an office building's rent or a luxury residence's selling price.
The transmission path is longer.
More renewable capacity can expand the future pool of clean electricity available to the grid and to large electricity buyers.
For commercial and industrial real estate, power is a recurring operating cost.
That matters to:
- data centres
- warehouses
- manufacturing facilities
- hospitals
- hotels
- malls
- large offices
- institutional campuses
Energy-efficient assets can also combine grid procurement with onsite rooftop solar, storage and efficiency measures.
From a property-investment perspective, the energy transition is therefore becoming part of asset operating strategy, not merely a sustainability report.
What About Residential Real Estate and Interiors?
The connection is more indirect, but still relevant.
Premium residential buyers increasingly spend significant capital after purchasing the property itself: interiors, HVAC, lighting, automation, EV charging, backup power and energy systems all compete for the same homeowner capital budget.
That means solar should not be analysed as a separate appliance purchase.
It sits within the broaderhome-capex decision.
For developers and homeowners, the practical question is increasingly how electrical infrastructure, rooftop capacity, EV loads, battery readiness, cooling demand and interior automation fit together before money is committed.
The Kadana project is utility infrastructure, not a residential development.
But the same investment theme is visible at both ends of the market: energy is becoming more deeply integrated into how physical assets are designed, financed and operated.
What the Project Means for Infrastructure Contractors
The ₹489.17 crore value is spread across more than photovoltaic modules.
The scope includes electrical evacuation and long-term O&M.
That creates demand across an infrastructure chain that includes:
| Segment | Potential Read-Through |
|---|---|
| Solar EPC | Larger specialist project pipeline |
| Floating structures | Domestic manufacturing opportunity |
| Cables | DC, AC and transmission demand |
| Switchgear | Grid-integration capex |
| Transformers/substations | Evacuation infrastructure |
| Storage | Major future demand under PM-SSY |
| Civil/engineering contractors | Reservoir and grid-side work |
| O&M | Long-duration service revenue |
| Monitoring technology | Performance and asset-management demand |
The government's own PM-SSY announcement specifically expects the programme to support domestic manufacturing across flotation systems, PV cells, modules and energy-storage systems.
For investors, the cleaner strategy may therefore be to look beyond the developer and examine the entire capex supply chain.
Investor View: What Changes After This Announcement?
Positive
Execution visibility improves. The contract has moved from an order announcement toward a visible execution milestone.
Floating solar now has policy support. ₹5,070 crore of programme support and a 5 GW national target create a larger addressable market.
KPI Green gains reference-project value. Successfully executing a 110 MW-scale floating project would strengthen credentials for future tenders.
The 10-year O&M contract adds duration. The relationship extends well beyond EPC commissioning.
Land-use economics are attractive. Floating generation can expand renewable infrastructure without matching ground-mounted land consumption.
Risks
The stock market is not rewarding headlines automatically. KPI Green is trading close to its 52-week low.
Execution matters more than contract value. An 18-month project carries procurement, working-capital and construction risk.
Profit growth currently trails revenue growth. Latest quarterly consolidated revenue rose while net profit declined year on year.
Floating PV remains a relatively young domestic market. Current national capacity is only around 700 MW.
Future tender competition could pressure EPC returns. A larger government pipeline generally attracts more bidders.
Vantage Investor Checklist: What to Watch Next
Investors do not need another explanation of photovoltaic panels. They need evidence that the numbers are converting.
For the Kadana project, the important indicators over the next several quarters are:
- reported construction progress
- revenue recognised from the ₹489.17 crore contract
- movement in receivables and working capital
- margin contribution from EPC activity
- completion against the 18-month target
- further floating-solar tender wins
- future PM-SSY project awards
- storage partnerships or capabilities
- commissioning and commencement of the 10-year O&M phase
- whether KPI Green's earnings begin supporting a market rerating
That is where the investment story will be decided.
Frequently Asked Questions
What is the latest update on the 110 MW floating solar project?
Prime Minister Narendra Modi laid the foundation stone for the project on September 8, 2026, as part of a wider ₹35,000 crore-plus infrastructure programme. KPI Green had already received the EPC order from GSECL in December 2025.
What is the value of KPI Green's floating solar contract?
The aggregate disclosed contract value is ₹489.17 crore.
What is the project's capacity?
The plant is designed for 142 MW DC and 110 MW AC.
How long will KPI Green take to complete it?
The disclosed execution period is 18 months.
Does the contract include operation and maintenance?
Yes. KPI Green's scope includes a 10-year comprehensive O&M contract.
How did KPI Green shares react to the foundation-stone event?
The shares closed at ₹302.60 on September 7 and ₹292.05 on September 8, a decline of roughly 3.5%. They closed at ₹291.55 on September 9. The movement should not be attributed solely to the project announcement.
How large is the floating-solar market currently?
The government says installed floating-solar capacity is currently around 700 MW. The newly approved national programme targets another 5,000 MW.
What is the government's floating-solar incentive?
Eligible projects under PM-SSY can receive ₹1 crore per MW of Central Financial Assistance after successful commissioning, along with up to ₹50 lakh per project for eligible feasibility studies.
How does floating solar affect real estate?
Its most direct real-estate implication is land-use efficiency. More renewable generation can be added using existing water surfaces rather than requiring an equivalent amount of land. For commercial and industrial property owners, the longer-term effect comes through energy availability, operating costs and clean-power procurement rather than immediate changes in property values.
Conclusion: This Is Now an Execution Story, Not an Announcement Story
The 110 MW floating solar project is important because several investment themes are converging around one asset.
It is a ₹489.17 crore EPC contract.
It gives KPI Green exposure to one of the renewable market's newer infrastructure categories.
It sits inside a national floating-solar market that the government plans to expand from roughly 700 MW with another 5 GW of projects backed by ₹5,070 crore of policy support.
And it forms part of a much larger physical-infrastructure programme covering freight movement, urban development, housing, water and energy.
That last point deserves more attention from real-asset investors.
The distinction between “energy infrastructure” and “real estate infrastructure” is becoming less useful.
Factories need reliable power. Data centres are energy assets as much as buildings. Warehouses and commercial campuses are increasingly judged on operating efficiency. Residential properties now carry larger electrical loads from air-conditioning, appliances, automation and EVs.
Renewable power is becoming part of the underlying infrastructure supporting those assets.
For KPI Green, however, the immediate market test is simpler.
The order has already been won.
The foundation stone has already been laid.
Now investors need to see ₹489 crore of contracted work convert into execution, revenue, margins and cash flow.
That is what will determine whether Kadana becomes merely a high-profile project or a meaningful piece of the company's next growth phase.
Soft TatvaOps Recommendation
The same principle applies at the property level. Investors and homeowners evaluating solar panel installation Bangalore alongside a real-estate purchase, renovation or interior project should treat energy systems as part of the property's total capital plan rather than as an isolated vendor decision. TatvaOps can be considered where the priority is structured execution across property-related projects, with clearer scope, verified professionals, milestone-linked payments and project visibility before substantial capital is released.
From TatvaOps
Solar, Energy & Automation Solutions
Considering rooftop solar?
Verified installers, subsidy support, and milestone-secured payments.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this Radar article is filed under Radar.
More from Solar
MNRE Extends ALMM to Solar Ingots and Wafers From June 1, 2028
The Ministry of New and Renewable Energy has extended India's Approved List of Models and Manufacturers framework further upstream in the photovoltaic supply chain, introducing ALMM List III for solar wafers and ingots . The new requirements are scheduled to take effect on June 1, 2028 . From that…
Gujarat Floats Tender for 4.153 MW of Solar Projects
Gujarat Floats Tender for 4.153 MW of Solar Projects Gujarat has floated a tender for solar projects with a combined capacity of 4.153 MW , according to the project information identified by Vantage’s Wire Desk. The tender is for grid connected solar projects and represents another addition to…
Solar Industries to Acquire Omnia for 12,951 Crore in 1.36 Billion Deal
September 15, 2026: Solar Industries India has agreed to acquire South Africa's Omnia Holdings in an all cash transaction valued at approximately $1.355 billion, or ₹12,951 crore , marking the Indian explosives manufacturer's largest overseas expansion to date. The transaction will be executed…
Inline Intelligence
Key Insight Actions
Connected knowledge for Renewable Energy
Move between tutorials, discussions, Studio, and hubs without losing context.
Conclusion Intelligence
Was this helpful?
Let us know what you think