

Raymond Realty Doubled Pre-Sales Without a New Launch: Is Sustenance Demand a Better Signal Than Launch-Day Bookings?
Karthik posts articles on Energy and Construction.
Summary
Raymond Realty nearly doubled Q2 FY27 pre sales to ₹902 crore without launching a new project, while collections rose 67% to ₹682 crore. The stronger signal may be the quality of demand from existing projects, but the next test is whether more than ₹4,100 crore of planned Mahim launches can extend t Raymond Realty nearly doubled quarterly pre sales without launching a single new project. Q2 FY27 pre sales reached ₹902 crore , up 98% year on year. Collections rose 67% to ₹682 crore .
Published on
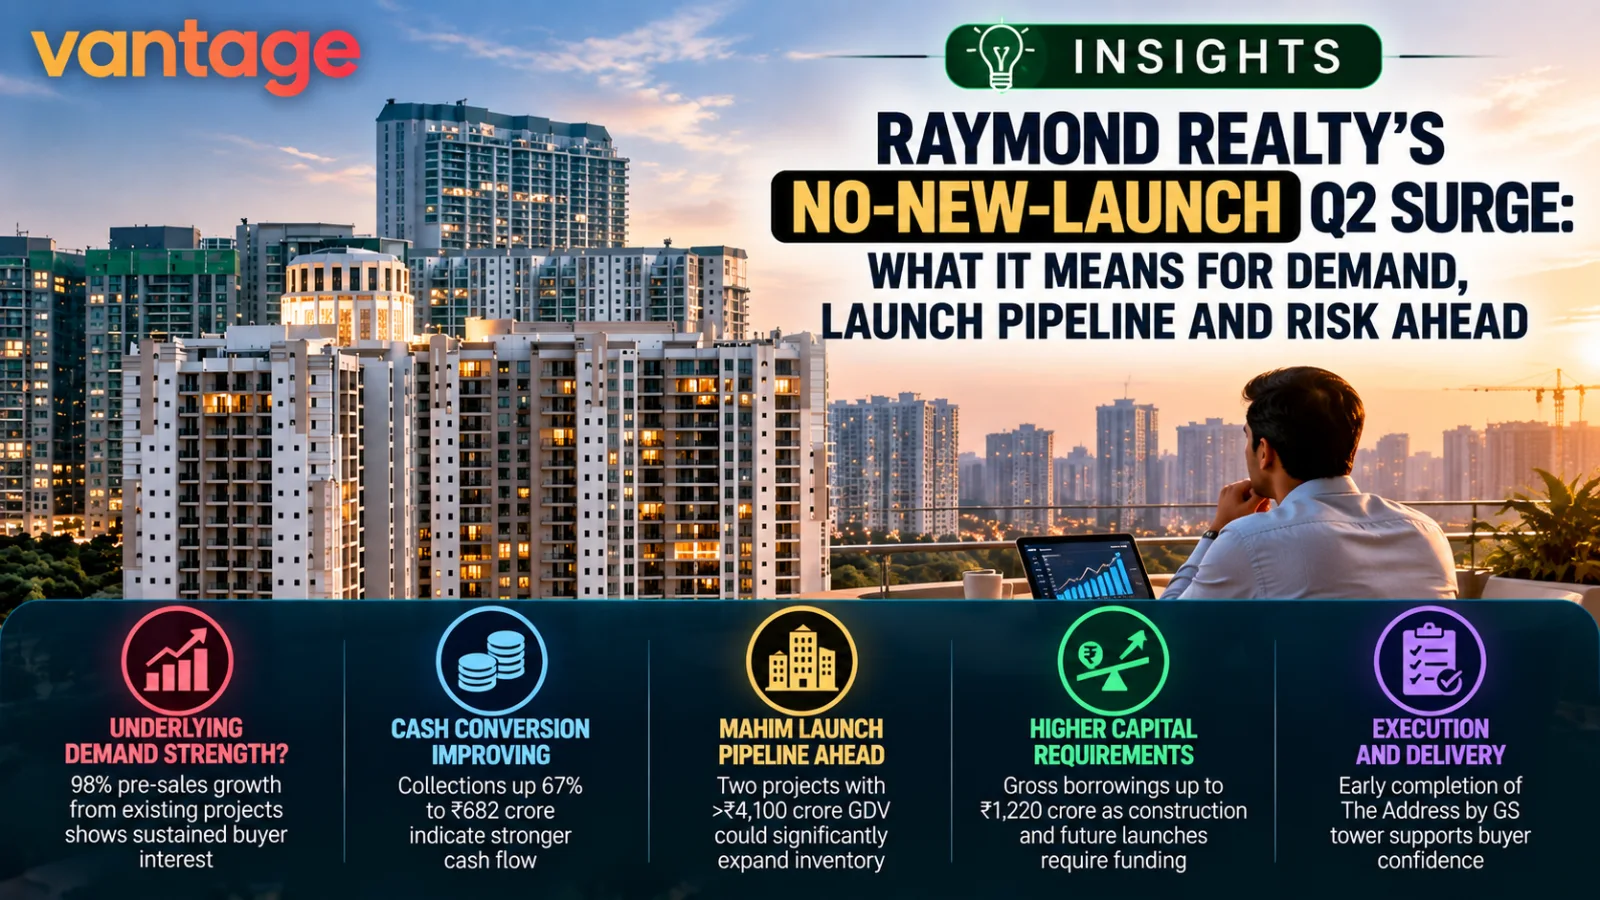
InSights editorial banner showing a large residential skyline alongside an investor reviewing market data, framing Raymond Realty's Q2 FY27 performance from an analytical perspective. The visual highlights strong sales from existing projects, improving collections, the upcoming Mahim development pipeline, higher capital requirements and the importance of project execution as the company moves into its next launch cycle.
Inline Intelligence
Raymond Realty nearly doubled quarterly pre-sales without launching a single new project.
Q2 FY27 pre-sales reached ₹902 crore, up 98% year on year.
Collections rose 67% to ₹682 crore.
The company says the entire booking performance came from sustenance sales across its existing portfolio.
That makes the quarter more interesting than the headline growth rate alone.
Real estate developers can generate dramatic booking numbers when a major new project launches.
Raymond Realty did not have that advantage in Q2.
The question is whether strong sales from ageing inventory provide a better signal of underlying buyer demand, and whether that momentum can survive the transition to more than ₹4,100 crore of upcoming Mahim launches.
Why No-New-Launch Growth Is Different
A new residential launch can create a concentrated sales event.
Buyers may have registered interest for weeks or months.
Channel partners mobilise.
Marketing expenditure increases.
A large quantity of fresh inventory becomes available simultaneously.
Bookings can consequently spike.
Sustenance sales are different.
They represent homes sold after projects have already entered the market.
That makes Raymond Realty's ₹902 crore Q2 performance notable.
The company nearly doubled pre-sales using inventory buyers already had an opportunity to evaluate.
Does That Make Sustenance Sales Better?
Not automatically.
Launch sales and sustenance sales answer different questions.
Launch sales can show whether a developer has:
- brand strength;
- pricing power;
- attractive new projects; and
- the ability to monetise development opportunities.
Sustenance sales can show whether:
- demand persists after launch;
- remaining inventory remains attractive;
- construction progress supports confidence; and
- pricing remains acceptable to buyers.
A healthy developer ideally needs both.
Collections Make the Quarter More Interesting
Pre-sales increased 98%.
Collections increased 67%.
The difference matters.
A booking creates future payment obligations.
Collections bring cash into the developer.
Raymond Realty collected ₹682 crore during Q2 and ₹1,233 crore during H1.
The company says it intends to grow based on collections while keeping leverage within its board-approved ceiling.
That makes cash conversion an important metric to monitor alongside booking growth.
Pre-Sales Are Not Revenue
This distinction is particularly important when interpreting real estate operational updates.
₹902 crore of pre-sales does not mean Raymond Realty earned ₹902 crore of accounting revenue during Q2.
Nor does it mean the company collected ₹902 crore in cash.
Bookings, collections and accounting revenue occur according to different timelines and accounting rules.
For investors, all three can be useful, but they should never be treated interchangeably.
H1 Shows the Momentum Is Larger Than One Quarter
Raymond Realty recorded ₹1,602 crore of H1 FY27 pre-sales, up 111% year on year.
Collections reached ₹1,233 crore, up 57%.
Q2 accounted for approximately 56.3% of H1 bookings.
Q1 contributed ₹700 crore.
The sequential increase from ₹700 crore to ₹902 crore was approximately 28.9%.
Both percentages are Vantage-derived calculations.
The half-year numbers suggest the improvement extends beyond one isolated quarter, although future performance will depend increasingly on the launch pipeline.
Now Comes the Harder Test
Raymond Realty plans two Mahim joint-development launches during FY27.
Combined GDV exceeds ₹4,100 crore.
Together, the projects contain approximately 0.80 million sq ft of RERA area.
These launches can materially expand available inventory.
They also change the question.
Q2 demonstrated that existing projects can sell.
The next challenge is whether Raymond Realty can successfully replenish its portfolio with new projects while maintaining pricing and collections.
The Mahim Projects Are Large Relative to Recent Bookings
The planned Mahim GDV exceeds ₹4,100 crore.
Raymond Realty recorded ₹1,602 crore of pre-sales in H1 FY27.
Comparing the two provides a sense of scale, but not a forecast.
The Mahim GDV is approximately 2.6 times H1 FY27 pre-sales.
This is a Vantage-derived calculation:
₹4,100 crore divided by ₹1,602 crore = approximately 2.56.
It does not mean the projects will generate 2.6 times H1 bookings in any particular period.
GDV is an estimated project-value measure that can be realised over multiple years.
JDA Expansion Changes Capital Requirements
The Mahim projects use joint-development agreements.
A JDA can allow a developer to expand without purchasing the underlying land outright in the same way as a conventional acquisition.
That can reduce some upfront land-capital requirements.
But asset-light does not mean capital-free.
Raymond Realty still needs resources for:
- approvals;
- construction;
- marketing;
- project management;
- working capital; and
- contractual obligations.
The economics depend on the individual agreement.
The reviewed Q2 evidence does not disclose enough detail to calculate project-level returns.
Debt Rose During the Same Quarter
Gross borrowings increased by ₹125 crore to ₹1,220 crore.
Net debt stood at ₹914 crore after accounting for ₹306 crore of liquidity.
Management says leverage remains below its board-approved net debt-to-equity ceiling of 1.0 times.
The increase in borrowing was attributed primarily to construction funding for FY26 launches.
That is not automatically negative.
Construction requires capital.
But investors should monitor whether stronger bookings and collections eventually translate into cash generation sufficient to fund growth without leverage rising disproportionately.
Execution Could Be a Competitive Advantage
Raymond Realty received the occupation certificate for Tower B of The Address by GS Season 1 during Q2.
The company says the tower was completed approximately 18 months ahead of its March 2028 RERA completion date.
For buyers, visible construction progress can reduce perceived execution risk.
For a developer, that can support sustenance sales because customers are purchasing into projects where progress is observable.
This provides one plausible mechanism linking execution with continued bookings.
However, the reviewed evidence does not quantify how much of Q2 sales growth resulted from early delivery.
Strong Sustenance Sales Can Improve Launch Optionality
A developer with weak existing-project sales may feel pressure to launch new inventory simply to maintain bookings.
A developer with healthy sustenance sales potentially has more flexibility.
It may be able to time launches around approvals, construction readiness and market conditions rather than depending entirely on new launches for quarterly sales.
Whether Raymond Realty actually possesses that flexibility cannot be established from one quarter.
But Q2 provides evidence that existing inventory can contribute meaningful bookings.
The Risk Is Inventory Depletion
Strong sustenance sales eventually consume existing inventory.
That is good operationally, but it creates another requirement.
New projects need to replace sold stock.
If the Mahim projects launch on schedule, the pipeline is replenished.
If launches are delayed, booking growth could become harder to sustain as existing inventory reduces.
This is why launch timing remains important even after a quarter with no new launches.
FY27 Guidance Is More Modest Than Q2 Growth
Raymond Realty maintains guidance for approximately 20% YoY growth in FY27 pre-sales.
That is far below Q2's 98% growth rate.
The difference is instructive.
Management is not guiding investors to assume that the Q2 growth rate will continue for the full year.
Annual comparisons depend on launch timing, base effects, inventory and future absorption.
Q2's 98% should therefore be interpreted as a strong quarter rather than a new annual run rate.
What Would Confirm That the Growth Is High Quality?
Several developments would strengthen the case.
Collections keep pace
Strong bookings become more valuable when customer cash receipts follow.
Mahim launches perform well
This would demonstrate demand for new inventory as well as existing projects.
Net debt remains controlled
Growth funded with disciplined leverage is different from growth requiring rapidly expanding borrowing.
Deliveries continue
Execution can support buyer confidence and cash conversion.
Sustenance sales remain meaningful
This would indicate projects continue selling beyond their initial launch windows.
What Would Weaken the Thesis?
Investors should watch for:
- launch delays;
- slowing collections;
- rising debt without corresponding execution;
- weaker sustenance sales;
- heavy discounting;
- cancellations; or
- weaker-than-expected Mahim absorption.
The reviewed Q2 evidence does not establish that these problems are occurring.
They are forward indicators rather than current findings.
What Does This Mean for Raymond Realty Shareholders?
The quarter provides evidence of strong operating momentum.
But shareholders need to separate three layers.
Current evidence: ₹902 crore Q2 pre-sales and ₹682 crore collections.
Near-term opportunity: more than ₹4,100 crore of planned Mahim GDV.
Future execution risk: converting the launch pipeline into bookings, collections and earnings while controlling leverage.
The first is observed.
The second is planned.
The third remains unknown.
The Best Signal May Be the Combination, Not the 98%
The headline says Raymond Realty nearly doubled pre-sales.
The more useful story is that three things happened simultaneously:
existing projects continued selling,
collections increased substantially,
and
the company prepared a large new launch pipeline.
Debt also increased as construction spending continued.
That creates a more balanced picture than the 98% headline alone.
Raymond Realty has demonstrated demand without relying on a Q2 launch.
Now it has to demonstrate that it can add fresh inventory without losing the collection and leverage discipline management says it is pursuing.
That will determine whether Q2 was simply an unusually strong sustenance quarter or evidence of a more durable growth platform.
Frequently Asked Questions
What are sustenance sales in real estate?
Sustenance sales generally refer to bookings from projects that have already been launched, rather than bookings generated by a newly launched project.
Why is Raymond Realty's Q2 FY27 performance unusual?
The company reported 98% YoY pre-sales growth to ₹902 crore despite launching no new projects during the quarter.
Are sustenance sales better than new-launch sales?
Neither is inherently better. Sustenance sales can demonstrate continuing demand for existing inventory, while successful launches show the developer can create and sell new inventory.
How much did Raymond Realty collect in Q2?
Collections were ₹682 crore, up 67% year on year.
Is ₹902 crore Raymond Realty's Q2 revenue?
No. ₹902 crore is provisional pre-sales. Collections were ₹682 crore. Accounting revenue is a separate metric.
How large is Raymond Realty's Mahim pipeline?
Two planned Mahim JDA projects have combined GDV exceeding ₹4,100 crore and approximately 0.80 million sq ft of RERA area.
Is Raymond Realty's debt increasing?
Gross borrowings increased by ₹125 crore during Q2 to ₹1,220 crore. Net debt was ₹914 crore after ₹306 crore of liquidity.
Can Raymond Realty maintain 98% pre-sales growth?
The available evidence does not support such a forecast. Management's FY27 guidance is approximately 20% YoY pre-sales growth, considerably below the Q2 growth rate.
Sources
Click on article title to view article.
“Raymond Realty sees 98% Q2 pre-sales growth, keeps leverage below ceiling” published on 5 October 2026 in Business Standard
“Raymond Realty Q2 pre-sales jump 98% to ₹902 crore, collections rise 67%” published on 5 October 2026 in Business Standard
Evidence Caveats
- Raymond Realty's Q2 and H1 operational figures are provisional.
- The interpretation of sustenance sales as a signal of underlying demand is editorial analysis.
- ₹902 crore pre-sales, ₹682 crore collections and accounting revenue are different metrics.
- The approximately 56.3%, 28.9% and 2.6 times comparisons are Vantage-derived calculations.
- More than ₹4,100 crore Mahim GDV is planned development value rather than achieved bookings.
- Management's FY27 pre-sales growth and margin targets are guidance.
- Project-level JDA economics, cancellation rates, discounts, cost of debt, debt maturities and future Mahim absorption are unavailable.

From TatvaOps
Property Purchase
Developing a property?
Structured oversight for multi-unit and investor-led builds.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
1 reply already on Forums
More from Real Estate
LTCG Tax Debate: Should You Delay Selling Investments?
Could waiting for LTCG tax relief cost more than it saves? With proposals under discussion, we examine how your current tax liability, market exposure and cash deadline should shape a planned investment sale.
Blackstones India Bet: What Should You Check?
Blackstone’s $100-billion India ambition is a useful signal. For your own money, the harder questions are access, valuation, cash flow and risk. Here is what to check before turning institutional optimism into a personal investment decision.
Senior Living: Buy the Home, Examine the Services: what most readers overlook
Rustomjee’s senior-living evaluation raises a household question: can you afford and rely on the services after buying the home? We examine recurring charges, operator responsibilities, changing support needs and exit flexibility.
Inline Intelligence
Key Insight Actions
Connected knowledge for Real Estate Market Analysis
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Topic hubs
Conclusion Intelligence
Related Discussions
Was this helpful?
Let us know what you think