
Home Loan EMI: What Does a Smaller Payment Cost?
Summary
A lower home loan EMI can come with a larger interest bill. Compare tenure, APR and repayment flexibility, with a worked example showing the cost of extending a ₹40 lakh loan from 20 to 25 years. A smaller home loan EMI can make a household budget more comfortable. It can also keep the household in debt for longer. Both can be true at the same time. The useful question is whether the reduction comes from a lower borrowing cost or from spreading repayment across more months.
Published on
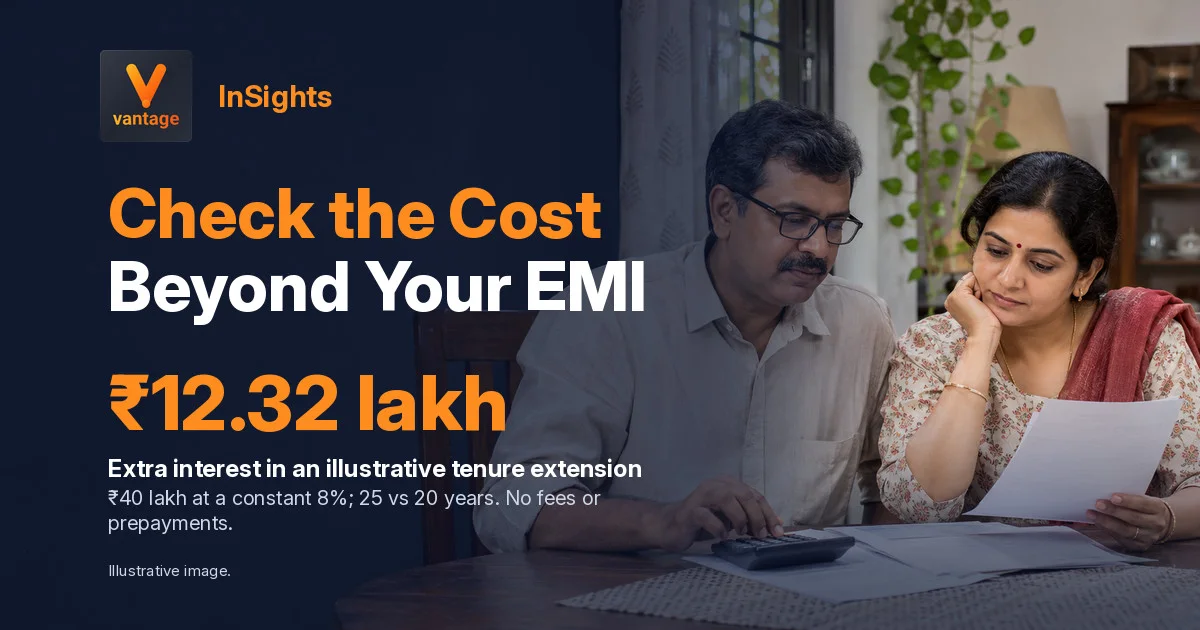
A couple reviews loan paperwork with a calculator, connecting household budgeting with the article’s illustrative ₹12.32 lakh additional interest from extending repayment under the stated assumptions.
Inline Intelligence
A smaller home-loan EMI can make a household budget more comfortable. It can also keep the household in debt for longer.
Both can be true at the same time. The useful question is whether the reduction comes from a lower borrowing cost or from spreading repayment across more months.
Outlook Money’s festive-season analysis raises that distinction -> Festive Season Home Loans: Don't Let A Lower EMI Fool You. For a buyer comparing offers, it is a reason to examine the repayment schedule before judging the deal.
How much difference can a longer tenure make?
Consider an illustrative ₹40 lakh loan at an annual interest rate of 8%, repaid through monthly instalments.
Assume the entire amount is disbursed at the start, the rate remains unchanged, payments arrive on time and there are no fees, prepayments or payment holidays.
| Repayment measure | 20-year loan | 25-year loan |
|---|---|---|
| Monthly EMI | ₹33,458 | ₹30,873 |
| Total interest | ₹40.30 lakh | ₹52.62 lakh |
| Total principal and interest repaid | ₹80.30 lakh | ₹92.62 lakh |
Extending repayment reduces the monthly EMI by approximately ₹2,585. It adds approximately ₹12.32 lakh to total interest under these assumptions.
These are independently calculated illustrations, not lender quotes or forecasts. Totals use the unrounded EMI, so multiplying the displayed rounded instalments may produce small differences.
The monthly relief is real. So is the additional borrowing cost in this example.
Does that make the longer loan a poor choice?
Not necessarily.
The shortest tenure is not automatically the most manageable one. An EMI that leaves too little for essential spending, emergencies or income disruption can create another kind of financial pressure.
Compare the schedules with your household’s reliable income and commitments. If the higher EMI leaves an inadequate buffer, the longer tenure may offer useful flexibility, provided its cost is understood.
A plan to make voluntary prepayments should be tested separately. Future bonuses and salary increases are uncertain, so show both outcomes: the contractual schedule without extra payments and a clearly labelled prepayment scenario.
What should you compare before the EMI?
Start with the same principal and tenure across lenders. Otherwise, one offer may appear cheaper because its repayment period is longer.
Ask for the Key Facts Statement, the amortisation schedule and the sanction terms. RBI’s KFS framework requires covered lenders to disclose APR and the repayment schedule, giving borrowers a structured basis for comparison.
Read the primary guidance here -> Key Facts Statement (KFS) for Loans & Advances.
APR is useful for examining the cost of credit. It is not a guarantee of the final lifetime cost of a floating-rate loan, because future rates and borrower actions can change the outcome.
What happens when the interest rate resets?
Ask which benchmark applies, what spread is added and when the next reset occurs. Then ask the lender to illustrate how a higher rate would affect the EMI, remaining tenure or both.
RBI’s floating-rate FAQ addresses communication, repayment options and quarterly statements. Its indexed version updated on 1 October 2025 describes switching to a fixed rate where that option is provided by the lender; borrowers should not assume it is universally available.
The guidance is here -> FAQs on Reset of Floating Interest Rate on EMI-based Personal Loans.
For broader context, Vantage has also explained why an aggregate lending-rate change cannot establish what happens to an individual contract -> RBI Lending Rates Ease on Fresh Rupee Loans.
Is a fee waiver still worth considering?
Yes, if it reduces a cost you would otherwise pay. Its value should be assessed within the whole offer.
List which charges are waived, which remain and whether the waiver has conditions. Compare the written totals rather than assuming that a waived processing fee means every application-related expense disappears.
If considering a balance transfer, compare the cost over your expected remaining holding period. Include the new lender’s charges and applicable exit costs, and ask how the rules apply to your loan type and sanction date.
A lower monthly payment alone cannot establish the break-even point.
What to check next
- Request comparable written offers. Use the same principal and tenure, and check the quoted rate’s eligibility conditions and validity.
- Read both the monthly and lifetime numbers. Compare EMI, APR, repayment duration, charges and the assumptions behind total interest.
- Test a less comfortable scenario. Ask for a higher-rate illustration and examine whether the payment still fits your budget without relying on uncertain income.
- Verify flexibility before depending on it. Obtain the applicable prepayment, rate-conversion and transfer conditions in writing.
The aim is a repayment structure you understand and can sustain. A festive label should not determine how much debt you take or how long you carry it.
FAQ
Does a lower EMI prove a loan is cheaper?
No. It may result from a longer tenure. Compare equivalent amounts and repayment periods before drawing that conclusion.
Is the 8% rate in the example available today?
The rate is an illustration, not a current bank offer. Obtain a personalised written quote from the lender.
Why does extending repayment increase interest?
Under the example’s assumptions, principal remains outstanding for longer. The lower monthly repayment reduces the balance more slowly.
Is APR the same as the advertised interest rate?
No. APR incorporates associated credit costs. Use the lender’s KFS and calculation to understand the difference.
Can a floating-rate loan’s final cost differ from the illustration?
Yes. Rate resets, disbursement timing, prepayments and other changes can alter the repayment path.
Should I always choose the shortest tenure?
No. Consider both total cost and your ability to maintain payments while retaining a reasonable financial buffer.
Sources
Click an article title to view the source.
- Festive Season Home Loans: Don't Let A Lower EMI Fool You published on 3 November 2026 in Outlook Money.
- Key Facts Statement (KFS) for Loans & Advances published on 15 April 2024 by the Reserve Bank of India.
- FAQs on the circular on Reset of Floating Interest Rate on Equated Monthly Instalments (EMI) based Personal Loans updated on 1 October 2025 by the Reserve Bank of India.
- RBI Lending Rates Ease on Fresh Rupee Loans published on 31 October 2026 in Vantage Radar.
Evidence Caveats
The repayment example uses the standard monthly reducing-balance EMI formula and the stated constant-rate assumptions. It excludes fees, insurance, taxes, staged disbursements and prepayments. It does not estimate inflation-adjusted cost or the return from investing any monthly difference. RBI FAQ access was inconsistent; the dated indexed official text was used. No current lender-specific rate, waiver or eligibility decision is asserted.
How would you balance a smaller monthly commitment against a larger lifetime interest bill? Share the circumstances or evidence that would influence your choice in the attached forum discussion, without disclosing sensitive financial details.
Disclaimer
This article provides general information and illustrative calculations, not personalised financial, tax or legal advice. Confirm current loan terms and applicable rules with your lender. Seek qualified advice where needed before borrowing, refinancing or changing your repayment plan.
From TatvaOps
Property Purchase
Financing your project?
Explore credit and milestone-secured payment options with Tatva Finance.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
3 replies already on Forums
More from Real Estate
Your Project Is Delayed. Can You Stop Paying the Builder?
A Haryana RERA case shows why project delay and buyer default can be separate questions. Before withholding an instalment, check the payment milestone, demand notices, construction evidence and your agreement.
Your Flat Is Delayed, but Payment Demands Keep Coming. What Should You Check?
Before you commit to a number, a delayed home can leave a buyer facing two pressures at once: the property is not ready, while instalment demands or loan repayments continue — worth a full read?
Is Your Cheque Book Still Valid? Three Things to Check Before a Payment
The RBI rejected a nationwide cheque-book replacement claim, but bank-specific instructions may still matter. Check your cheque series, the date on each cheque and your bank’s Positive Pay rules.
Inline Intelligence
Key Insight Actions
Connected knowledge for Personal Finance
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Topic hubs
Conclusion Intelligence
Related Discussions
Was this helpful?
Let us know what you think