

Shapoorji Pallonji Shelved Its Real Estate IPO: Can the Group Solve a 55,000 Crore Debt Challenge Without It?
Karthik posts articles on Energy and Construction.
Summary
Shapoorji Pallonji Group has shelved its real estate IPO for now while managing debt estimated at more than ₹55,000 crore. The bigger balance sheet question is whether monetising part of its 18.4% Tata Sons stake can provide enough permanent liquidity to reduce costly debt without requiring the grou Shapoorji Pallonji Group has put the proposed listing of Shapoorji Pallonji Real Estate on the back burner. That removes, at least temporarily, one potential source of equity capital for a group carrying debt estimated at more than ₹55,000 crore .
Published on
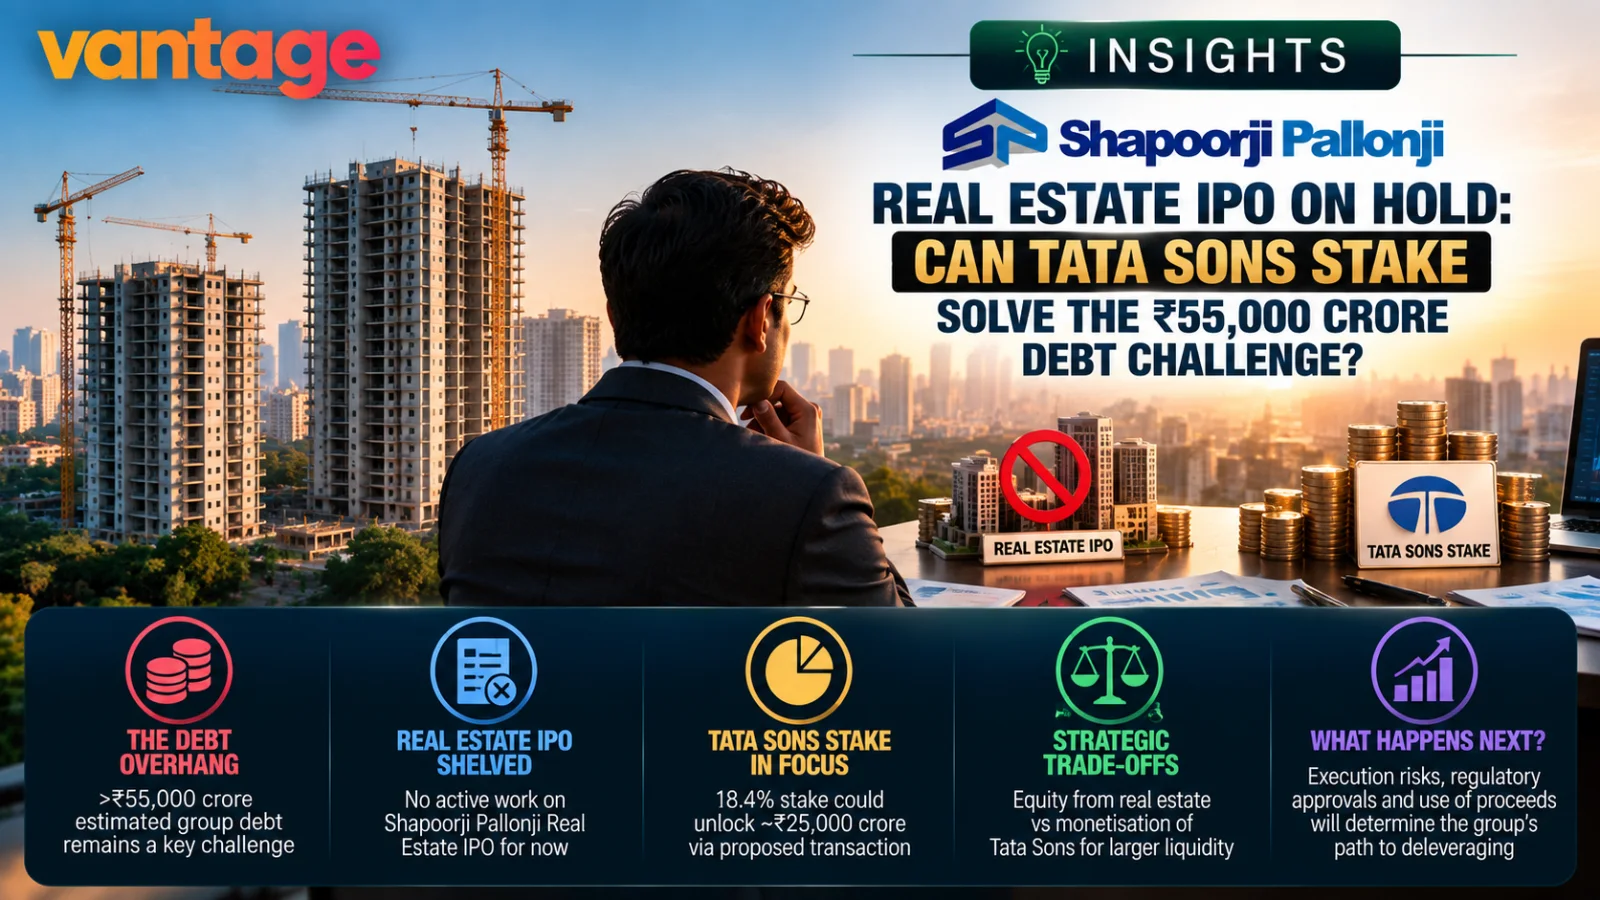
InSights editorial banner showing Shapoorji Pallonji branding against an Indian real estate construction backdrop, with an investor evaluating competing capital strategies. The visual frames the group's estimated debt burden, the shelved real estate IPO, its 18.4% Tata Sons stake and the strategic question of whether potential stake monetisation can provide meaningful liquidity and support deleveraging.
Inline Intelligence
Shapoorji Pallonji Group has put the proposed listing of Shapoorji Pallonji Real Estate on the back burner.
That removes, at least temporarily, one potential source of equity capital for a group carrying debt estimated at more than ₹55,000 crore.
But SP Group possesses something potentially more valuable than an SPRE IPO.
It owns approximately 18.4% of Tata Sons.
A proposal involving the monetisation of around 3% of that holding could potentially generate approximately ₹25,000 crore of gross proceeds.
The strategic question is therefore not simply why SPRE is no longer preparing to list.
It is whether monetising a relatively small portion of the Tata Sons stake could provide a more effective route to repairing the group's capital structure than selling equity in the real estate business.
The IPO Was One Route, Not the Entire Plan
An SPRE IPO could have raised fresh capital and established a public valuation for the real estate platform.
That would have been useful.
But the group's financing challenge is much larger than one real estate transaction.
SP Group has been refinancing substantial borrowings while attempting to unlock value from major assets.
The SPRE IPO therefore needs to be viewed as one component of a broader capital strategy.
With that component paused, the alternatives become more important.
The ₹55,000 Crore Number Needs Context
Moneycontrol estimates SP Group debt at more than ₹55,000 crore.
This is group-level debt.
It is not the standalone debt of SPRE.
That distinction matters because the real estate business and the wider conglomerate should not be treated as financially identical entities.
The IPO may have contributed liquidity to the wider group, but the reviewed evidence does not establish exactly how much IPO capital would have been raised or how much would have gone towards debt reduction.
Why Tata Sons Is the Key Asset
SP Group owns approximately 18.4% of Tata Sons.
The difficulty is that the stake has historically been illiquid.
Unlike publicly traded shares, it cannot simply be sold on an exchange.
That means its theoretical value and its immediate cash value can be very different things.
Unlocking liquidity requires a transaction.
The proposed selective capital reduction is one such possibility.
₹25,000 Crore Changes the Scale of the Discussion
The proposed transaction could generate around ₹25,000 crore of gross proceeds.
Compared with a debt estimate exceeding ₹55,000 crore, that is substantial.
The ratio is approximately 45.5%.
This is a Vantage-derived scale comparison.
It is not a deleveraging forecast.
Gross proceeds can be reduced by taxes and transaction effects, while management could allocate capital to refinancing, operations or other obligations.
Still, the comparison illustrates why Tata Sons monetisation can potentially matter more to the group's balance sheet than a conventional real estate IPO.
Selling SPRE Equity and Monetising Tata Sons Are Economically Different
An SPRE IPO would exchange ownership in the real estate business for capital.
Monetising part of Tata Sons would exchange part of an existing financial asset for capital.
The distinction matters strategically.
SP Group may prefer to preserve ownership in a growing operating business if it can raise sufficient liquidity from another asset.
Alternatively, public markets might eventually provide SPRE with benefits beyond immediate fundraising.
There is no verified evidence that this trade-off caused the IPO decision.
It is an analytical framework for understanding the available options.
The Cost of Waiting Matters
SP Group's debt challenge is not only about principal.
Financing costs matter.
The group has undertaken major private-credit and bond transactions.
The Economic Times recently reported yields ranging from roughly 14% to 18.95% on recent bond offerings in the context of its fundraising.
High borrowing costs can make time expensive.
Even if refinancing pushes maturities outward, the group ultimately benefits from reducing reliance on costly debt rather than repeatedly replacing it.
Refinancing Buys Time
SP Group completed approximately ₹15,100 crore of private-credit financing in July.
It subsequently repaid ₹3,500 crore to bondholders after securing fresh loans.
Further dollar and rupee bond fundraising has also been reported.
These transactions can improve liquidity and manage near-term maturities.
But refinancing does not necessarily solve the underlying leverage problem.
It can create time for an asset monetisation transaction to occur.
That may be its most strategically important function.
Deleveraging Changes the Equation
Suppose SP Group can monetise a portion of Tata Sons and direct a significant amount towards debt repayment.
Lower debt could potentially:
- reduce interest expense;
- improve refinancing flexibility;
- lower financial risk;
- strengthen negotiating power with lenders; and
- reduce the urgency of selling equity in operating businesses.
Whether these outcomes occur depends on the transaction actually being completed and how proceeds are used.
Neither is currently certain.
Why Keep SPRE Private?
There are potential reasons a shareholder might prefer to retain a real estate business privately.
Private ownership can provide:
- greater control;
- less quarterly market scrutiny;
- flexibility around capital allocation; and
- freedom from public-market valuation volatility.
But remaining private also removes some advantages of listed equity.
These can include:
- access to public capital;
- price discovery;
- acquisition currency;
- institutional investor participation; and
- future equity fundraising.
The reviewed evidence does not establish which considerations drove SP Group's decision.
SPRE Still Has an Operating Business to Grow
The real estate platform continues to develop projects.
Its activities span residential and commercial development, affordable-to-mid-income housing through Joyville and redevelopment through SD Corp.
Recent 2026 launches have included projects in Mumbai and Pune.
This means the capital-structure discussion should not obscure the operating business.
A future IPO could become more attractive if SPRE expands its portfolio, improves cash generation or reaches a valuation the owners find compelling.
Could Shelving the IPO Preserve Future Value?
Potentially.
If shareholders believe the business could command a better valuation later, postponing an IPO can preserve that option.
But there is no verified evidence that valuation was the reason the current process was paused.
Any such interpretation must remain hypothetical.
The observable fact is simply that active IPO work has stopped.
The Tata Sons Route Has Its Own Risks
Monetising the Tata Sons stake is not straightforward.
The proposed capital reduction remains unresolved.
The wider debate includes questions around Tata Sons' listing, shareholder interests, regulatory requirements and governance.
Moneycontrol reports that people familiar with the situation expect any monetisation process to be lengthy.
This creates an important trade-off.
The potentially larger source of liquidity may also be the more complicated one to execute.
Could the SPRE IPO Become the Backup Plan Again?
Yes.
If Tata Sons monetisation stalls, SP Group could theoretically revisit other routes.
Those might include:
- an SPRE IPO;
- asset sales;
- additional refinancing;
- strategic investment;
- other equity transactions; or
- combinations of these.
The evidence does not establish which path would be chosen.
But shelving the IPO today does not remove its future option value.
What Does This Mean for Real Estate Investors?
SPRE's situation illustrates an important distinction in developer analysis.
A developer can have:
valuable land and projects,
strong operating assets,
and still face
capital-structure constraints at the shareholder or group level.
Investors therefore need to examine both operating performance and financing structure.
One cannot automatically substitute for the other.
What Does It Mean for Homebuyers?
Homebuyers should resist two opposite conclusions.
The first is that a shelved IPO means individual projects are necessarily in trouble.
The evidence does not support that.
The second is that a large corporate asset such as the Tata Sons stake eliminates project-level risk.
That is also unsupported.
Homebuyers should continue evaluating individual SPRE projects through RERA records, approvals, construction progress and contractual commitments.
What Would a Successful Debt Strategy Look Like?
The strongest outcome for SP Group would involve more than simply avoiding near-term defaults.
A durable capital strategy would likely require:
- manageable maturities;
- lower borrowing costs;
- permanent debt reduction;
- adequate operating liquidity; and
- preservation of valuable operating assets.
Refinancing can address the first two only partly.
Asset monetisation could potentially address the third.
Operating cash generation contributes to the fourth.
The fifth determines how much long-term value remains after the restructuring process.
The Critical Metric Is Not IPO Proceeds Anymore
With SPRE's listing on the back burner, the key metric shifts.
Investors should now watch actual debt reduction.
Not proposed liquidity.
Not estimated asset value.
Not refinancing volume.
Actual reduction in outstanding obligations.
If Tata Sons monetisation generates cash but debt remains broadly unchanged, the balance-sheet problem will look different from a scenario in which proceeds materially reduce leverage.
The Real Trade-Off
SP Group faces a capital-allocation problem involving two very different assets.
One is an operating real estate platform.
The other is a large minority holding in one of India's most important corporate holding companies.
An SPRE IPO would monetise part of the first.
A Tata Sons transaction would monetise part of the second.
The latter may offer much greater liquidity.
But it is also entangled in a complex shareholder and regulatory process.
That explains why shelving the SPRE IPO does not make the group's financial story simpler.
It arguably makes the Tata Sons outcome even more consequential.
Frequently Asked Questions
Why did Shapoorji Pallonji shelve the SPRE IPO?
Moneycontrol reports that active work on the IPO has stopped while the group explores other capital-unlocking options. The reviewed evidence does not establish one definitive reason for the decision.
Is Shapoorji Pallonji Real Estate in financial trouble?
The reviewed evidence establishes significant debt at the wider SP Group level, not that SPRE itself is in financial distress. Standalone SPRE financial metrics are not sufficiently disclosed in the reviewed sources to make that conclusion.
Why is SP Group's Tata Sons stake important?
SP Group owns approximately 18.4% of Tata Sons. Monetising part of this holding could potentially generate substantial liquidity for the group.
How much could the proposed Tata Sons transaction raise?
A proposed selective capital reduction involving around 3% of SP Group's stake could generate approximately ₹25,000 crore in gross proceeds, according to Moneycontrol.
How does ₹25,000 crore compare with SP Group's debt?
It is approximately 45.5% of the more than ₹55,000 crore debt estimate. This is only a scale comparison and does not represent expected debt reduction.
Why does SP Group keep refinancing debt?
Refinancing can address maturities and liquidity while the group pursues longer-term capital solutions. It does not necessarily reduce total debt.
Could SPRE still list later?
Yes. The IPO is shelved for now rather than verified as permanently cancelled. No new timetable is available.
What should investors watch next?
Actual Tata Sons monetisation, use of proceeds, changes in group debt, refinancing costs and any revival of the SPRE IPO process are the key indicators.
Sources
Click on article title to view article.
“Shapoorji Pallonji Group shelves plans to list real estate arm” published on 5 October 2026 in Moneycontrol
“SP Group renews push to monetise Tata Sons stake before listing, seeks relief from costly debt” published on 1 October 2026 in Moneycontrol
“Shapoorji Pallonji Group closes one of India's biggest private credit deals” published on 20 July 2026 in Business Standard
Evidence Caveats
- The interpretation of the choice between SPRE equity and Tata Sons monetisation is Vantage editorial analysis.
- No evidence reviewed establishes that Tata Sons monetisation caused the SPRE IPO to be shelved.
- More than ₹55,000 crore is an estimated group-level debt figure.
- ₹25,000 crore is proposed gross liquidity, not completed proceeds.
- The 45.5% comparison is Vantage-derived and is not a deleveraging forecast.
- Reported refinancing should not be treated as permanent debt reduction.
- Standalone SPRE debt, valuation, profitability, IPO valuation and future IPO timing remain unavailable.

From TatvaOps
Residential Construction
Need a reliable project estimate?
Structured costing and BOQ support before you commit budget.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
1 reply already on Forums
More from Real Estate
LTCG Tax Debate: Should You Delay Selling Investments?
Could waiting for LTCG tax relief cost more than it saves? With proposals under discussion, we examine how your current tax liability, market exposure and cash deadline should shape a planned investment sale.
Blackstones India Bet: What Should You Check?
Blackstone’s $100-billion India ambition is a useful signal. For your own money, the harder questions are access, valuation, cash flow and risk. Here is what to check before turning institutional optimism into a personal investment decision.
Senior Living: Buy the Home, Examine the Services: what most readers overlook
Rustomjee’s senior-living evaluation raises a household question: can you afford and rely on the services after buying the home? We examine recurring charges, operator responsibilities, changing support needs and exit flexibility.
Inline Intelligence
Key Insight Actions
Connected knowledge for Financial Analysis
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Topic hubs
Conclusion Intelligence
Related Discussions
Was this helpful?
Let us know what you think