

Merlin Group Plans 10,000 Crore Expansion: Can a 20 Million Sq Ft Pipeline Deliver Without Stretching Execution?
Karthik posts articles on Energy and Construction.
Summary
Merlin Group plans to invest ₹10,000 crore over five years and launch nearly 20 million sq ft of development potential. The opportunity is substantial, but rising construction costs and a pipeline spanning housing, offices, malls and mixed use projects make execution, leasing and capital discipline Merlin Group is preparing for a significant expansion cycle. The Kolkata based developer plans to invest approximately ₹10,000 crore over five years and has nearly 20 million sq ft of development potential intended for launch over the next two to three years.
Published on
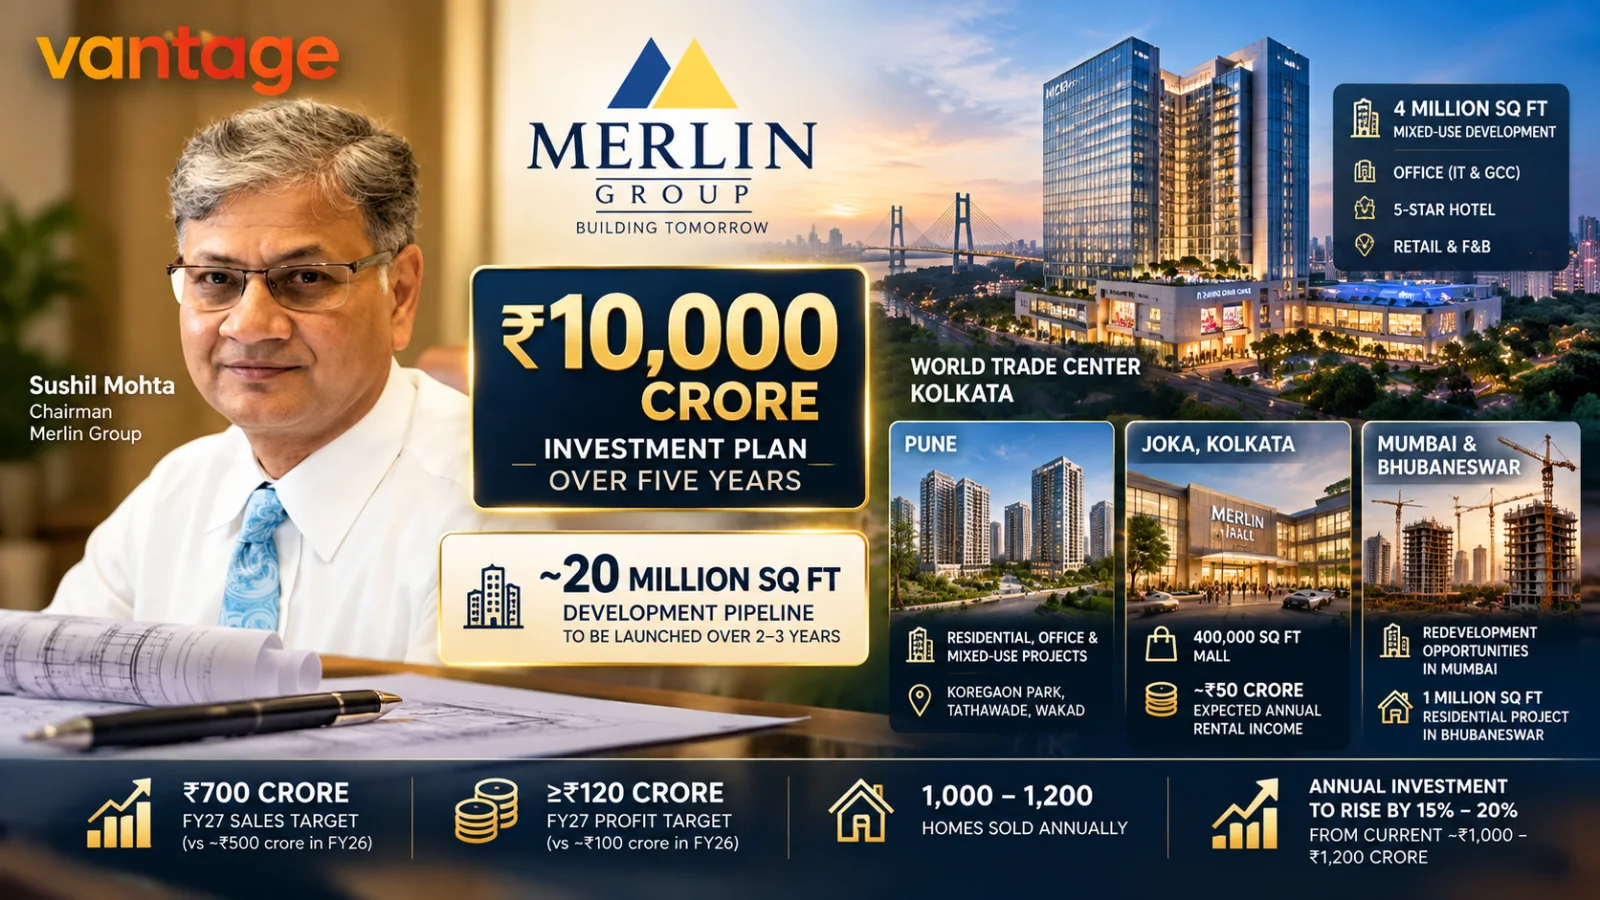
Editorial Radar-style banner featuring the supplied executive portrait alongside residential, commercial, retail and construction imagery representing Merlin Group's planned expansion. The visual highlights the ₹10,000 crore five-year investment plan, nearly 20 million sq ft development pipeline, Kolkata and Pune projects, and FY27 growth targets.
Inline Intelligence
Merlin Group is preparing for a significant expansion cycle.
The Kolkata-based developer plans to invest approximately ₹10,000 crore over five years and has nearly 20 million sq ft of development potential intended for launch over the next two to three years.
Its pipeline spans residential projects, offices, malls and mixed-use developments across markets including Kolkata and Pune.
Merlin is also targeting approximately ₹700 crore in FY27 sales, compared with around ₹500 crore in FY26.
The growth opportunity is clear.
But the more important question for buyers, investors and the company itself is:
Can Merlin scale investment, construction and leasing fast enough without allowing execution risk or rising costs to erode the benefits of expansion?
₹10,000 Crore Is a Plan, Not an Outcome
Large investment announcements can create the impression that the capital has already entered projects.
That is not what the disclosed figure means.
Merlin's ₹10,000 crore represents planned deployment over five years.
The company currently invests approximately ₹1,000 crore to ₹1,200 crore annually and expects that figure to increase around 15% to 20% each year.
Actual five-year deployment will therefore depend on factors including:
- project approvals;
- land availability;
- financing;
- launch schedules;
- construction;
- sales;
- leasing; and
- market conditions.
For investors, execution against the plan matters more than the headline number.
The 20 Million Sq Ft Pipeline Is the Bigger Operational Challenge
Merlin says it has nearly 20 million sq ft of development potential planned for launch over the next two to three years.
That is a large pipeline relative to the company's current reported sales scale.
Development potential, however, passes through several stages before becoming economic value.
A project needs to move from planning to approval, launch, construction, sales or leasing and finally completion.
Each stage introduces different risks.
The challenge is therefore not simply launching 20 million sq ft.
It is converting that pipeline into completed, cash-generating assets without weakening capital discipline.
Merlin Is Diversifying Beyond Residential Development
The portfolio is becoming increasingly mixed.
The company's major projects include:
- residential housing;
- office developments;
- shopping malls;
- mixed-use projects;
- hospitality components; and
- recurring rental assets.
This diversification can reduce reliance on one property segment.
Residential projects can produce development sales.
Commercial and retail assets can create recurring rental income.
Mixed-use projects can combine both models.
But diversification also makes execution more complex.
Selling apartments requires a different operating model from leasing offices or managing shopping malls.
A broader portfolio therefore increases both opportunity and organisational demands.
Kolkata World Trade Center Is a Major Test
Merlin's approximately 4 million sq ft World Trade Center development in Kolkata is one of the clearest examples.
The project combines IT and GCC offices, hospitality and food and beverage retail.
Phase 1, at approximately 600,000 sq ft, is almost completely sold or leased according to the company.
Later phases are substantially larger.
Phase 2 is approximately 1.5 million sq ft and Phase 3 approximately 1 million sq ft.
That creates significant future commercial space.
The project's success will depend partly on whether Kolkata can attract sufficient corporate and GCC demand to absorb that capacity.
GCC Growth Could Support the Office Strategy
India's office market has been benefiting from substantial GCC expansion.
That creates an opportunity for developers delivering modern Grade A offices.
Merlin's World Trade Center strategy explicitly includes IT and GCC space.
But national GCC growth does not automatically translate into equal demand across every city.
Kolkata still has to compete with established GCC markets such as Bengaluru, Hyderabad, Chennai and Delhi-NCR.
The question is therefore not whether GCC demand is growing nationally.
It is how much of that demand Kolkata can capture.
Pune Provides a Different Growth Engine
Merlin's Pune pipeline includes major projects in Koregaon Park, Tathawade and Wakad.
The company is developing residential, commercial and mixed-use assets in the city.
It has also acquired approximately three acres in Koregaon Park for about ₹300 crore, where it plans a 1.3 million to 1.4 million sq ft high-end commercial office tower.
Pune offers exposure to a different demand base from Kolkata.
That geographic diversification can reduce dependence on one city.
But it also requires Merlin to compete against established Pune developers and institutional office landlords.
The Rental Portfolio Could Change Merlin's Business Mix
Merlin currently generates approximately ₹60 crore in annual rental income, mainly from Homeland Mall and Acropolis Mall.
Its Joka mall is expected by the company to contribute another ₹50 crore annually once operational.
That potential contribution is large relative to the existing rental base.
A Vantage scale comparison puts the expected ₹50 crore at approximately 83% of current annual rental income.
This does not mean Merlin's rental income will automatically grow 83%.
Existing asset performance, commencement timing and stabilisation of the new mall all matter.
But it illustrates how much the Joka asset could change the scale of the recurring-income business if the company's expectation is achieved.
Recurring Income Can Reduce Dependence on Residential Sales
Residential development produces cash flows that can be uneven.
Sales depend on project launches, construction progress and buyer demand.
Rental assets create a different income profile.
A stabilised office or mall can produce recurring cash flow through leases.
For a developer pursuing a large expansion programme, a growing rental portfolio can therefore provide diversification.
But holding income-producing assets also ties up capital.
Merlin will need to balance the value of recurring income against the capital required to develop and retain those properties.
The FY27 Sales Target Requires Faster Growth
Merlin recorded approximately ₹500 crore in sales in FY26.
Its FY27 target is approximately ₹700 crore.
That implies a 40% increase, based on a Vantage calculation.
Profit is targeted at at least ₹120 crore, compared with around ₹100 crore in FY26.
That represents at least 20% growth.
The different growth rates are worth noting.
Sales are targeted to rise faster than profit.
That does not establish margin compression because these are broad company figures and additional financial detail would be required.
But it reinforces why investors should evaluate profitability alongside headline sales growth.
Construction Costs Are the Most Immediate Pressure
Mohta said construction costs had increased by approximately 20% during the year.
He cited materials such as aluminium and tiles among the drivers.
This is particularly relevant for projects where homes have already been sold.
A developer cannot simply reprice an existing customer contract every time input costs increase.
That means cost inflation can be absorbed by the developer and reduce project margins.
For a company planning rapid expansion, procurement, construction efficiency and pricing discipline therefore become critical.
Bigger Pipelines Increase Working-Capital Demands
A 20 million sq ft development pipeline requires more than land.
Projects require capital for:
- approvals;
- design;
- construction;
- contractors;
- materials;
- marketing;
- infrastructure; and
- working capital.
The reviewed evidence does not provide enough information to determine Merlin's future financing mix, consolidated debt or cost of capital.
Those are important unavailable metrics.
A large pipeline can create substantial value when projects sell and lease successfully.
It can also increase capital requirements before that value is realised.
For Homebuyers, Scale Does Not Replace Project Due Diligence
A ₹10,000 crore investment plan can strengthen a developer's visibility.
But buyers purchase individual homes, not five-year corporate investment plans.
The relevant questions remain project-specific.
Buyers should examine:
- RERA details;
- approvals;
- construction milestones;
- possession schedules;
- specifications;
- payment plans; and
- contractual commitments.
The size of Merlin's overall pipeline should therefore be treated as corporate context rather than a guarantee of any individual project's delivery.
For Commercial Investors, Absorption Matters More Than Construction
The office component of Merlin's expansion creates another analytical distinction.
Building office space does not create economic value by itself.
The space needs to attract occupiers.
Investors should watch:
- pre-leasing;
- physical occupancy;
- rent-paying occupancy;
- achieved rents;
- lease duration;
- tenant quality;
- GCC demand; and
- competing supply.
The same principle applies to retail assets.
A completed mall needs tenants, footfall and sustainable retailer economics.
The Opportunity Is Scale Plus Diversification
Merlin's strategy has several potential strengths.
It is expanding across multiple asset classes.
It has exposure to Kolkata and Pune rather than relying on one city.
It is developing recurring rental income alongside residential sales.
And it has a substantial launch pipeline.
If execution remains disciplined, these factors could create a larger and more diversified real estate platform.
The Risk Is Trying to Scale Too Many Things at Once
The other side of diversification is complexity.
Merlin is simultaneously pursuing:
- housing launches;
- office developments;
- malls;
- mixed-use projects;
- rental assets;
- hospitality-linked development;
- geographic expansion; and
- potential Mumbai redevelopment.
Each requires management attention and capital.
Rapid expansion can create pressure on:
- cash flow;
- construction management;
- procurement;
- project delivery;
- leasing teams; and
- financing.
The quality of execution therefore becomes more important as the pipeline grows.
What Would Confirm the Expansion Thesis?
Several indicators would strengthen the case that Merlin is successfully converting its investment plan into operating growth.
FY27 sales approach the ₹700 crore target
This would indicate stronger residential or development sales.
World Trade Center phases achieve strong leasing or sales
That would provide evidence that commercial demand is absorbing new supply.
Joka mall opens and builds rental income
This would expand recurring revenue.
Pune projects maintain execution schedules
That would validate geographic diversification.
Construction-cost pressure moderates
This could reduce pressure on project margins.
Rental income grows without excessive leverage
This would strengthen the quality of recurring cash flow.
What Would Challenge the Plan?
Warning signs would include:
- project-launch delays;
- slower residential sales;
- weak office absorption;
- cost inflation;
- delayed mall stabilisation;
- rising leverage;
- slower collections; or
- execution delays across multiple projects.
The reviewed evidence does not establish that these outcomes are occurring.
They are the key risks to monitor when evaluating a large forward development plan.
The ₹10,000 Crore Headline Is Only the Starting Point
Merlin's investment plan is significant because it signals an ambition to scale beyond its existing footprint.
But real estate value is created through execution rather than announcements.
The 20 million sq ft pipeline needs to become launched projects.
Those projects need to become sold or leased space.
Construction needs to become completed assets.
And rental properties need to become stable cash-flow generators.
If Merlin can achieve those transitions while controlling construction costs and financing, the five-year plan could materially expand the company.
If execution or demand lags, the same scale could increase capital and delivery risk.
That is the central trade-off behind Merlin Group's ₹10,000 crore expansion.
Frequently Asked Questions
Is Merlin Group investing ₹10,000 crore immediately?
No. The company says it plans to deploy approximately ₹10,000 crore over five years.
What is the biggest risk in Merlin Group's expansion plan?
No single risk can be identified as definitive. Execution, construction costs, project sales, commercial leasing, financing and the pace of new launches will all matter.
Why is the 20 million sq ft pipeline important?
It represents substantial future development potential, but it also creates significant construction, capital and sales or leasing requirements.
Could Merlin's rental income increase substantially?
The company currently reports around ₹60 crore of annual rental income and expects its Joka mall to add approximately ₹50 crore annually once operational. The latter is a forward company expectation.
Is Merlin becoming less dependent on residential housing?
Its pipeline includes offices, malls, mixed-use projects and rental assets alongside housing, indicating a more diversified portfolio. The reviewed evidence does not provide a future revenue mix sufficient to quantify the degree of dependence.
Why does construction-cost inflation matter?
Costs that rise after homes have already been sold can pressure developer margins because existing bookings cannot simply be repriced to recover every subsequent increase.
Is the Kolkata World Trade Center already fully completed?
No. The project has multiple phases. Merlin says Phase 1 is almost completely sold or leased, while later phases form part of the continuing development programme.
What should investors watch over the next two years?
Project launches, sales, commercial leasing, rental-income growth, completion schedules, construction costs and financing will provide clearer evidence of how successfully Merlin is executing the plan.
Sources
Click on article title to view article.
“Merlin Group plans ₹10,000 crore investment over five years; targets ₹700 crore sales in FY27” published on 2 October 2026 in ETRealty
Evidence Caveats
- ₹10,000 crore is a forward five-year investment plan.
- Nearly 20 million sq ft is planned development potential, not completed or occupied real estate.
- FY27 sales and profit figures are company targets.
- The 40% sales-growth comparison, minimum 20% profit-growth comparison and 83% Joka-rent scale comparison are Vantage-derived calculations.
- The expected ₹50 crore Joka mall rental contribution is a company forecast.
- The analysis of execution complexity, working-capital demands and diversification is editorial interpretation based on the disclosed development plan.
- Consolidated debt, future financing costs, project-level margins, project IRRs and future rental yields were not available in the reviewed evidence.

From TatvaOps
Residential Construction
Building or extending your home?
Run your residential build with verified contractors and daily progress tracking.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
1 reply already on Forums
More from Real Estate
LTCG Tax Debate: Should You Delay Selling Investments?
Could waiting for LTCG tax relief cost more than it saves? With proposals under discussion, we examine how your current tax liability, market exposure and cash deadline should shape a planned investment sale.
Blackstones India Bet: What Should You Check?
Blackstone’s $100-billion India ambition is a useful signal. For your own money, the harder questions are access, valuation, cash flow and risk. Here is what to check before turning institutional optimism into a personal investment decision.
Senior Living: Buy the Home, Examine the Services: what most readers overlook
Rustomjee’s senior-living evaluation raises a household question: can you afford and rely on the services after buying the home? We examine recurring charges, operator responsibilities, changing support needs and exit flexibility.
Inline Intelligence
Key Insight Actions
Connected knowledge for Real Estate Expansion Analysis
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Senior Living: Buy the Home, Examine the Services: what most readers overlook
1 replies
Related discussionData Centres Next Door: What Should Homebuyers Check?
1 replies
Related discussionIf Green Certification Is Becoming Standard, What Will Make One Office Building Worth More Than Another?
1 replies
Related discussion
Topic hubs
Conclusion Intelligence
Related Discussions
Senior Living: Buy the Home, Examine the Services: what most readers overlook
Popular in insights discussions1 reply
Data Centres Next Door: What Should Homebuyers Check?
Popular in insights discussions1 reply
If Green Certification Is Becoming Standard, What Will Make One Office Building Worth More Than Another?
Popular in insights discussions1 reply
Was this helpful?
Let us know what you think