

DLF Sold 1,985 Crore of Luxury Senior Homes: Is Retirement Housing Becoming India's Next Premium Real Estate Category?
Karthik posts articles on Energy and Construction.
Summary
DLF Sold ₹1,985 Crore of Luxury Senior Homes: Is Retirement Housing Becoming India's Next Premium Real Estate Category? DLF has sold all 172 homes at The Aureva, its luxury senior living project in Gurugram. Total reported sales were approximately ₹1,985 crore . Average price realisation was approximately ₹11.5 crore per residence . NRIs accounted for 25% of buyers, according to Business Standard. Those numbers make The Aureva an unusual real estate experiment. This is not affordable retirement housing. It is not conventional assisted living. And it is not simply another luxury tower.
Published on
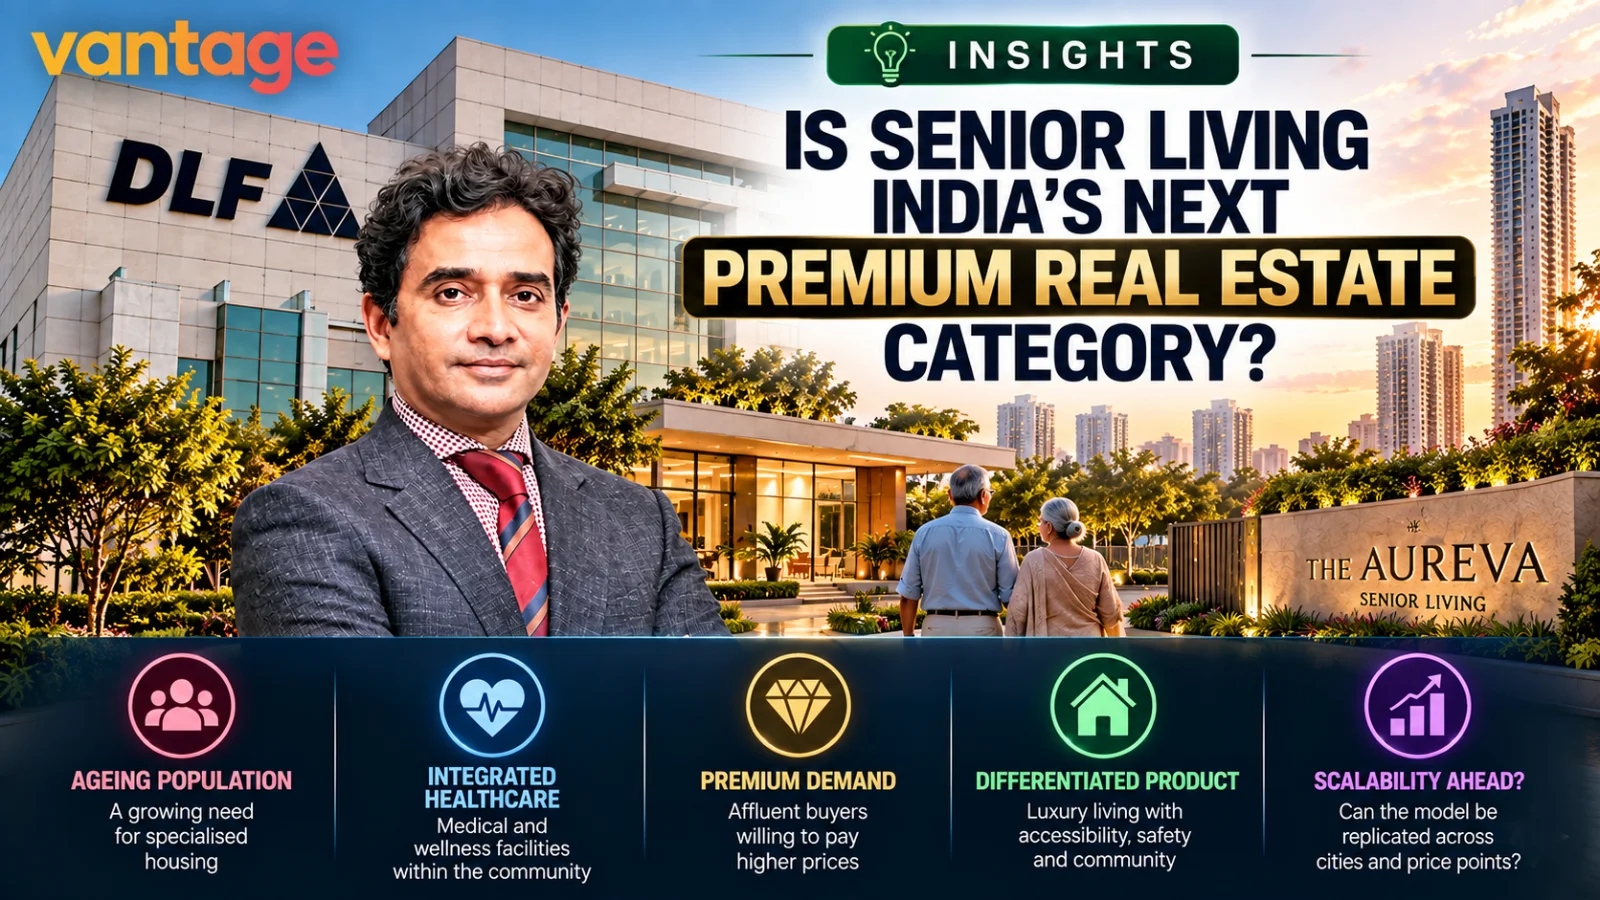
InSights editorial banner combining the supplied executive portrait and DLF building reference with an illustrative luxury senior-living environment. An older couple represents the target resident segment, while the visual frames ageing demographics, integrated healthcare and wellness, premium buyer demand, differentiated age-friendly housing and the key question of whether the luxury senior-living model can scale across Indian cities and price points.
Inline Intelligence
DLF has sold all 172 homes at The Aureva, its luxury senior-living project in Gurugram.
Total reported sales were approximately ₹1,985 crore.
Average price realisation was approximately ₹11.5 crore per residence.
NRIs accounted for 25% of buyers, according to Business Standard.
Those numbers make The Aureva an unusual real estate experiment.
This is not affordable retirement housing.
It is not conventional assisted living.
And it is not simply another luxury tower.
The project combines high-end residential property with age-oriented design, healthcare access, wellness, hospitality and community infrastructure.
The question is whether DLF has demonstrated the emergence of a scalable new real estate category, or whether The Aureva is primarily an exceptionally successful luxury project serving a small group of wealthy buyers.
Start With the ₹11.5 Crore Ticket Size
The economics immediately separate The Aureva from conventional senior housing.
DLF reported an average price realisation of approximately ₹11.5 crore per apartment.
The project generated approximately ₹1,985 crore from only 172 homes.
That creates a very different market proposition from senior housing designed around affordability.
A developer does not need thousands of buyers when each transaction has an eight-figure rupee ticket size.
This Is Senior Living Through a Luxury-Housing Lens
The Aureva combines several characteristics:
- large four-bedroom residences;
- premium finishes;
- private decks;
- dedicated staff accommodation;
- universal-accessibility features;
- an on-site medical centre;
- emergency-response support;
- wellness;
- hospitality; and
- community infrastructure.
The product therefore appears designed around a particular buyer problem.
Affluent seniors may want independence and luxury without giving up access to healthcare, safety and community.
That is a different proposition from either a conventional apartment or an institutional care facility.
Why Would Someone Pay ₹11.5 Crore for Senior Living?
The answer cannot be established from sales data alone because the reviewed evidence does not include a buyer survey.
But the product suggests several possible sources of value.
For an affluent older resident, conventional luxury housing may still leave unresolved questions around:
- accessibility;
- medical emergencies;
- community;
- maintenance;
- security; and
- ageing in place.
A purpose-designed retirement community attempts to integrate those functions.
For wealthy households, the decision may therefore be less about paying a premium for the apartment itself and more about paying for a residential ecosystem designed around later life.
That is an editorial interpretation, not a reported buyer-motivation metric.
NRI Demand Is Particularly Interesting
Business Standard reports that NRIs represented approximately 25% of buyers.
That is potentially important.
Families living overseas can face a practical problem when parents or older relatives remain in India.
A professionally managed senior community with healthcare and emergency infrastructure may address some of that concern.
But the evidence does not disclose why individual NRI buyers purchased homes.
The NRI share therefore identifies an important buyer group without proving the motivation behind their purchases.
Scarcity May Be as Important as Senior Living
The Aureva contains only 172 residences.
That means the project does not need mass adoption to sell out.
DLF's brand, Gurugram location, product scarcity and luxury positioning may all have contributed to absorption.
This creates an important analytical distinction.
A successful senior-living project does not automatically equal a large senior-living market.
A limited number of wealthy buyers can make a small luxury project extremely successful.
Can the Model Scale?
This is the most important question.
Scaling could happen in two different ways.
More luxury senior projects
Developers could replicate high-ticket retirement communities in wealthy micro-markets across Gurugram, Mumbai, Bengaluru, Pune, Hyderabad or other cities.
Broader senior housing
Developers could create products at lower ticket sizes for a much larger group of older households.
The Aureva provides evidence for the first model.
It provides much less evidence for the second.
Healthcare Changes the Real Estate Proposition
Conventional residential projects typically compete on:
- location;
- apartment size;
- amenities;
- brand; and
- price.
Senior living adds another layer.
Healthcare access and emergency response become part of the residential value proposition.
That means operating quality may matter long after the apartment is sold.
A beautifully designed medical centre has limited value if staffing, emergency response or long-term management is poor.
For buyers, due diligence therefore needs to extend beyond the developer's construction record.
The Operating Model Could Matter as Much as the Building
Senior communities require ongoing services.
That raises questions conventional luxury-home buyers may spend less time considering.
Who manages the community?
What services are included?
What are recurring charges?
How are medical emergencies handled?
How does service quality change over time?
What happens when residents require greater levels of assistance?
The reviewed sources do not provide enough information to answer all these questions for The Aureva.
They are nevertheless important considerations when evaluating the category.
Senior Housing Is Not One Product
The phrase "senior living" can hide very different businesses.
An independent-living community for active retirees is different from assisted living.
Assisted living is different from nursing care.
Luxury retirement housing is different again.
The Aureva appears closest to a premium independent-retirement model with healthcare access and age-oriented infrastructure.
That distinction matters because demand, operating complexity and pricing can vary dramatically across these categories.
DLF's Brand Probably Matters
DLF has developed more than 185 projects covering more than 352 million sq ft, according to the company.
Its scale and brand can influence buyer confidence in a way that may be difficult for smaller developers to reproduce.
Senior housing can make trust particularly important because buyers may care about long-term maintenance and service continuity.
The Aureva's performance therefore cannot automatically be used as a benchmark for an unknown developer launching an equivalent project.
Gurugram Matters Too
The project sits in Sector 63, Gurugram.
Location can affect the economics through:
- surrounding property values;
- proximity to healthcare;
- family accessibility;
- transport connectivity;
- local wealth; and
- buyer familiarity with premium residential products.
A ₹11.5 crore senior home in Gurugram cannot automatically establish the viable ticket size for retirement housing elsewhere.
The ₹1,985 Crore Sell-Out Is Material for DLF
DLF's FY27 sales-booking guidance is approximately ₹20,000 crore.
The Aureva's ₹1,985 crore is equivalent to approximately 9.9% of that target.
That is a Vantage-derived comparison.
It shows why specialised luxury launches can be financially meaningful even when the number of apartments is small.
DLF can generate almost one-tenth of annual sales guidance from 172 residences because the ticket size is so high.
This Is Also a Lesson in How Luxury Changes Developer Economics
Suppose two developers each sell 172 homes.
One sells at ₹1 crore per home.
The other averages ₹11.5 crore.
Their unit volumes are identical.
Their booking values are radically different.
This is why India's premiumisation cycle can support strong developer sales values even when unit-sales growth is less dramatic.
The Aureva is an extreme illustration of that dynamic.
But High Sales Value Does Not Tell Us the Margin
₹1,985 crore is reported sales value.
It is not project profit.
The reviewed evidence does not disclose The Aureva's:
- land cost;
- construction cost;
- marketing cost;
- financing cost;
- operating commitments;
- project margin; or
- cash collected to date.
It would therefore be inappropriate to infer project profitability from sales bookings alone.
Could Senior Living Become a New Luxury-Housing Differentiator?
Possibly.
Luxury developers increasingly need more than marble, clubhouses and larger apartments to differentiate projects.
Specialisation can create another layer of value.
Developers can design communities around:
- seniors;
- wellness;
- branded residences;
- hospitality;
- golf;
- waterfront living;
- managed services; or
- other lifestyle propositions.
Senior living has one distinctive advantage.
It addresses demographic and practical needs rather than relying entirely on aspirational branding.
That could make the category more durable if developers execute the operating model well.
The Bigger Opportunity May Not Be at ₹11.5 Crore
The Aureva proves that a wealthy niche exists.
The larger societal opportunity is different.
India's ageing population will create demand across income groups.
The harder real estate challenge is whether developers can create senior-friendly housing at much lower ticket sizes while still funding healthcare, accessibility, maintenance and professional management.
The Aureva does not answer that question.
Its economics are built around luxury pricing.
What Would Prove the Category Is Scaling?
One sell-out is not enough.
Stronger evidence would include:
Repeat projects from DLF
If DLF launches more senior communities, that would indicate management sees a repeatable opportunity.
Entry by major competing developers
Multiple credible developers would broaden the category.
Success outside Gurugram
Absorption across different cities would reduce location-specific uncertainty.
Wider price points
Projects below the ultra-luxury level would demonstrate broader demand.
Strong resale markets
Resale liquidity would show that the product remains attractive beyond the initial launch.
Sustainable operating quality
Senior housing depends on services continuing after possession.
What Could Go Wrong?
The risks are different from ordinary luxury housing.
A project can be physically excellent but operationally disappointing.
Potential issues include:
- high recurring service charges;
- healthcare-service quality;
- inadequate staffing;
- ageing infrastructure;
- poor community management;
- limited resale liquidity;
- service-provider changes; and
- mismatch between residents' changing care needs and the services available.
These are category-level considerations.
The reviewed evidence does not establish that they are problems at The Aureva.
What Should Buyers Ask Before Purchasing Senior Living?
Buyers should look beyond the apartment.
Important questions include:
Who will operate the community?
What healthcare services are guaranteed?
What happens during a medical emergency?
Which services require additional payment?
How will maintenance charges be determined?
What accessibility standards are built into residences and common areas?
Can residents add care services as their needs change?
How transferable or resalable is the property?
The answers can materially affect the long-term value of a retirement home.
What Should Real Estate Investors Watch?
For investors, The Aureva creates an interesting signal rather than a complete investment thesis.
Watch:
- repeat senior-living launches;
- absorption speed;
- ticket sizes;
- NRI participation;
- project margins where disclosed;
- geographic expansion;
- competing supply; and
- whether specialised housing creates pricing power.
If multiple projects achieve similar outcomes, luxury senior living could become a meaningful sub-segment of India's premium residential market.
If replication proves difficult, The Aureva may instead remain an exceptional project shaped by DLF's brand, Gurugram and limited inventory.
The Aureva Has Proven Demand, Not Yet Scalability
DLF has already answered one question.
Can 172 buyers be found for luxury retirement residences averaging approximately ₹11.5 crore in Gurugram?
Yes.
The project sold out.
The harder questions remain unanswered.
Can the product be repeated?
Can it work in other cities?
Can competitors reproduce it?
Can senior housing move beyond ultra-luxury pricing?
Can operators maintain service quality for decades?
Those questions will determine whether The Aureva is remembered as an unusually successful luxury launch or an early marker of a much larger change in Indian residential real estate.
Frequently Asked Questions
Is luxury senior living becoming popular in India?
The Aureva's sell-out demonstrates strong demand for one high-end Gurugram project. More projects, cities and price points would be needed to establish broader market-scale adoption.
Why did DLF The Aureva sell for ₹1,985 crore?
The project contains 172 luxury residences with average price realisation of approximately ₹11.5 crore. DLF also positions it around retirement-focused healthcare, accessibility, wellness, hospitality and community infrastructure.
Are senior living homes only for wealthy buyers?
No. Senior housing can exist across different price and care categories. The Aureva specifically represents the luxury end of the market.
Is senior living the same as assisted living?
No. Senior living can include independent retirement communities, assisted living and higher-care environments. The reviewed sources do not characterise The Aureva as a comprehensive assisted-living facility.
Why is NRI demand important for senior housing?
Business Standard reports that NRIs accounted for 25% of The Aureva's buyers. The data identifies NRIs as a meaningful buyer group, although their individual purchase motivations were not disclosed.
Is ₹11.5 crore the price of every apartment at The Aureva?
No. It is the reported average price realisation. Individual transaction values can differ.
Is ₹1,985 crore DLF's profit from The Aureva?
No. It is reported project sales value. Project-level profit and margin were not disclosed in the reviewed evidence.
What would show that luxury senior housing is scalable?
Repeat launches, successful projects across multiple cities, entry by competing developers, broader ticket sizes, sustained operating quality and healthy resale demand would provide stronger evidence.
Sources
Click on article title to view article.
“DLF completes sell-out in its senior living project for ₹1,985 crore” published on 4 October 2026 in Business Standard
“DLF sells all 172 luxury senior living homes in Gurugram for Rs 1,985 crore” published on 4 October 2026 in Moneycontrol
“DLF has reported Rs 1985 crore sale from its first senior living project in Gurgaon.” published on 4 October 2026 in The Economic Times
Evidence Caveats
- The argument that luxury senior living could become a specialised premium residential category is editorial analysis.
- One 172-unit sell-out cannot establish the size or growth rate of India's overall senior-living market.
- ₹1,985 crore is sales value, not reported project profit, revenue recognised or cash collected.
- The 9.9% comparison with DLF's FY27 sales guidance is a Vantage-derived scale indicator.
- The reviewed sources do not provide a buyer survey explaining why residents or their families selected the project.
- The NRI share is reported as 25%, but a precise unit count is unavailable.
- Project margin, construction cost, cancellation rate, resale liquidity, maintenance charges, long-term service costs and future appreciation are unavailable.

From TatvaOps
Property Purchase
Financing your project?
Explore credit and milestone-secured payment options with Tatva Finance.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this InSights article is filed under InSights.
1 reply already on Forums
More from Real Estate
LTCG Tax Debate: Should You Delay Selling Investments?
Could waiting for LTCG tax relief cost more than it saves? With proposals under discussion, we examine how your current tax liability, market exposure and cash deadline should shape a planned investment sale.
Blackstones India Bet: What Should You Check?
Blackstone’s $100-billion India ambition is a useful signal. For your own money, the harder questions are access, valuation, cash flow and risk. Here is what to check before turning institutional optimism into a personal investment decision.
Senior Living: Buy the Home, Examine the Services: what most readers overlook
Rustomjee’s senior-living evaluation raises a household question: can you afford and rely on the services after buying the home? We examine recurring charges, operator responsibilities, changing support needs and exit flexibility.
Inline Intelligence
Key Insight Actions
Connected knowledge for Real Estate Insights
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Topic hubs
Conclusion Intelligence
Related Discussions
Was this helpful?
Let us know what you think