
LTCG and STT: Review Reports Do Not Mean a Tax Cut

Founder & construction tech innovator. Building data-driven platforms for project management, site intelligence, and real estate market analysis across India's urban growth centers.
Summary
Finance Minister Nirmala Sitharaman’s comments on equity taxation have reopened a consequential debate for investors. Speaking at the Bloomberg New Economy Forum in New Delhi on 13 October, she welcomed views on long term capital gains tax and securities transaction tax without committing to changes. Separately, Moneycontrol reported that the Centre was examining proposals to review equity LTCG taxation, citing an unnamed senior government official. That makes the discussion worth following. It does not establish a revised tax rate, an exemption or an implementation date. What has actually been said?
Published on
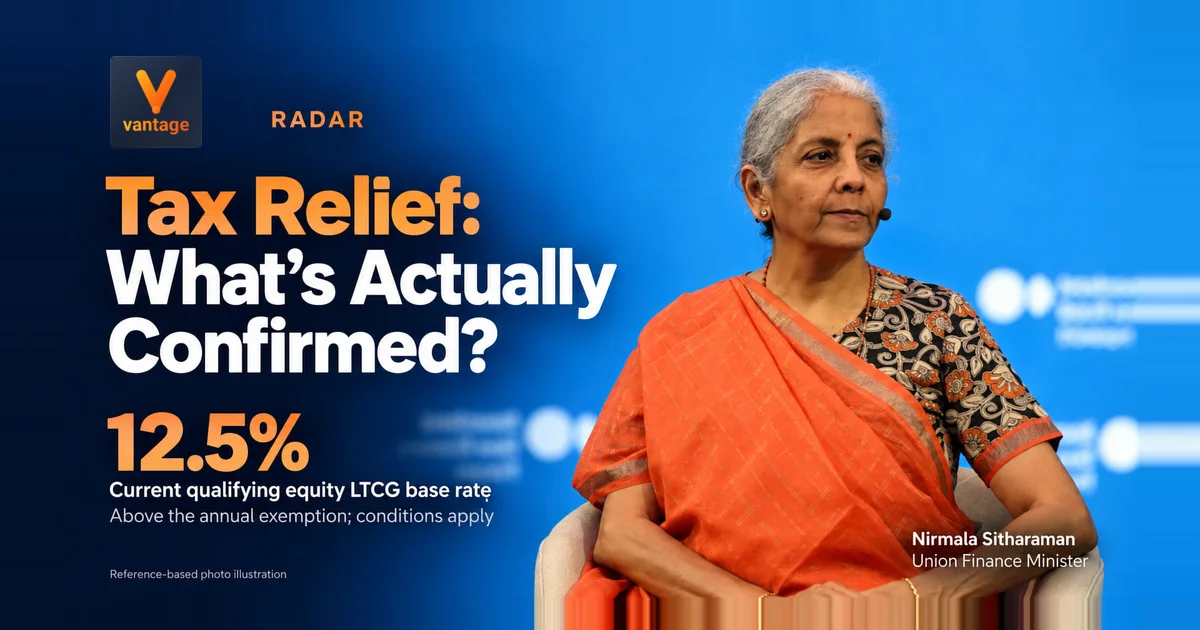
Nirmala Sitharaman beside the question “Tax Relief: What’s Actually Confirmed?” and the current 12.5% qualifying equity LTCG base rate.
Inline Intelligence
Finance Minister Nirmala Sitharaman’s comments on equity taxation have reopened a consequential debate for investors. Speaking at the Bloomberg New Economy Forum in New Delhi on 13 October, she welcomed views on long-term capital gains tax and securities transaction tax without committing to changes.
Separately, Moneycontrol reported that the Centre was examining proposals to review equity LTCG taxation, citing an unnamed senior government official.
That makes the discussion worth following. It does not establish a revised tax rate, an exemption or an implementation date.
What has actually been said?
The Finance Minister acknowledged questions from domestic and overseas investors about capital gains taxation, STT and the treatment of different asset classes.
Her remarks indicated willingness to listen while Budget preparations were underway. They did not specify which proposal, if any, the government would adopt.
The distinction matters because three different developments can appear under similar headlines: investors requesting relief, officials examining proposals and the government changing the law. The cited reporting establishes the first two, not the third.
Why are LTCG and STT discussed together?
They affect investment outcomes through different mechanisms.
Long-term capital gains tax concerns qualifying profits when an investment is sold. STT applies to specified securities transactions and is calculated on the applicable transaction value, rather than the investor’s profit.
Under the official equity LTCG provision reviewed for this article, qualifying gains above an aggregate annual threshold of ₹1.25 lakh attract a 12.5% base tax rate. Applicable conditions, surcharge and cess must also be considered.
NSE’s published schedule separately lists STT of 0.1% on delivery-based equity-share purchases and 0.1% on sales. Other transaction categories have different treatment.
Consequently, a change to one levy would not automatically remove the other.
A review is not a confirmed benefit
A workable tax change needs more than a statement of interest. Investors would need to know the covered assets, applicable rate or threshold, eligibility conditions and effective date under the relevant legal provisions.
Without those details, a headline about possible relief cannot determine the tax on a planned sale.
Nor should this debate be read as evidence that all investment taxes have remained unchanged. NSE’s schedule already distinguishes derivatives STT rates effective from 1 April 2026 from earlier rates. The present question is whether the October discussion produces a further change.
What should readers watch next?
The next consequential development would be an attributable government proposal or legal measure containing specific terms. Any announcement would then need to be checked for its legal status and commencement provisions.
Meanwhile, market uncertainty remains a separate consideration. We explained what expected volatility can and cannot tell investors in this related report -> India VIX Rises Sharply From September Levels.
A possible tax concession and the market value of an investment are different variables. Neither can be assumed from the other.
Sources
Click an article title to view the source.
- FM Sitharaman says open to hearing views on LTCG tax review published on 13 October 2026 in Moneycontrol.
- Centre examining proposals to review LTCG tax on equities, says senior government official published on 13 October 2026 in Moneycontrol.
- Section 198: Tax on long-term capital gains in certain cases, Income Tax Department, Income-tax Act, 2025, website version marked 2026; accessed on 15 October 2026.
- SEBI Turnover Fees, STT and Other levies, NSE India, updated on 17 April 2026; accessed on 15 October 2026.
- India VIX Rises Sharply From September Levels published on 13 October 2026 in Vantage Radar.
Reporting limitation: The proposal-review claim relies on Moneycontrol’s unnamed official. The cited reporting does not establish an approved October tax cut or its effective date.
Which detail would you need before treating a tax-relief headline as relevant to your investments: the covered assets, eligibility conditions or effective date? Explain your reasoning in the attached forum discussion.
From TatvaOps
Property Development
Developing a property?
Structured oversight for multi-unit and investor-led builds.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this Radar article is filed under Radar.
More from Real Estate
Bharat Future City Core Works Estimated at 18000 Crore
Telangana's reported estimate for roads, utilities and other core infrastructure at Bharat Future City is close to ₹18,000 crore. A master plan unveiling is expected in December.
Telangana to Return Title Deeds to Housing Beneficiaries
Telangana plans to return original housing documents to nearly seven lakh beneficiaries of older government schemes. District collectors have been asked to arrange the return.
Amrapali Assets Could Be Auctioned. Will That Bring Your Home Closer?
When a court considers recovering money from a developer's assets, a homebuyer may reasonably ask: will that money help finish my flat? The answer depends on several steps that cannot be assumed from a hearing alone. Properties must be identified, any applicable attachment and sale process must be…
Inline Intelligence
Key Insight Actions
Connected knowledge for Taxation
Move between tutorials, discussions, Studio, and hubs without losing context.
Conclusion Intelligence
Was this helpful?
Let us know what you think