
REITs and InvITs Get New Depository Receipt Rules
Summary
SEBI has issued separate frameworks for depository receipts backed by units of Real Estate Investment Trusts and Infrastructure Investment Trusts, creating an additional route for overseas participation in Indian property and infrastructure assets. The circulars, dated 2 November 2026, follow the earlier regulatory amendments enabling the instruments. The development establishes an issuance framework; it does not establish that a particular trust has completed an offering or attracted fresh investment. The official documents are available here Framework for Issuance of Depository Receipts on Units of REITs and Framework for Issuance of Depository Receipts on Units of InvITs.
Published on
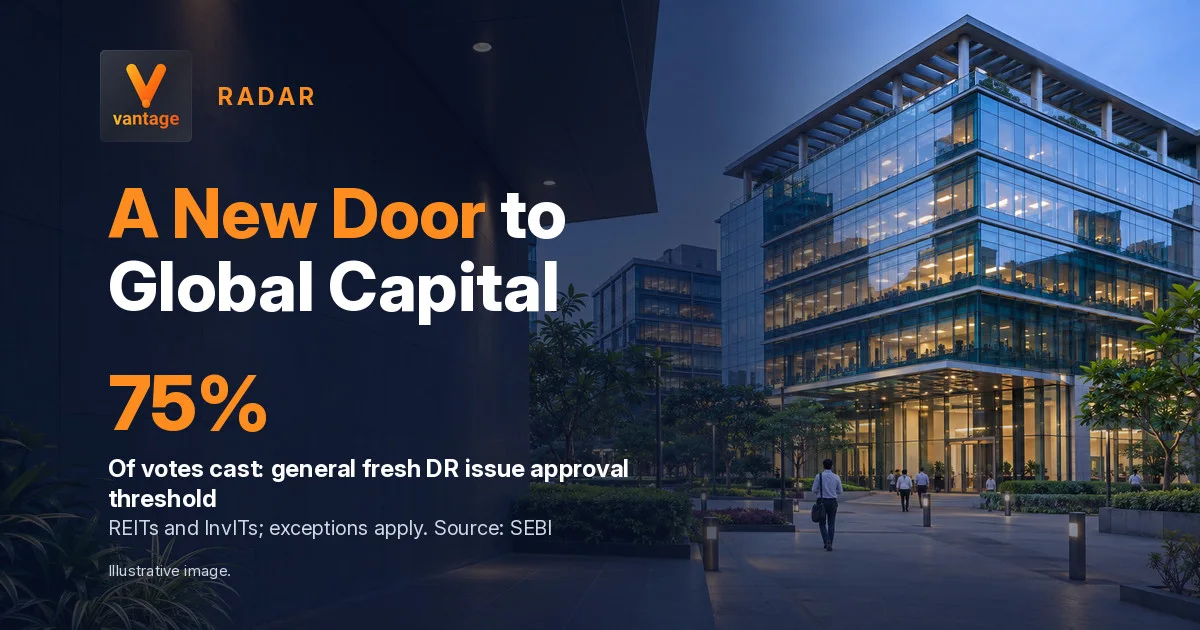
Illuminated office buildings connect India’s commercial-property market with SEBI’s new depository-receipt framework for REITs and InvITs. The callout highlights the general voting threshold, with exceptions noted.
Inline Intelligence
SEBI has issued separate frameworks for depository receipts backed by units of Real Estate Investment Trusts and Infrastructure Investment Trusts, creating an additional route for overseas participation in Indian property and infrastructure assets.
The circulars, dated 2 November 2026, follow the earlier regulatory amendments enabling the instruments. The development establishes an issuance framework; it does not establish that a particular trust has completed an offering or attracted fresh investment.
The official documents are available here -> Framework for Issuance of Depository Receipts on Units of REITs and Framework for Issuance of Depository Receipts on Units of InvITs.
How the route works
A depository receipt is a foreign-currency instrument backed by underlying securities held with a domestic custodian. Under the framework, the underlying trust units may be newly issued or transferred by existing unitholders.
Moneycontrol reports that the receipts can be listed on India International Exchange and NSE International Exchange in GIFT City. Holders and their beneficial owners cannot be persons resident in India.
The report explains the structure and conditions -> SEBI allows REITs, InvITs to issue depository receipts on GIFT City exchanges; sets 75 percent approval norm.
Unitholder approval remains important
For fresh DR issues, the framework generally requires support from at least 75% of votes cast. Exceptions cover specified simultaneous initial offerings and subsequent offerings within an already approved limit.
That qualification matters. The threshold should not be described as approval from 75% of all outstanding units, or as a requirement for a new vote on every subsequent offering.
Vantage previously examined the broader changes to REIT voting and the enabling provision for receipts -> SEBI Shifts REIT Approval Rule to Votes Cast. The November circular adds the detailed issuance framework, making this a distinct implementation update.
A funding option is different from a funding outcome
The economic consequences will depend on how individual trusts use the route.
An offering backed by newly issued units can bring capital into the trust. A transfer of existing units changes the ownership of those units and should not automatically be counted as new money available for acquisitions or debt reduction.
For existing investors, the next meaningful evidence will be trust-specific announcements: the transaction structure, pricing, intended use of proceeds and implications for each unit.
An additional access channel may broaden funding choices. It does not, by itself, improve occupancy, infrastructure revenue, distributions or investment returns.
Sources
Click an article title to view the source.
- Framework for Issuance of Depository Receipts on Units of REITs published on 2 November 2026 by SEBI.
- Framework for Issuance of Depository Receipts on Units of InvITs published on 2 November 2026 by SEBI.
- SEBI allows REITs, InvITs to issue depository receipts on GIFT City exchanges; sets 75 percent approval norm published on 2 November 2026 in Moneycontrol.
- SEBI Shifts REIT Approval Rule to Votes Cast published on 31 October 2026 in Vantage Radar.
Evidence Caveats
SEBI’s circular listings and indexed REIT circular text were accessible, but complete direct PDF access was inconsistent. Combined REIT and InvIT implementation details are also attributed to Moneycontrol. No completed offering, capital inflow or return improvement is asserted.
If a trust you follow proposes this route, which disclosure would matter most to you: pricing, use of proceeds or the effect on distributions per unit? Explain your reasoning in the attached forum discussion.
From TatvaOps
Development
Developing a property?
Structured oversight for multi-unit and investor-led builds.
Free quotes · Verified contractors · tatvaops.com
Discuss this article
Join the conversation
Continue this discussion on Forums. A board named like this Radar article is filed under Radar.
More from Real Estate
Haryana RERA Rejects Delayed-Flat Compensation Claim
A Haryana RERA adjudicating officer has rejected a homebuyer’s compensation claim against Ireo Grace Realtech in a dispute involving a delayed apartment at The Corridors project in Gurugram. According to news reports, the officer dismissed the complaint on 7 October 2026 , citing an earlier finding…
Equity Mutual Fund Inflows Ease in October as Debt Funds Attract Fresh Money
Equity mutual funds attracted approximately ₹32,994 crore in net inflows in October 2026, down nearly 14% from ₹38,307 crore in September, according to reports citing data from the Association of Mutual Funds in India. The decline means the category received less net new money than in the previous…
Supertech Projects: NBCC Targets 9,600 Crore in Work Awards This Quarter
NBCC expects to award approximately ₹9,600 crore of work associated with stalled Supertech projects during the October–December 2026 quarter, according to a report by ETRealty. The target follows NBCC’s earlier announcement that it had floated tenders for construction and related work across 16…
Inline Intelligence
Key Insight Actions
Connected knowledge for Regulatory Updates
Move between tutorials, discussions, Studio, and hubs without losing context.
Related discussions
Topic hubs
Conclusion Intelligence
Related Discussions
Was this helpful?
Let us know what you think